
The displayed weekly fund total improved, but an unreported issuer entry leaves confirmation incomplete.
Reporting week: October 19 to 25, 2026. Evidence cutoff: October 25, 2026, 19:04:38 PDT / October 26, 02:04:38 UTC.
Bitcoin’s completed daily references stayed above $80,000, but the margin narrowed. Coin Metrics’ October 25 reference was $80,038.91, down 2.31% from October 18. Farside’s displayed October 19 to 23 totals add to +$301.2 million, while its displayed twenty-session total is −$365.0 million. Both fund totals are provisional because the October 23 VanEck HODL entry is unreported. A positive displayed week therefore does not establish the complete demand confirmation required by the prior issue.
The practical consequence is a cautious assessment with less room above the retained daily threshold. There is evidence of buying early in the week, but the longer-window display has weakened and the week ended with withdrawals. Neither a temporary spot breach nor a provisional positive flow total can settle a test defined on different observations.
Executive snapshot
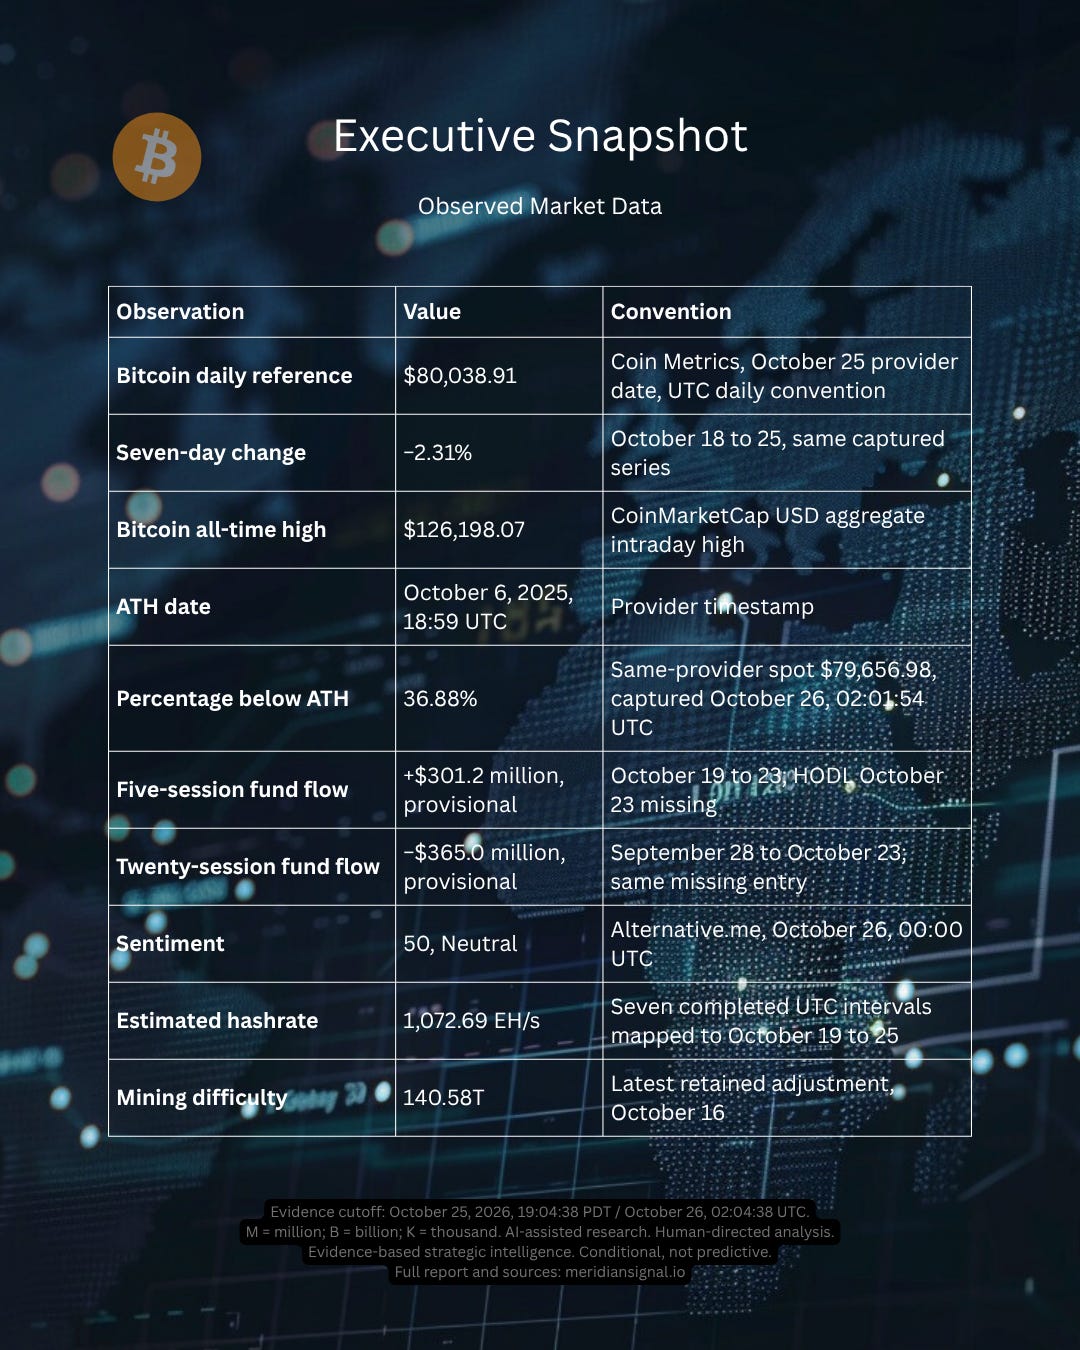
EH/s means exahashes per second; T means trillion. The daily reference and spot snapshot have different providers and observation conventions. The spot comparison is not used to calculate the weekly return.
Last issue’s test
WCIR 031, displayed publicly as October 20, retained three consecutive completed Coin Metrics daily references above $80,000, a complete positive October 19 to 23 fund window and a positive twenty-session total no lower than +$1,719.6 million. The separate deterioration case required three consecutive daily references below $76,000 plus a complete negative fund week.
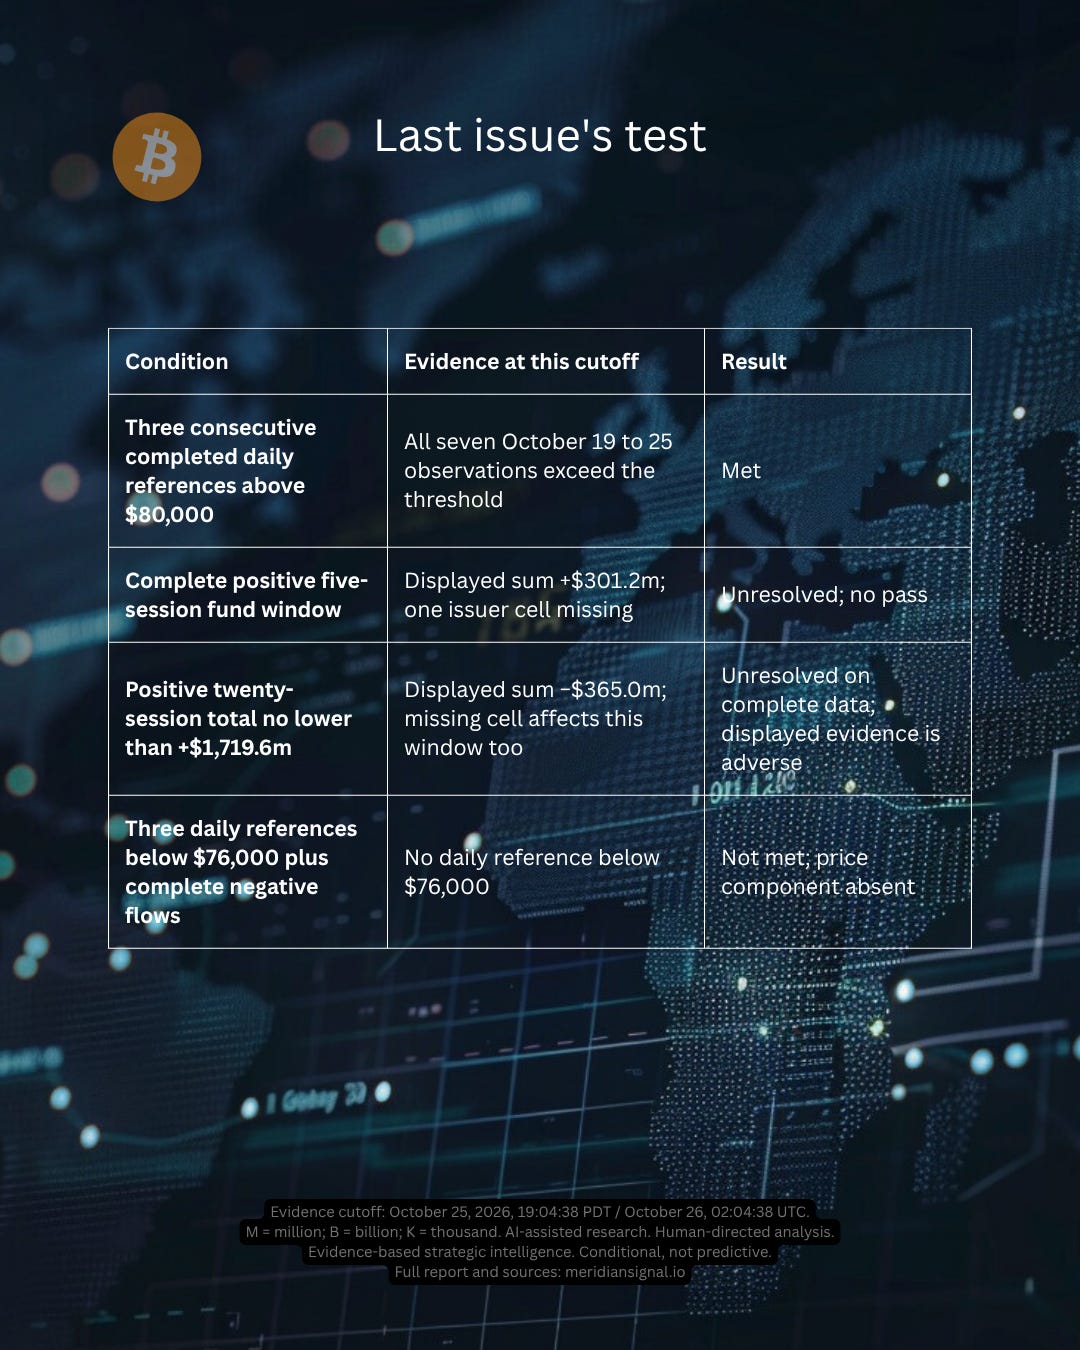
The levels and durations are unchanged. The current evidence supports a qualified uneven-recovery assessment rather than full constructive confirmation. It also does not establish the specified deterioration combination. These levels are intermediate research triggers, not validated support, resistance or trading instructions.
Price structure and fund demand
The seven daily references are $81,918.20, $82,898.91, $84,176.08, $81,257.02, $80,924.18, $80,699.31 and $80,038.91. The last observation is only $38.91 above $80,000. All seven satisfy the daily condition, but the falling observations after October 21 make that pass less reassuring than a simple binary label suggests. That is analyst interpretation, not a new numerical indicator.
Farside’s displayed five session totals are +$526.7m, +$23.2m, +$524.8m, −$635.6m and −$137.9m. The first three add to +$1,074.7m; the last two subtract $773.5m. October 19 was the strongest session and October 22 the weakest. The Friday figure and resulting week remain provisional. Missing is not zero.
IBIT’s displayed five-session contribution is +$565.7m, while FBTC contributes −$116.6m. The net improvement is therefore not evidence of uniform participation across issuers. Fund flows describe this U.S. spot-fund sample, not all institutional demand or all Bitcoin ownership.
The current displayed twenty-session sum covers September 28 to October 23. The preceding complete window, September 21 to October 16, remains +$1,719.6m in this capture. The windows share fifteen sessions. The displayed difference is −$2,084.6m because +$2,385.8m from September 21 to 25 rolls out and the provisional +$301.2m enters. This is an overlapping-window comparison, not two independent twenty-session samples.
The missing HODL observation prevents a definitive completed-window conclusion. Other public tables differ in issuer entries and totals, so they are not silently spliced into Farside. The next decisive evidence is the reported issuer value and a refreshed, reconciled history. Until then, the displayed sign and change are observations about available data, not a completed demand verdict.
ATH and historical drawdown
CoinMarketCap’s retained statistics identify an actual aggregate intraday ATH of $126,198.06960343386, reached October 6, 2025 at 18:59 UTC. The same object supplies spot $79,656.97916973327. Using unrounded inputs, 100 × (ATH − spot) / ATH equals 36.8793996453%, displayed as 36.88% below ATH. This is a retrieval-time snapshot captured at 02:01:54 UTC, about three minutes before the cutoff; a separate quote-update timestamp was not exposed for that object.
CoinGecko independently retains a $126,080 aggregate high on October 6, 2025 at 10:57:42 UTC. The providers corroborate the date and approximate scale, not the identical tick. Different aggregation inputs, filtering and timestamps account for non-identical records; the two highs are not averaged. The retained current records show no replacement ATH. Coin Metrics weekly returns remain a separate, unspliced daily series.
Distance below a record is historical context. It is not a valuation discount or evidence that a return to the old high is inevitable.
Macro and liquidity
The Federal Reserve’s October 23 H.15 release shows the five-year inflation-indexed Treasury yield at 2.33% on October 22, versus 2.58% on October 15 in the prior report, a 25 basis point decline. Within the current release, October 16’s 2.52% to October 22’s 2.33% is a separate 19 basis point change. Neither is described as a completed Friday-to-Friday week. Lower real yields reduce one competing-return measure, but do not prove funds will move into Bitcoin.
The October 22 H.4.1 release reports weekly-average reserve balances of $2,962.607 billion for the week ended October 21, down $59.533 billion. The Treasury General Account averaged $952.002 billion, up $68.629 billion. These are daily averages, not Wednesday-only balances. Treasury cash accumulation and lower reserves make these selected measures less supportive, even as the real yield declined. They do not comprise a comprehensive global-liquidity model or identify actual Bitcoin purchases.
No comparable whole-market stablecoin growth estimate is assigned. The prior edition’s native-peg versus USD-valued aggregation problem remains unresolved in this edition; its old readings are not carried forward as current. That limits conclusions about stablecoin liquidity and cannot be interpreted as no growth or no change.
Corporate ownership and financing
Strategy’s October 19 filing reports 267 bitcoin acquired for $22.1 million during October 12 to 18, bringing holdings to 848,517 bitcoin at October 18. The company reports an average acquisition price of $82,900 including fees and expenses. Funding was $22.0 million in common-share proceeds and $0.1 million in USD Cash. The acquisition period precedes this reporting week; the disclosure is new this week.
The same filing reports $193.1 million of STRC preferred-share repurchases, $45.5 million of preferred dividends paid from the separate USD Reserve, and ending balances of $447.3 million USD Cash and $4.83 billion USD Reserve. Its digital-credit repurchase authorization increased from $2 billion to $3 billion, with $1.16 billion remaining. Authorization is not completed expenditure, and repurchase capacity is not Bitcoin purchase funding.
October 20 proxy materials still describe daily dividends as conditional on approval and declaration, with the special meeting scheduled for October 28. Future dividend mechanics are not treated as implemented adoption. The relevant Bitcoin inference remains conditional: continued purchases provide demand, but competing repurchases, distributions and financing obligations constrain flexibility. One company’s holdings do not establish all owners’ intentions or a price floor.
Network operation and miner economics
Mempool’s seven completed daily intervals average 1,072.69 EH/s, versus 1,031.47 EH/s in the preceding seven intervals, an increase of 4.00%. Each endpoint maps to the preceding completed UTC day. The final endpoint is October 26 at 00:00 UTC and represents October 25. Difficulty remains 140.57768 trillion, following the October 16 adjustment of +5.9237% at block 971712. A daily estimate and a difficulty period are different measurements.
Hashrate Index displayed $35.87 per petahash per day in the capture. This measures expected mining revenue, not profit; no matched weekly-profit claim is made. Electricity, equipment efficiency, fees and financing affect individual miners differently. Rising network computation does not establish profitable miners, decentralization, durable holders or a price floor.
The Bitcoin Core advisory index was reviewed as scoped software evidence. An advisory index is not a real-time audit of all nodes or proof of universal software adoption. No comprehensive protocol-safety certification is made.
Custody and operational risk
The retained Bitquery investigation continues to describe an estimated $102.0 million from 335 wallets across six chains, with its figures identified as verified October 16. This is an investigator’s multi-asset estimate, not $102 million in Bitcoin and not a new loss total for this reporting week. Its page discusses reseller provenance and movement of stolen funds; it does not certify containment across every device or custodian.
The earlier custody watch therefore remains open. No new claim of wider exposure or successful containment is justified merely by rereading an older update. Comprehensive custody coverage was not established. The evidence that would matter is verified scope, remediation and any continuing loss, separately from Bitcoin consensus and mining computation.
Changes, contrary evidence and Horizon Posture
Alternative.me sentiment is 50, Neutral, at October 26, 00:00 UTC, down from 59 a week earlier. It is partly market-derived and is not counted as independent confirmation of fund demand.
The strongest constructive evidence is that the daily condition still passes, the displayed weekly fund sum is positive and the selected real yield fell. The strongest contrary evidence is that the daily margin narrowed, the last two fund sessions reversed much of the early buying, the displayed longer total turned negative, and reserves declined. Missing fund data qualifies the magnitude and final test result; it does not justify ignoring the adverse display.
Long term: Constructive and thesis-led, with custody watch. This remains a qualitative thesis stance. Persistent protocol impairment, wider verified custody failures or unsustainable financing would weaken it. Verified containment and resilient recurring use would strengthen it. This week’s observations alone do not prove either outcome.
Medium term: Conditional, with weaker displayed longer-window demand. The provisional positive week is encouraging relative to two negative weeks, but a recovery upgrade requires complete inflows, broader participation and a reconciled longer window. The missing entry keeps that conclusion unresolved.
Tactical: Cautious, with a narrow daily-price margin. Price persistence passes, but joint price-and-flow confirmation does not. Keep the same $80,000 and $76,000 levels and three-completed-day duration. Do not relabel an intraday spot move as failure of a daily test.
Conditional paths and next tests
Constructive continuation requires three consecutive completed daily references above $80,000, a complete positive next five-session fund window, and a positive twenty-session total no lower than its completed preceding comparable window. The next standard fund window is October 26 to 30. This edition’s provisional −$365.0m is not frozen as a completed benchmark: first resolve the missing entry and visibly record the completed base and any revisions. Until then, dependent comparisons remain unresolved.
Uneven recovery remains the closest qualified description while price persistence survives and demand evidence is mixed or incomplete. The deterioration case still requires three consecutive completed daily references below $76,000 together with a complete negative five-session flow window. Neither a spot breach nor missing data supplies a pass or failure by itself.
Meridian strategic conclusion
The positive displayed week offers a reason to watch for demand repair. The weakened longer display and narrowing daily-price margin offer a reason to withhold a recovery upgrade. The next useful step is complete evidence, not a stronger adjective. ATH context, lower real yields and rising computation do not replace that demand test.
Sources
price, retrieved 2026-10-26T02:01:54.293562+00:00.
cmc, retrieved 2026-10-26T02:01:54.772381+00:00.
gecko, retrieved 2026-10-26T02:01:54.350059+00:00.
flows, retrieved 2026-10-26T02:01:55.216120+00:00.
network, retrieved 2026-10-26T02:01:55.423526+00:00.
sentiment, retrieved 2026-10-26T02:01:54.228982+00:00.
h15, retrieved 2026-10-26T02:01:54.422931+00:00.
h41, retrieved 2026-10-26T02:01:54.468485+00:00.
sec, retrieved 2026-10-26T02:01:57.110015+00:00.
archive, retrieved 2026-10-26T02:01:57.714276+00:00.
prior, retrieved 2026-10-26T02:01:57.250617+00:00.
core, retrieved 2026-10-26T02:01:56.674809+00:00.
custody, retrieved 2026-10-26T02:01:58.064092+00:00.
hashprice, retrieved 2026-10-26T02:01:58.107034+00:00.
Editorial Note
The Bitcoin Evidence-Led Series distinguishes sourced observations, descriptive calculations and Meridian’s qualitative assessments. Each edition reflects the evidence available at its stated cutoff; source data may subsequently be revised.
Meridian Signal uses artificial intelligence to assist source discovery, comparison, drafting and arithmetic verification. Final review and editorial responsibility rest with Meridian Signal. Material limitations are disclosed, and corrections to prior reporting are identified explicitly.
Research Disclosure
This report provides general informational and educational research, not personalized investment, legal or tax advice or an instruction to transact. Bitcoin is volatile, and loss of principal is possible. Assessments involve uncertainty; conditions and scenarios do not guarantee outcomes.
Meridian Signal
Bold clarity at the right time.
Independent strategic intelligence on capital regimes, digital infrastructure and systemic risk.
AI-assisted. Human-directed.
Evidence-based strategic intelligence. Conditional, not predictive.
Questions or corrections: contact@meridiansignal.io