
Seven daily references stayed above the retained price trigger, while a complete fund-flow window recorded $678.9 million of net outflows.
Reporting week: October 5 to 11, 2026. Evidence cutoff: October 11, 2026 at 7:10:53 p.m. PDT / October 12 at 02:10:53 UTC.
Bitcoin kept the price condition that supported its recovery. Fund demand moved in the opposite direction. Coin Metrics’ October 11 daily reference was $83,636.61, down 3.33% from October 4, but all seven completed daily references during the week remained above $80,000. Farside’s complete October 5 to 9 window recorded $678.9 million of net outflows. [1,2]
That changes the assessment. Last issue’s demand question was unresolved because an issuer entry was missing. This week’s demand condition failed on complete displayed data. Meridian’s overall reading is uneven recovery, with weaker fund demand. The long-term thesis remains constructive and conditional; the tactical posture moves to cautious, with price persistence intact. These are qualitative assessments, not transaction instructions.
Executive snapshot
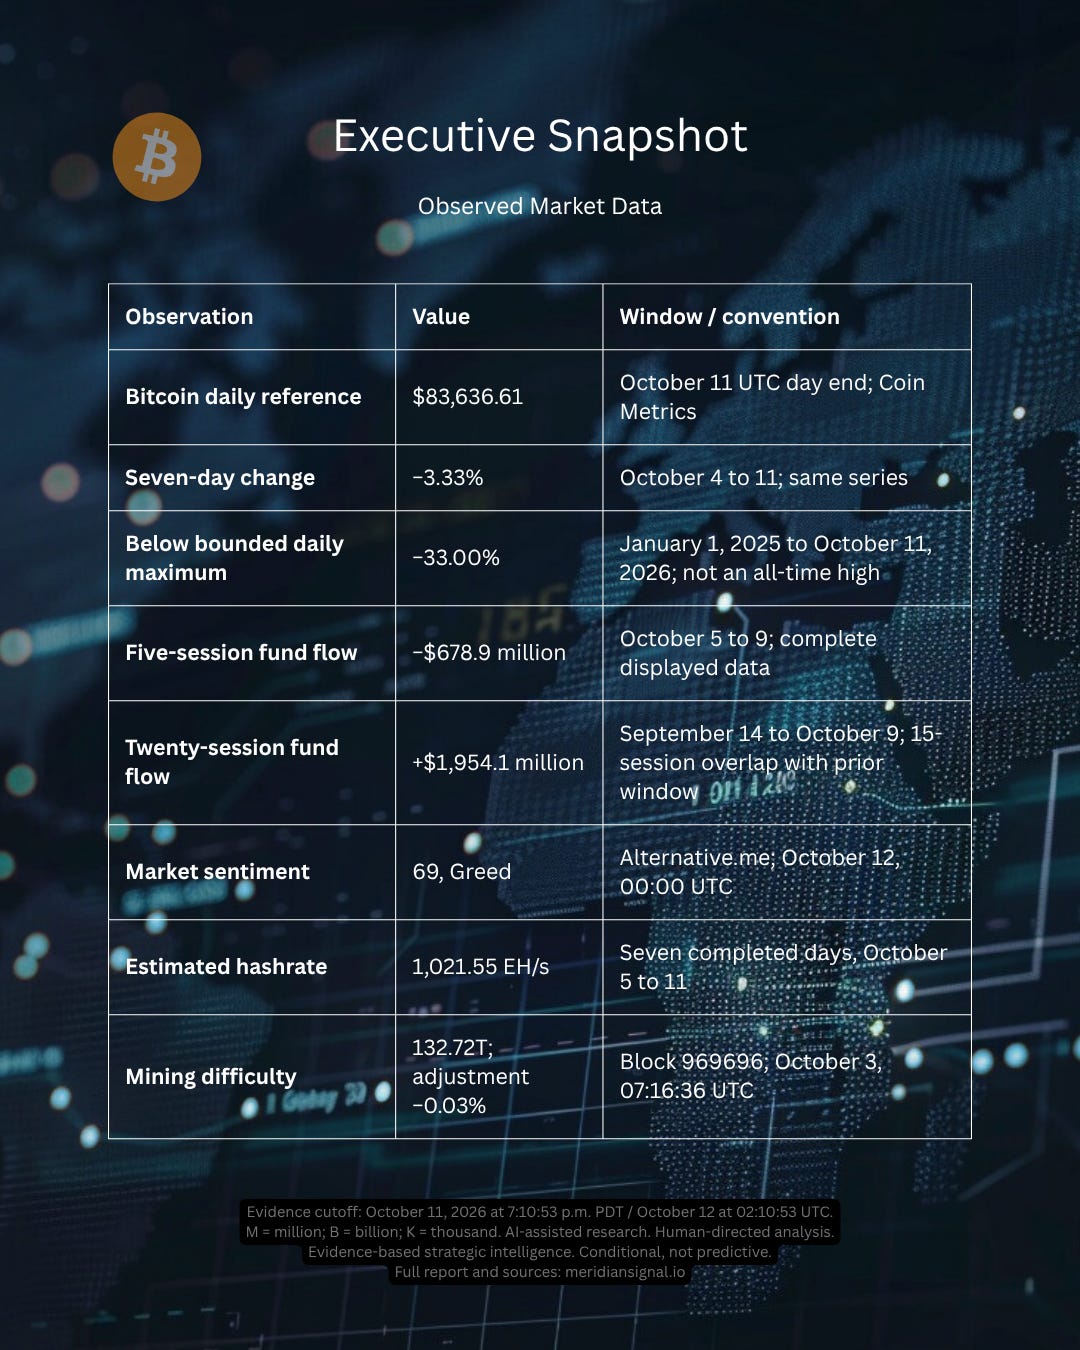
The bounded maximum is $124,824.45 on October 6, 2025, within the retrieved January 1, 2025 to October 11, 2026 history. It is a daily reference, not an intraday high or an all-time-high claim. EH/s means exahashes per second; T abbreviates trillion in the dimensionless difficulty figure. Source data may be revised after this cutoff. [1–4]
Last issue’s test
WCIR 029, published October 5, retained three joint continuation conditions: three consecutive completed Coin Metrics UTC daily references above $80,000; a complete positive October 5 to 9 fund-flow window; and a positive twenty-session total no lower than the prior comparable completed total. It also retained a separate deterioration combination: three consecutive daily references below $76,000 together with a complete negative five-session flow window.
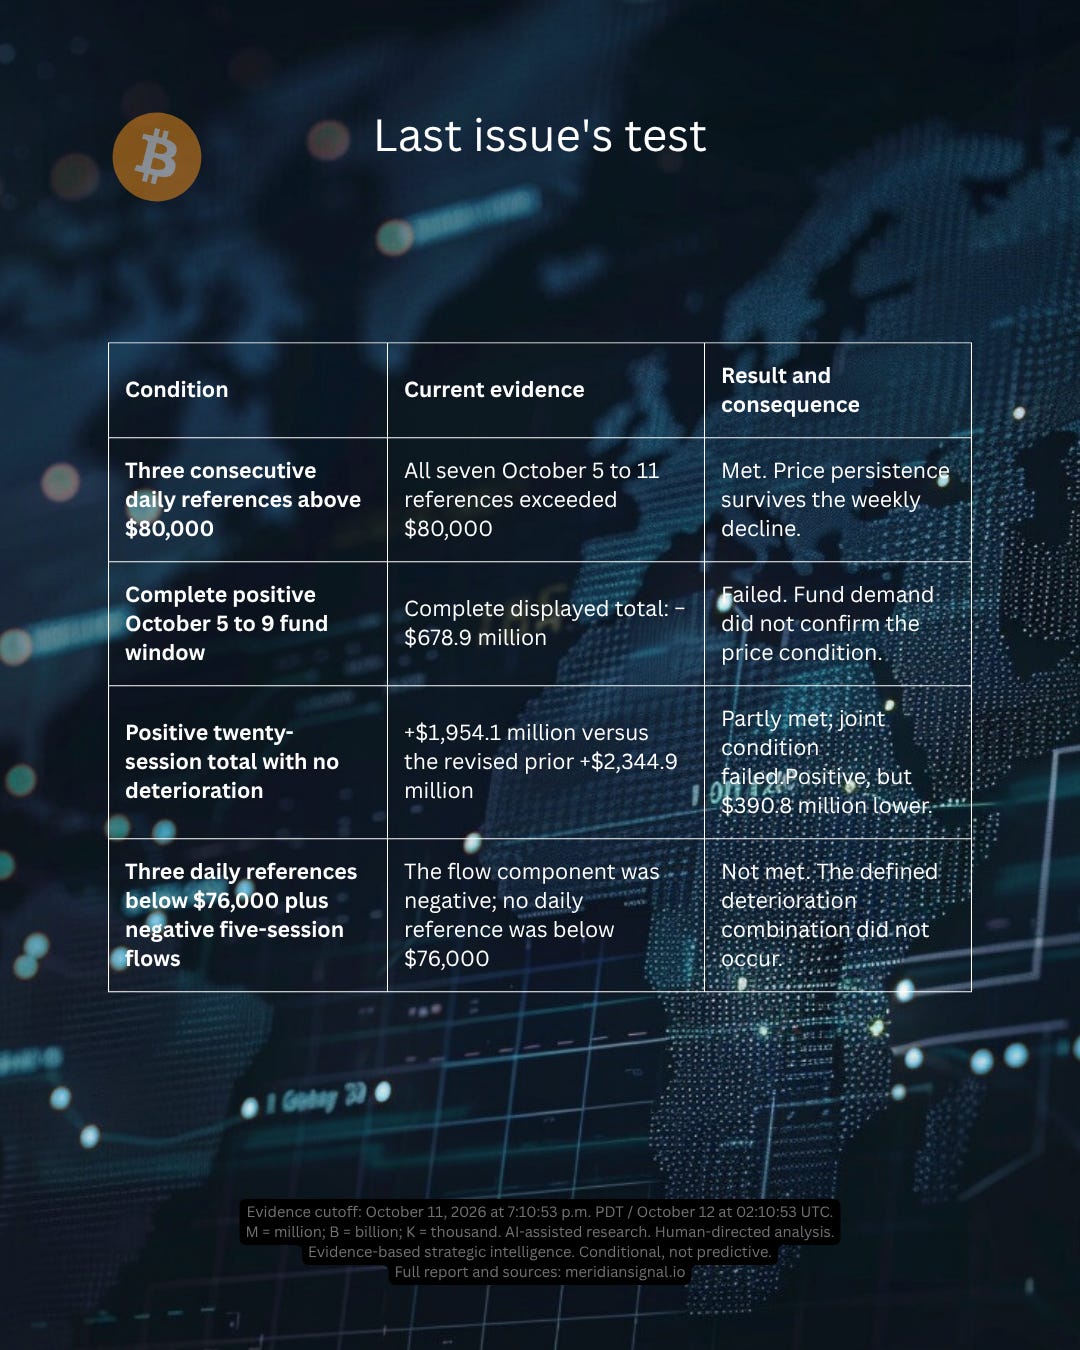
The full continuation test was not met, although the price component passed. The evidence fits the previously defined uneven-recovery path. Failing continuation does not automatically satisfy the separate deterioration case. Both reference levels and the three-day duration remain unchanged; they are intermediate research triggers, not established support, resistance or proof of a market regime.
The missing entry is now resolved
Data revision identified October 11, 2026: Farside now displays +$158.2 million for October 2 IBIT, the iShares Bitcoin Trust. That completes October 2 at +$189.9 million. The September 28 to October 2 five-session total is now +$241.1 million, versus the +$82.9 million provisional figure preserved in WCIR 029. Its September 4 to October 2 twenty-session total is now +$2,344.9 million, versus the published provisional +$2,186.7 million. [2]
This edition compares completed windows from the current capture. The revision supplies information that was unavailable at the earlier cutoff; it does not turn WCIR 029’s originally unresolved test into a contemporaneous pass. The original article and its limitation remain part of the record. The fresh comparison also shows why simply carrying forward last week’s provisional denominator would distort the change.
Price structure and institutional demand
The standard seven-day price change compares October 4 with October 11 in one newly captured Coin Metrics PriceUSD series. The separate Monday-to-Sunday change, October 5 to 11, was −2.56%. These windows answer different questions. The daily observation convention also matters: an intraday move through a reference level would not satisfy a test defined using completed UTC daily observations. [1]
The five fund sessions were −$89.8 million, +$118.8 million, −$484.9 million, −$244.1 million and +$21.1 million. October 6 was the strongest session; October 7 was the weakest. Friday’s small positive reading did not reverse the week’s net withdrawal. The observed series covers U.S. spot Bitcoin funds, not every institutional buyer or every Bitcoin transaction. [2]
Issuer participation makes the aggregate more informative. Fidelity’s FBTC contributed −$380.3 million and ARKB contributed −$207.2 million across the week. IBIT was almost flat at +$1.1 million. A large issuer avoiding a net withdrawal is different from broad fresh demand. Equally, this table cannot identify all final beneficial owners or explain the intent behind each subscription or redemption. [2]
The twenty-session total covers September 14 to October 9. Its +$1,954.1 million remains a meaningful counterweight to the weak week, but it is lower than the completed September 4 to October 2 total. The windows overlap by fifteen sessions, so they are not independent confirmations. Their $390.8 million difference reflects the five sessions entering the calculation versus the five leaving it, not the full −$678.9 million current-week total in isolation.
Meridian’s inference is that demand support has become less convincing even while price persistence remains visible. These observations do not establish that fund redemptions caused the price decline. Trading outside the funds, derivatives, supply decisions and other influences are not comprehensively measured here. The supported conclusion concerns weaker demand in this channel, not a claim that all institutional demand disappeared.
Macro and liquidity
The Federal Reserve’s October 9 H.15 release places the five-year inflation-indexed Treasury yield at 2.62% on October 8. That is three basis points below the October 1 observation used in WCIR 029, at 2.65%. Within the current release, the move from October 2’s 2.69% to October 8 was seven basis points lower. The first is an issue-to-issue observation comparison; the second is a Friday-to-Thursday comparison, not a completed Friday-to-Friday week. [5]
The decline modestly eases that particular real-yield measure. It does not establish broadly easier financial conditions, and 2.62% still represents a positive real yield on that Treasury benchmark. Bitcoin has no contractual cash flow, so the competing return available in other assets remains relevant without supplying a mechanical price forecast.
In the October 8 H.4.1 release, weekly average reserve balances were $3,029.659 billion for the week ended October 7, up $81.569 billion. The Treasury General Account averaged $880.253 billion, down $68.421 billion. These are averages of daily figures. The Wednesday levels in the same release are different observations and are not substituted into the weekly comparisons. [6]
Higher bank reserves and a smaller Treasury cash balance can make the selected dollar-liquidity context less restrictive. They do not measure money allocated to Bitcoin, and the two changes need not match dollar for dollar because other balance-sheet factors also move. The weak fund week therefore coexists with some more supportive liquidity observations. That coexistence argues against explaining the market through one liquidity statistic.
Circle’s transparency page was dated October 8 for its reserve composition, but the retrieved material did not establish a comparable whole-market stablecoin supply series. Issuer reserve composition is not total stablecoin growth, and stablecoin balances are not automatically committed Bitcoin buying power. This report makes no aggregate expansion claim. That gap limits the breadth of the liquidity assessment rather than implying zero growth. [7]
Corporate ownership and financing
Strategy’s October 5 Form 8-K reported 334 bitcoin acquired for $28.7 million during October 1 to 4, bringing reported holdings to 848,000 bitcoin at October 4. The disclosed average acquisition price for that purchase period was $85,838.8, including fees and expenses. This is a disclosure during the current reporting week about the preceding period, not evidence of purchases during October 5 to 11. The SEC filing inventory reviewed at cutoff did not show a later acquisition 8-K. [8]
The funding split matters. Strategy reported $15.7 million of Bitcoin purchases funded by common-share net proceeds and $13.0 million from its USD Cash. During October 1 to 4 it also repurchased 740,634 STRC preferred shares for $73.7 million using USD Cash. Those are different uses of capital. A company’s financing capacity cannot all be counted as incremental Bitcoin demand. [8]
For the full September 28 to October 4 period, the filing reports $154.1 million of USD Cash used for STRC repurchases and $142.5 million of its separate USD Reserve used for preferred dividends and debt interest. At October 4, those balances were $833.4 million and $4.88 billion respectively. The reserve is intended to support financial obligations; it should not be treated as an unrestricted future Bitcoin purchase commitment. The filing’s financial estimates were prepared by management and had not been audited or reviewed by its independent accounting firm. [8]
An October 9 proxy communication keeps the proposed daily dividend record dates conditional on shareholder approval and effective amended certificates. It also clarifies that declared dividends would be payable on the next business day after the relevant record date. A proposed change to payment mechanics is not completed adoption, added annual income or proof of lower financing risk. [9]
These disclosures support the existence of an active corporate ownership and financing structure. They also show why ownership size, liquidity, obligations and market demand must remain separate. One company’s balance sheet cannot establish holder intent across Bitcoin, and large holdings do not create a guaranteed market floor.
Network operation and miner economics
Mempool’s seven completed daily intervals for October 5 to 11 average 1,021.55 EH/s, up 6.26% from the same-mapping prior mean of 961.36 EH/s. The endpoint timestamp marks the interval’s end and is mapped to the preceding completed UTC date. Each comparison uses seven intervals from the same capture. Difficulty remained 132.716 trillion, rounded to 132.72T, after the October 3 adjustment of −0.0309%. [4]
Estimated hashrate is inferred from block production and difficulty. It is not a census of machines, operators or jurisdictions. A higher estimate describes network computation under this convention; it does not demonstrate decentralization, profitability, durable-holder intent or protection against falling prices. The estimate may vary with block timing and provider methodology.
Hashrate Index displayed $39.80 per petahash per day when retrieved at October 12, 02:07:13 UTC. This is an indicative revenue measure, not profit. The page did not expose a separate measurement timestamp for that quote, so it is treated as a retrieval-time snapshot rather than a weekly average or a like-for-like weekly return. Power, equipment efficiency, fees, financing and other operating costs determine what miners retain. Stronger estimated hashrate can coexist with pressure on individual miners. [10]
Custody, protocol and sentiment
Bitcoin Core’s release index lists version 31.1. Its official release notes describe fixes for excessive chainstate disk activity and an address leak involving the private-broadcast feature. Availability of a fix is different from operators installing it, and neither establishes that every custody provider has equivalent controls. The security-advisory index remains a source of scoped software disclosures, not a comprehensive incident census. [11]
This edition does not establish complete coverage of custodians or custody incidents. It therefore makes no claim of unchanged custody risk or an incident-free week. Protocol operation, customer withdrawal access, key management and intermediary solvency are separate questions. A specific verified disruption would require analysis of affected users, assets, duration and recovery before changing a broader assessment. The coverage limitation restricts broad custody conclusions without invalidating the independently observed price and fund data.
Alternative.me’s Fear & Greed reading was 69, Greed, timestamped October 12 at 00:00 UTC, compared with 70 at the prior issue’s October 5 observation. Both preceded their respective Sunday Pacific cutoffs. The index partly incorporates market inputs and should not be counted as wholly independent confirmation. A Greed label can coexist with a negative fund week; it does not demonstrate actual new buying. [3]
Changes, continuities and the strongest contrary case
The material change is weaker complete fund evidence. Price persistence, the positive longer fund window and the retained reference levels continue. Estimated hashrate increased; difficulty has not adjusted again. Selected reserve and real-yield observations became more supportive, but they did not translate into a positive fund week in the observed channel.
The strongest contrary case to a constructive long-term posture is that visible price resilience is concealing fragile demand and financing dependencies. Further complete outflow windows, weakening corporate liquidity or verified operational impairment would add weight to that case. This week already weakens the medium-term demand reading; the tactical assessment should reflect that before the separate $76,000 deterioration combination occurs.
There is also evidence against declaring a broad breakdown: every completed daily reference remained above $80,000, the twenty-session total stayed positive, and the specified price-and-flow deterioration test was not met. A disciplined assessment holds both sides. Neither one weak week nor one recovered price level can settle the longer thesis.
Conditional paths and Horizon Posture
Constructive continuation: retain three consecutive completed Coin Metrics UTC daily references above $80,000, plus a complete positive next five-session fund window and a positive twenty-session total no lower than this edition’s completed comparable total. The next standard five-session window is October 12 to 16, subject to actual trading sessions and complete issuer reporting. A genuine closure is not a missing observation or a zero-flow session. Any revision to the comparison base will be disclosed before reassessment.
Uneven recovery: price persistence continues while fund evidence is mixed or weaker. This is the current closest fit. It can persist without either full continuation confirmation or the defined deterioration combination. A partial condition will be labeled partial, not promoted into a regime conclusion.
Deterioration: retain three consecutive completed daily references below $76,000 together with a complete negative five-session fund window. An isolated intraday break does not qualify. Missing issuer data keep a dependent test unresolved. No probabilities are assigned to these conditional paths.
Long term: Constructive and thesis-led. Credible, persistent protocol or custody impairment, or financing fragility that undermines the ownership thesis, would weaken this view. Evidence of reliable use and resilient financing would support it; price alone cannot verify either.
Medium term: Conditional, with weaker demand. Complete recurring inflows, broader issuer participation and stabilization of the twenty-session total would strengthen it. Another complete negative window or sustained financing stress would weaken it further. Participation is described from observable flows, not a proprietary breadth score.
Tactical: Cautious, with price persistence intact. The shift from last issue’s constructive-with-caution posture follows failed demand confirmation on complete data. Joint price-and-flow confirmation would strengthen it. The retained deterioration combination would warrant a more adverse reading. These conditions guide interpretation rather than portfolio instructions.
Meridian strategic conclusion
Bitcoin’s recovery is still visible in the retained price test, but its fund-demand support has weakened. This week resolves an uncertainty in an unfavorable direction: the current five-session window is complete and negative. The revised prior data improve the historical record without repairing this week’s failed confirmation.
The next useful evidence is whether inflows resume across a complete window while daily price persistence holds. Until then, the appropriate posture is more cautious tactically and conditional over the medium term. Network operation and selected liquidity readings provide context, but neither can substitute for the demand evidence the recovery still needs.
Sources and observation conventions
Coin Metrics PriceUSD methodology and Community API capture. BTC in USD; daily UTC day-end reference under provider date labels, preserved as returned. 649 consecutive observations, no splice. Revisions are possible.
Farside U.S. Bitcoin fund flows. USD millions. Current five-session window October 5 to 9; twenty-session window September 14 to October 9. Completed prior windows are recalculated from the same current capture. Displayed daily totals may differ slightly from sums of rounded issuer entries.
Alternative.me index API. October 12, 00:00 UTC observation; partly market-derived.
Mempool mining data. Interval ends mapped to preceding completed UTC days; difficulty block 969,696, October 3 at 07:16:36 UTC.
Federal Reserve H.15, October 9 release, observations through October 8. Prior October 1 observation is retained from WCIR 029’s dated source record.
Federal Reserve H.4.1, October 8 release, weekly averages for week ended October 7. Original source units: USD millions.
Circle transparency, issuer-specific reserve context dated October 8; no whole-market stablecoin comparison asserted.
Strategy October 5 Form 8-K and SEC filing inventory. Company-reported transactions and balances through October 4; filing date is not transaction date.
Strategy October 9 proxy communication. Conditional proposals and company clarifications, not implemented changes.
Hashrate Index, retrieval-time revenue snapshot; no separately visible measurement timestamp.
Bitcoin Core 31.1 release notes, release index and security advisories. Software disclosures do not establish adoption or comprehensive custody-incident coverage.
The accompanying source map records individual retrieval times, windows and limitations. Arithmetic is descriptive and reproducible in the workbook. Observations, calculations and qualitative judgments are kept distinct. No proprietary score, probability, price target or transaction instruction is assigned.
Editorial Note
The Bitcoin Evidence-Led Series distinguishes sourced observations, descriptive calculations and Meridian’s qualitative assessments. Each edition reflects the evidence available at its stated cutoff; source data may subsequently be revised.
Meridian Signal uses artificial intelligence to assist source discovery, comparison, drafting and arithmetic verification. Final review and editorial responsibility rest with Meridian Signal. Material limitations are disclosed, and corrections to prior reporting are identified explicitly.
Research Disclosure
This report provides general informational and educational research, not personalized investment, legal or tax advice or an instruction to transact. Bitcoin is volatile, and loss of principal is possible. Assessments involve uncertainty; conditions and scenarios do not guarantee outcomes.
Meridian Signal
Bold clarity at the right time.
Independent strategic intelligence on capital regimes, digital infrastructure and systemic risk.
AI-assisted. Human-directed.
Evidence-based strategic intelligence. Conditional, not predictive.
Questions or corrections: contact@meridiansignal.io