
Seven days above $80,000 meet the price test, while a missing fund entry leaves the broader demand test unresolved.
Reporting week: September 28 to October 4, 2026. Evidence cutoff: October 4, 2026 at 7:17:27 p.m. PDT / October 5, 2026 at 02:17:27 UTC.
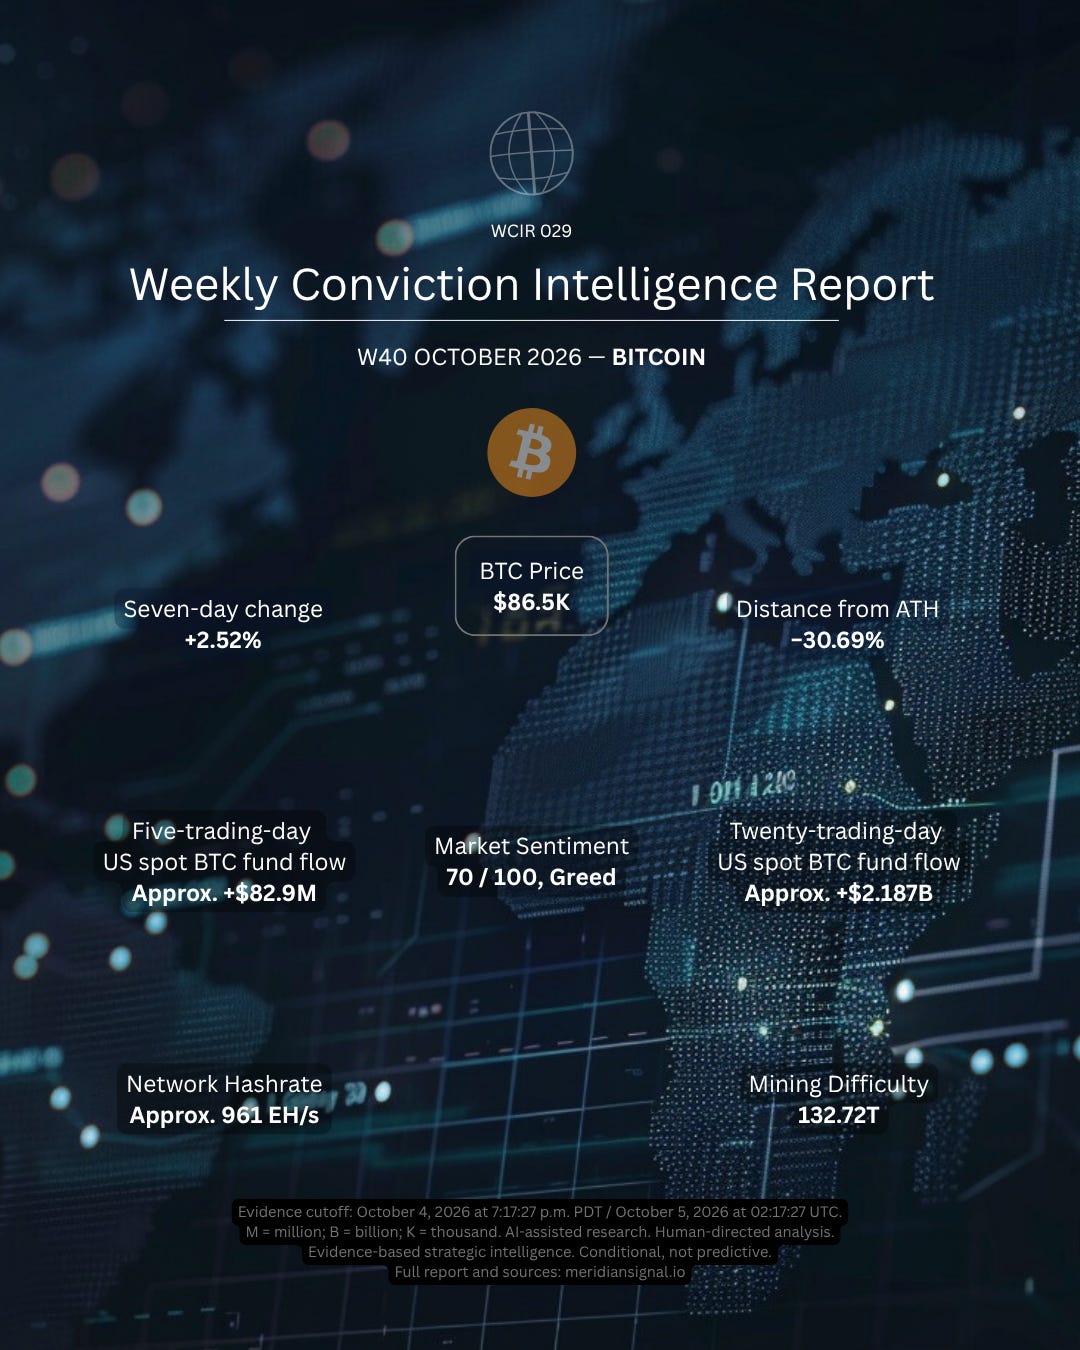
Bitcoin’s recovery has lasted long enough to meet last week’s price condition. The broader demand condition has not earned the same conclusion. Coin Metrics’ October 4 daily reference was $86,520.80, up 2.52% from September 27, and every completed daily reference during the reporting week remained above $80,000. That is observable persistence, rather than a brief intraday crossing. [1]
Fund evidence is less conclusive. The displayed five-session total is +$82.9 million, provisional, with one missing issuer entry. We cannot turn that unfinished total into a confirmed positive week. Meridian’s overall assessment is constructive, with incomplete demand confirmation. The recovery remains intact on the chosen price convention; its demand support still needs a complete reading. [2]
Executive snapshot
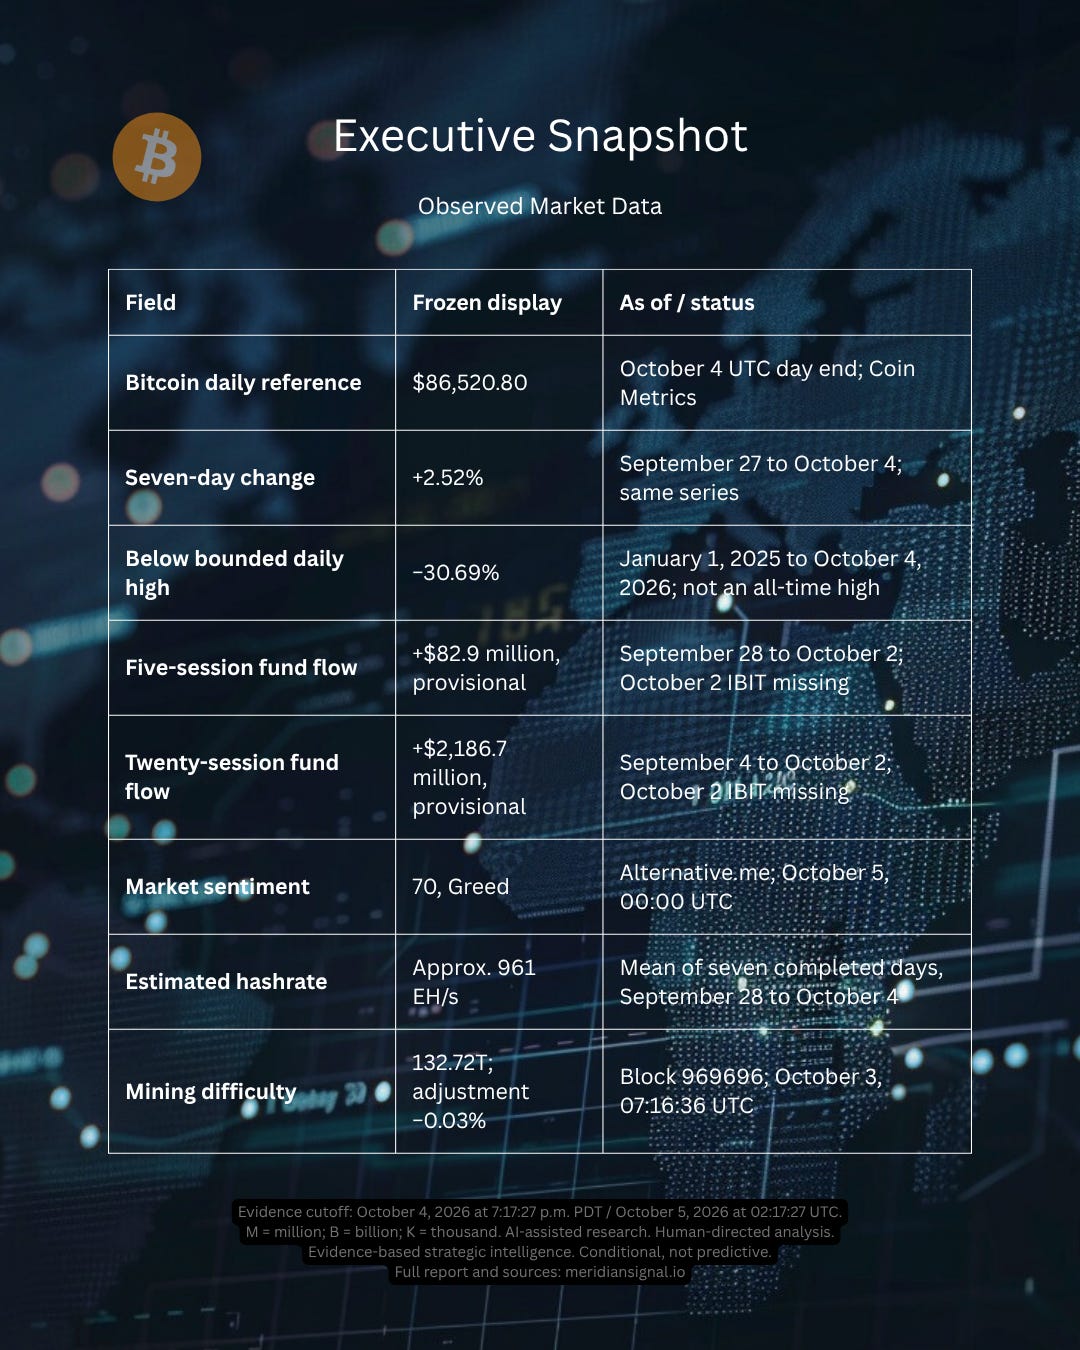
The price maximum used here is bounded: $124,824.45 on October 6, 2025, within the January 1, 2025 to October 4, 2026 sample. It is neither an intraday high nor a claim about Bitcoin’s entire history. Fund totals come from displayed daily totals and remain provisional. Difficulty is dimensionless; T abbreviates trillion. EH/s means exahashes per second. [1–4]
Last issue’s test
WCIR 028, published September 28, required at least three consecutive completed daily references above $80,000, a positive next five-session fund window, and a positive twenty-session total without renewed deterioration between issues. These were joint conditions, not interchangeable confirmations.
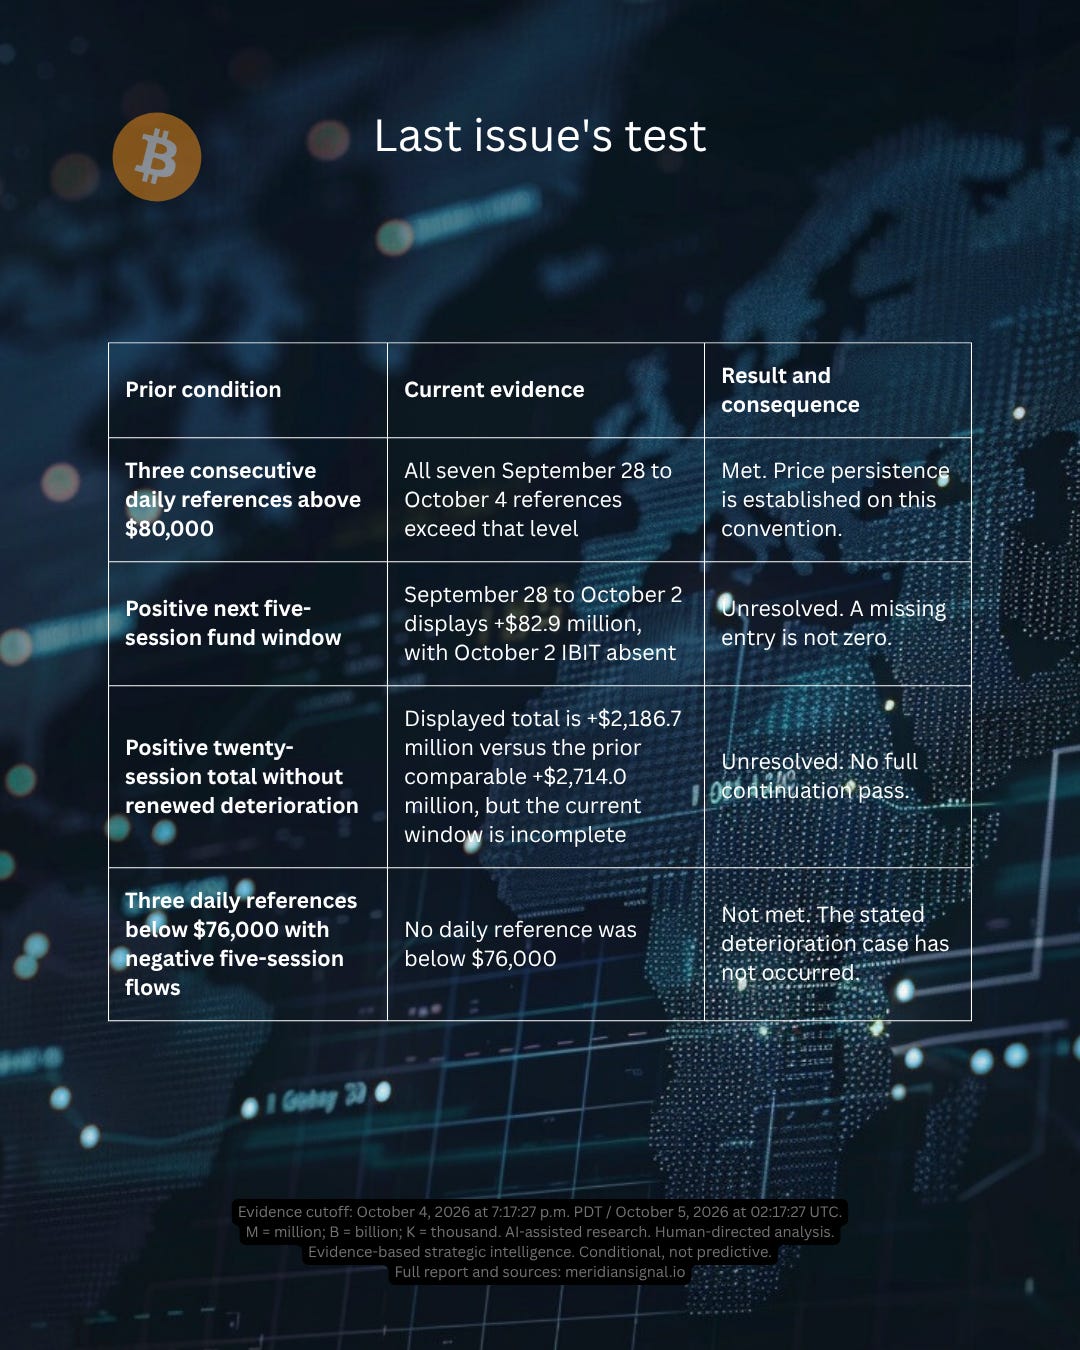
The combined continuation test is partly met. We retain both reference levels and their three-day duration. Raising them merely because price advanced would quietly change the test. They are intermediate assessment triggers, not proven support, resistance, or a declaration of a new market regime.
Price structure and demand quality
The seven-day comparison uses September 27 and October 4 from one freshly retrieved Coin Metrics series. It is distinct from the 3.60% change between Monday’s September 28 reference and Sunday’s October 4 reference. The former is our standard seven-day measure; the latter describes movement within the named calendar week. No second exchange series is joined to this history. [1]
Farside’s four complete sessions through October 1 sum to +$51.2 million. October 1 contributed +$102.7 million, including +$195.6 million from the iShares Bitcoin Trust, whose ticker is IBIT. Other issuers offset part of that contribution. Fidelity’s FBTC entries total −$167.9 million across the five dates. October 2 IBIT remains missing. The twenty-session window covers September 4 to October 2 and overlaps the prior window by fifteen sessions. [2]
Meridian’s inference is narrower than a claim of demand collapse: the known sessions show uneven participation, while the unfinished week prevents a definitive aggregate comparison. A rising price can coexist with selective fund buying, trading outside these funds, or changing willingness to sell. This dataset does not identify which mechanism dominated. The next useful evidence is a complete fund window and repeated participation, not a stronger adjective for the price chart.
Macro and liquidity
The Federal Reserve’s October 2 H.15 release gives a five-year inflation-indexed Treasury yield of 2.65% for October 1, compared with 2.64% on September 25. That is a one-basis-point increase within the same release. It should not be described as unambiguous weekly easing. WCIR 028 used an earlier observation date; changing the starting date changes the comparison. [5]
In the October 1 H.4.1 release, weekly average reserve balances were $2.948 trillion for the week ended September 30, up $17.897 billion from the previous weekly average. The Treasury General Account averaged $948.674 billion, down $28.410 billion. These are weekly averages, not Wednesday closing balances. [6]
Those movements describe different parts of dollar funding conditions. Reserve balances increasing alongside a lower Treasury balance can be relevant to available banking-system liquidity, but they do not measure money committed to Bitcoin. Real yields also remain a competing influence on the relative appeal of assets without contractual cash flows. Our assessment therefore stays conditional: these releases offer context, not a single mechanical explanation of the weekly price gain.
A comparable current aggregate for stablecoin supply was not established from the primary material reviewed. Circle’s transparency page supplies issuer-specific reserve context; it cannot stand in for the entire market. We make no aggregate stablecoin expansion claim. The missing comparison limits the breadth of our liquidity conclusion rather than changing an absent observation into “no change.” [7]
Corporate ownership and financing
Strategy disclosed on September 28 that it acquired 1,665 bitcoin for $142.7 million during September 21 to 27, reporting 847,666 bitcoin held as of September 27. This is a new disclosure during our reporting week about transactions in the preceding week. It is not evidence of an additional October purchase. [8]
The same filing links common-share issuance proceeds to Bitcoin purchases and preferred-share repurchases. Its allocation matters: financing raised by a treasury company is not automatically all spot Bitcoin demand. The October 1 filing maintained a 12% annual dividend rate for its STRC preferred instrument for the stated forthcoming period and described a proposed change involving daily dividend record dates. The change depended on shareholder approval and an effective certificate amendment; an announced proposal is not implementation. [8,9]
Meridian treats these disclosures as evidence of an active financing structure, with continuing obligations and conditions. They do not prove durable-holder intent across the market, remove refinancing risk, or show that other corporate owners behaved similarly. The useful follow-through is whether subsequent filings confirm completed purchases, cash uses and the effectiveness of proposed terms. We do not infer those outcomes from the announcement alone.
Network operation and miner economics
Mempool.space supplied all seven completed daily hashrate intervals for September 28 to October 4. Their mean is 961.36 EH/s, displayed as approximately 961 EH/s. Interval-end timestamps are mapped to the preceding completed UTC date. Coin Metrics and Blockchain.com supplied dated backup estimates; they were reviewed as checks, not silently substituted into the primary average. [4,10,11]
Difficulty stood at 132.72 trillion after the October 3 adjustment, a reduction of 0.03%. Hashrate estimates describe computational work inferred from block production and difficulty. They do not identify miner profit, ownership dispersion, or a price floor. Differences between providers can reflect estimation and timing conventions even when the broad magnitude is similar. [4,10]
Hashrate Index displayed $41.08 per petahash per day at retrieval, without a visible measurement timestamp for that quote. We treat it as indicative revenue context, not a dated weekly average or a verified week-over-week change. Revenue per unit of computing power is not operating profit: power costs, machine efficiency, financing and fees affect what a miner retains. This separation prevents healthy network operation from becoming an unsupported claim that miners face no financial pressure. [12]
Custody, protocol and positioning
Bitcoin Core’s official release material and security-advisory index were reviewed. Version 31.1 is carried forward as software context; the reviewed advisory on a vulnerability fixed in version 29.0 is an older disclosure, not a newly observed incident this week. Software release, operator adoption and demonstrated network effects are separate events. The materials do not establish universal upgrading. [13]
This review did not establish comprehensive coverage of all custodians or custody incidents. We therefore make no claim that custody risk was unchanged or that no incident occurred. Holding through an intermediary introduces operational and counterparty considerations distinct from the functioning of Bitcoin’s protocol. Evidence of a specific incident would require its own dated assessment of scope, affected assets and remediation, rather than a market-wide conclusion from an incomplete review.
Alternative.me’s index was 70, Greed, timestamped October 5 at 00:00 UTC, which was still Sunday in Pacific time and preceded this cutoff. Sentiment incorporates market inputs and is not wholly independent confirmation of price strength. Deribit’s Bitcoin perpetual contract showed approximately $800.0 million in open interest at 02:10:43 UTC. This is a single venue and instrument snapshot, not total market leverage or a directional position. Neither observation establishes why the weekly price change occurred. [3,14]
Changes, continuities and the strongest contrary case
Price persistence strengthened relative to last issue’s explicit test. Fund confirmation became less secure because the current displayed totals are incomplete and the known sessions were uneven. The distinction is analytical: price can pass its condition while demand remains unresolved. We should neither discard the price evidence nor award the joint test prematurely.
The strongest contrary case is that the recovery is running ahead of durable, broad demand. Corporate financing remains conditional, real yields are not uniformly easing, and a sentiment reading in Greed does not remove reversal risk. A complete fund series could alter the demand assessment in either direction. Conversely, several further completed daily references above $80,000 alongside complete, persistent inflows would weaken that contrary case.
Our continuity review uses the immediately prior published issue and preserves its exact conditions. It does not claim that the subsequent price move validates a forecast, calibrates a probability, or demonstrates foresight across Meridian’s archive.
Conditional paths and horizon posture
The constructive path retains three consecutive completed Coin Metrics UTC daily references above $80,000. It also requires a complete positive next five-session fund window and a positive twenty-session total that is not lower than the immediately preceding comparable issue’s completed total. If a component remains incomplete, the joint outcome remains unresolved. A later revision must be identified before comparing it with the frozen result.
The uneven-recovery path is price persistence with mixed, weaker or incomplete fund evidence. That is the closest description of this snapshot. The next standard five-session comparison is October 5 to 9, subject to complete issuer reporting. It must not be replaced opportunistically by a more favorable selection of days.
The deterioration path retains three consecutive completed daily references below $76,000 together with a complete negative five-session fund window. An isolated intraday break does not meet that definition. These are conditional research tests; they provide neither odds nor transaction instructions.
Long term: Constructive and thesis-led. This posture would weaken with credible evidence of persistent protocol or custody failures that impair use, or financing fragility that undermines the ownership thesis. One week’s price strength cannot resolve those longer-horizon questions.
Medium term: Conditional, with demand persistence unproven. Complete recurring inflows and broader participation would strengthen it. Complete negative fund windows or sustained financing stress would weaken it, even if price temporarily remained above the intermediate trigger.
Tactical: Constructive, with caution. Continued daily persistence and complete demand confirmation would strengthen this reading. The defined price-and-flow deterioration combination would change it. Missing data alone warrant less confidence, not a fabricated bearish observation.
Conclusion
Bitcoin has supplied the price persistence that last issue asked readers to watch. That is progress, but it is not the whole test. The useful next step is to see whether complete demand evidence supports the recovery rather than treating a provisional positive total as settled confirmation.
Our stance preserves both sides of the record: seven completed days above the unchanged reference level, and an unfinished demand picture with uneven known participation. The horizons remain deliberately distinct. Network activity informs operation; financing disclosures inform obligations; prices and flows inform market behavior. None should stand in for the others. A stronger conclusion will require stronger, complete evidence.
Principal sources
Coin Metrics PriceUSD methodology, Community API daily snapshot through October 4.
Farside U.S. Bitcoin fund flows, displayed sessions through October 2.
Alternative.me index API, October 5 UTC observation.
Mempool.space mining data, daily intervals and difficulty history.
Federal Reserve H.15, October 2 release.
Federal Reserve H.4.1, October 1 release.
Circle transparency, issuer-specific context.
Strategy September 28 disclosure, with Form 8-K.
Strategy filings, October 1 Form 8-K.
Blockchain.com hashrate, backup historical estimate.
Hashrate Index, indicative quote at retrieval.
Deribit contract-summary documentation, live perpetual snapshot.
Editorial Note
The Bitcoin Evidence-Led Series distinguishes sourced observations, descriptive calculations and Meridian’s qualitative assessments. Each edition reflects the evidence available at its stated cutoff; source data may subsequently be revised.
Meridian Signal uses artificial intelligence to assist source discovery, comparison, drafting and arithmetic verification. Final review and editorial responsibility rest with Meridian Signal. Material limitations are disclosed, and corrections to prior reporting are identified explicitly.
Research Disclosure
This report provides general informational and educational research, not personalized investment, legal or tax advice or an instruction to transact. Bitcoin is volatile, and loss of principal is possible. Assessments involve uncertainty; conditions and scenarios do not guarantee outcomes.
Meridian Signal
Bold clarity at the right time.
Independent strategic intelligence on capital regimes, digital infrastructure and systemic risk.
AI-assisted. Human-directed.
Evidence-based strategic intelligence. Conditional, not predictive.
Questions or corrections: contact@meridiansignal.io