
Weekly Conviction Intelligence Report | Evidence-Led Series
Reporting week: September 21 through 27, 2026. Evidence cutoff: Sunday, September 27 at 7:13:22 p.m. Pacific daylight time / Monday, September 28 at 02:13:22 UTC. UTC means Coordinated Universal Time. Daily observations and release dates below differ from this collection cutoff.
Executive assessment
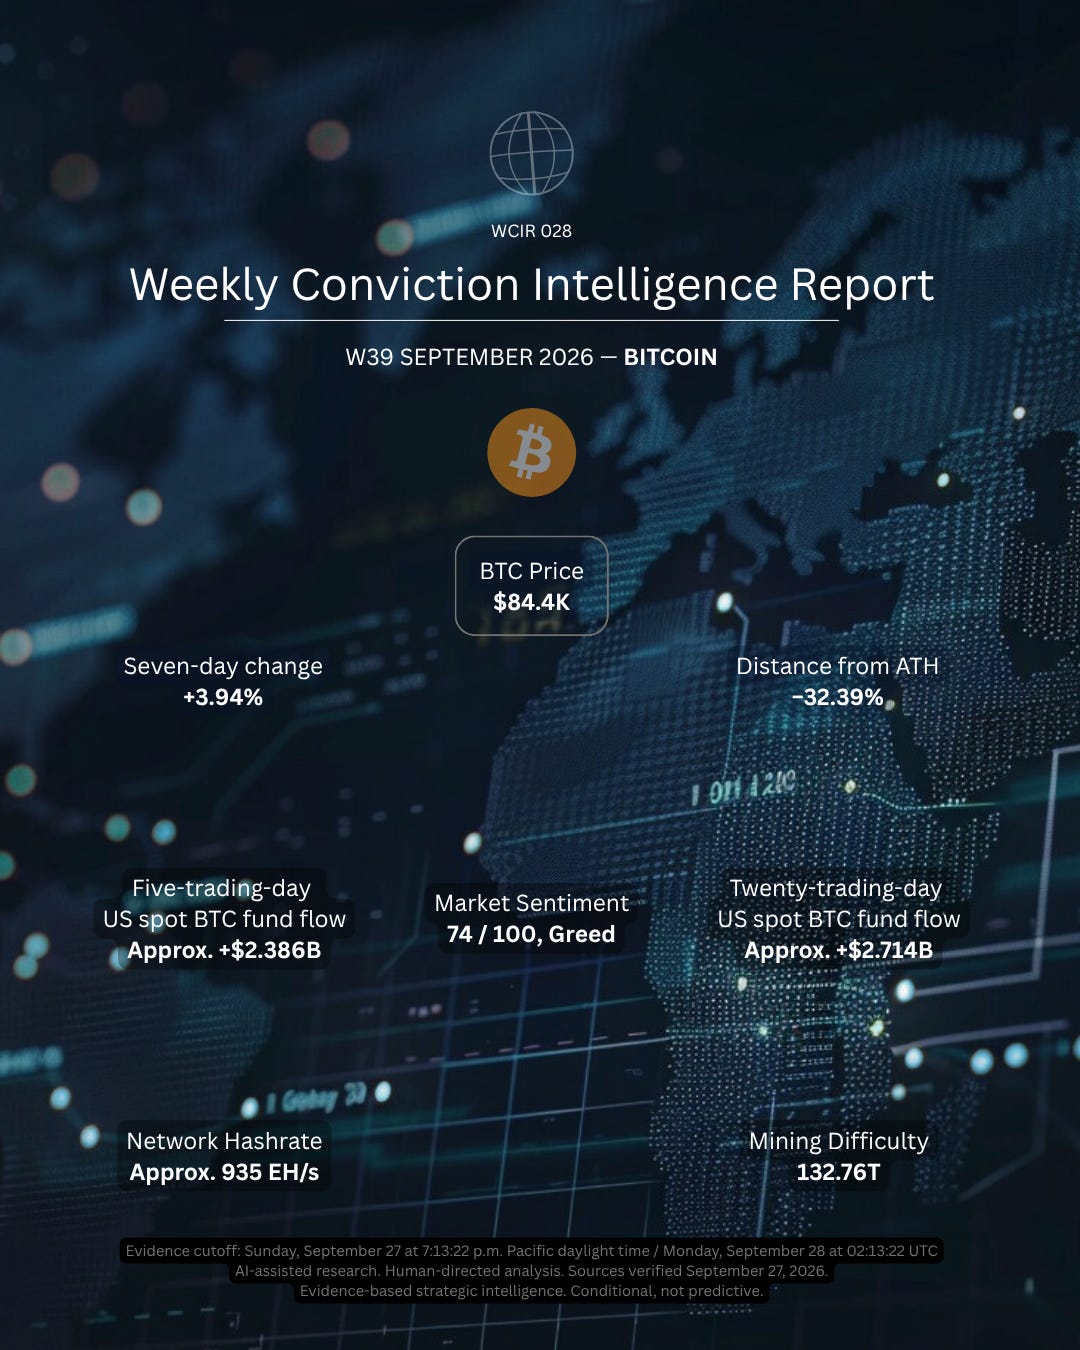
Bitcoin retained the $80,000 reference from the previous issue, and fund demand supplied the corroboration that had been missing. Coin Metrics’ September 27 daily reference was $84,392.47, up 3.94% from September 20 in the same retrieved series. U.S. spot Bitcoin funds recorded approximately +$2,385.8 million over September 21 through 25, with all five sessions positive. The twenty-session balance also increased. Coin Metrics, Farside.
Meridian’s assessment improves to constructive, with stronger confirmation. That judgment concerns the observed recovery. A durable market regime requires more than one stronger week. Inflows were front-loaded, the daily price reference finished below Monday’s level, and real yields rose in the latest Federal Reserve release. Those qualifications matter when judging what the headline improvement can sustain.
Executive Snapshot
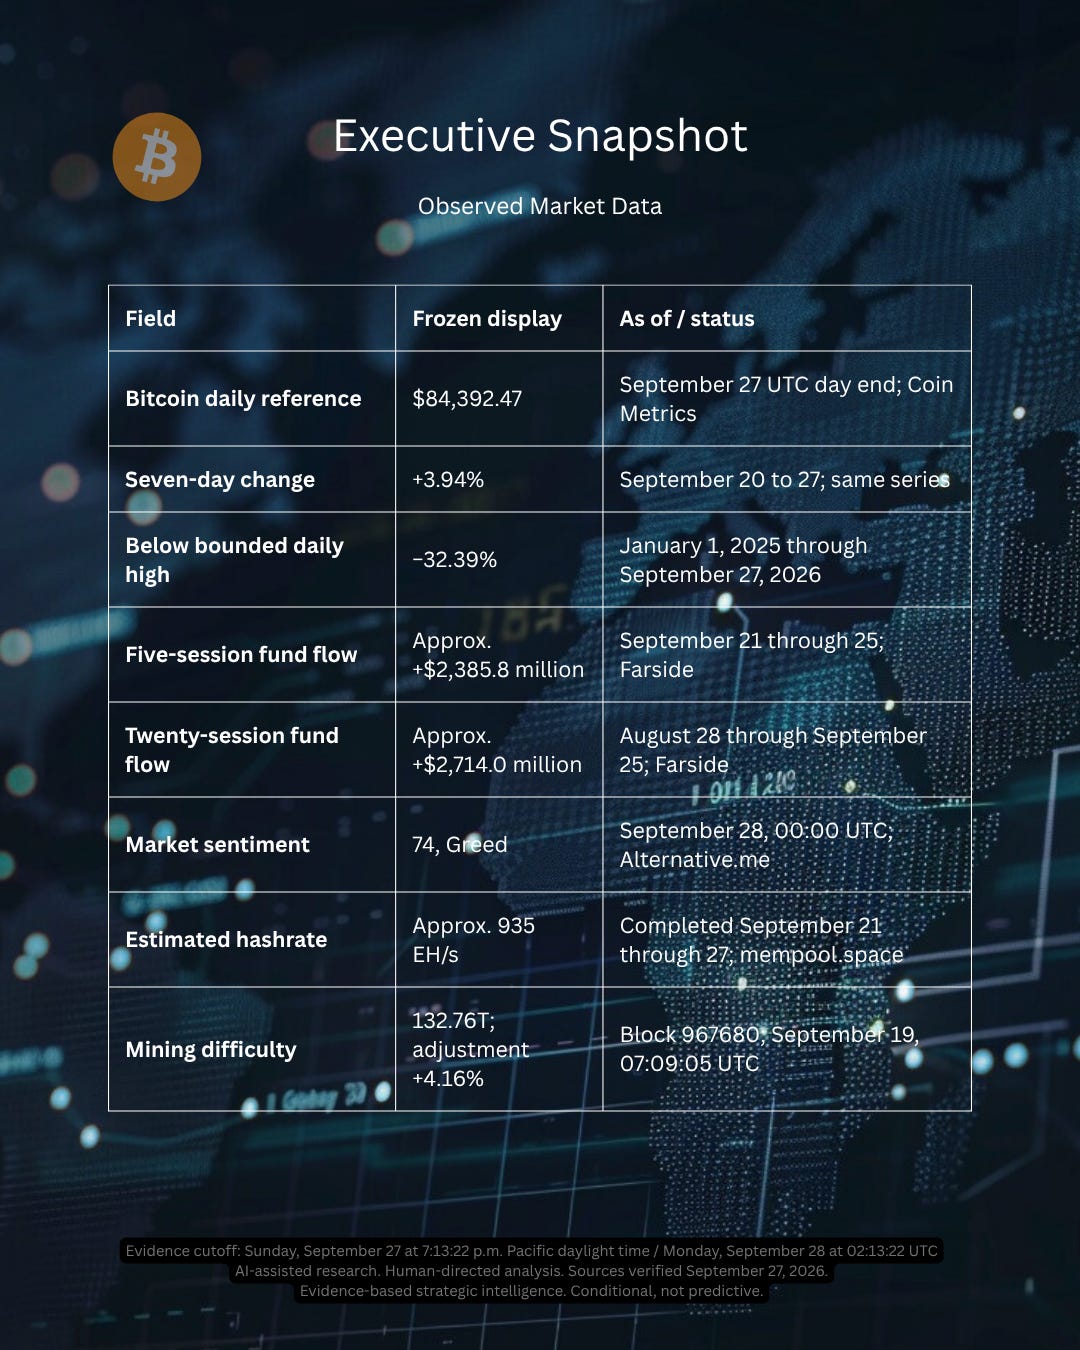
EH/s means exahashes per second. T means trillion. The bounded high is the largest daily reference in 635 observations, $124,824.45 on October 6, 2025. It is neither an intraday high nor a claim about Bitcoin’s entire price history. Full precision and observation conventions accompany the workbook. Sentiment, network data.
Last issue’s test
WCIR 027, published September 21, asked whether the recovered $80,000 area would hold while positive demand repeated and the wider fund balance stabilized. It specified at least three consecutive completed UTC daily references in Coin Metrics for retaining the price area. Its deterioration case combined repeated references below $76,000 with another negative five-session fund window.
Constructive intermediate test: met for this review. All seven September 21 through 27 daily references exceeded $80,000. The final three were $84,062.16, $84,386.50 and $84,392.47. Five positive fund sessions followed the previous near-flat week, while the wider balance rose from approximately $1,762.1 million to $2,714.0 million. This satisfies the stated duration and corroboration for the intermediate test. Persistence across several future weeks remains unresolved.
Combined deterioration test: not met. The specified price sequence and negative fund window did not occur. Both $80,000 and $76,000 remain unchanged reference levels. We are not replacing them with new levels merely because price advanced. Neither reference is guaranteed support or a transaction instruction.
What changed, and what continued
The meaningful change is alignment: retained daily price strength now accompanies repeated fund inflows and an improving wider balance. The September 20 reference in this vintage matches the prior report’s underlying Coin Metrics value, so the seven-day comparison needs no price-source splice.
Some continuity is less supportive. Estimated hashrate rounds to the same 935 EH/s as the prior week, and difficulty remains at the September 19 adjustment. Sentiment rose from the previous issue’s 70 to 74 but retained its Greed classification. Because sentiment incorporates market inputs, it is not another fully independent confirmation of price strength. The macro backdrop remains demanding, and beneficial-owner behavior remains incompletely observed.
Institutional demand: stronger, with concentration
Farside’s five displayed daily totals were +$999.0 million, +$714.7 million, +$346.9 million, +$190.7 million and +$134.5 million. Monday represented 41.87% of the five-session total, and the first two sessions represented 71.83%. BlackRock’s iShares Bitcoin Trust, identified as IBIT in the source, contributed $1,157.6 million, or 48.52%. This is materially stronger participation than last week’s late rescue, but the inflow pace diminished through Friday.
The five-session window is also this calendar week’s complete U.S. fund trading week. It shares no sessions with September 14 through 18, whose same-vintage total is +$6.1 million. The two twenty-session windows share fifteen observations. Their +$951.9 million difference reflects five new sessions entering and five older sessions leaving, not an additional pool of money to add to this week’s inflows. Displayed issuer rows reconcile to displayed totals; provider rounding and later revisions remain possible. Farside source table.
Meridian infers firmer sponsorship, not proof of who ultimately owns the coins or why they bought. Fund subscriptions are one demand channel. They cannot establish that funds caused the entire price move, identify unreported sellers, or certify durable holding intentions.
Price structure and derivatives
The seven-day gain conceals a different within-week path. Monday’s daily reference was $86,505.30, above Sunday’s $84,392.47. The decline between those two completed daily references was 2.44%, even though the full September 20 to 27 comparison gained 3.94%. Monday’s value is a dated close reference, not an intraday weekly high. This pattern cautions against describing the week as uninterrupted acceleration.
A separate Deribit snapshot at September 28, 02:10:01 UTC showed approximately $862.3 million of open interest in its Bitcoin perpetual contract. Deribit defines that inverse contract’s amount in U.S. dollars. This is a single-venue point-in-time position stock, not fund inflow, market-wide leverage or a directional long signal. No comparable historical positioning window is established here. The observation adds context without proving that leverage is safe or crowded. Deribit data, definitions.
Macro and liquidity
The Federal Reserve’s September 16 increase left its target range at 3.75% to 4.00%. That is a continuing policy backdrop, not a fresh September 21 through 27 decision. In the September 25 H.15 release, the five-year inflation-indexed Treasury yield increased from 2.55% on September 18 to 2.70% on September 24, a 15-basis-point change within one release vintage. Higher real yields can increase the opportunity cost of assets without contractual income. They do not isolate the cause of Bitcoin’s movement. Policy statement, H.15.
The September 24 H.4.1 release showed weekly average reserve balances of $2.930193 trillion, down $83.601 billionfor the week ended September 23. The weekly average Treasury General Account rose $100.056 billion to $977.084 billion. Wednesday reserve balances were $2.969922 trillion, a different observation convention. These figures describe particular U.S. balance-sheet channels; they do not form a complete global liquidity measure. H.4.1.
A reliable aggregate stablecoin change is not established here because the retrieved API aggregate and website total have unreconciled coverage or timing differences. The Chicago Fed’s explanatory page was readable, but the current numerical financial-conditions series was not verified. Consequently, the report cannot claim broad liquidity easing. Stronger fund demand has developed alongside, rather than erased, these macro constraints.
Corporate ownership and financing
Strategy’s September 21 filing disclosed 950 Bitcoin purchased for $75.7 million during September 14 through 20, bringing holdings to 846,000 as of September 20. The same filing reported $174.0 million of preferred-share repurchases and no shares sold through its at-the-market program during that period. Bitcoin purchases used U.S. dollar cash. These are separate uses of corporate resources. Strategy Form 8-K.
The disclosure is new relative to the previous issue’s retained September 14 filing, but its transactions precede this reporting week. It does not establish purchases during September 21 through 27 or a September 27 holdings balance. A large corporate treasury’s ownership stock, marginal purchases and financing obligations should remain separate. This issuer example cannot represent all corporate demand, and no broad ownership-concentration conclusion follows from it.
Custody, protocol and miner economics
Mempool.space’s seven completed daily estimates average 934.70 EH/s, rounded to 935 EH/s for the dashboard. Interval-end timestamps September 22 through 28 map to completed dates September 21 through 27. Difficulty remains 132.76 trillion after the 4.16% September 19 increase. That is evidence about network work and adjustment, not a newly observed difficulty increase this week.
Hashrate is inferred from block production and varies with block timing. It does not measure beneficial ownership, prove decentralization, protect a price floor or establish miner profitability. A miner-economics conclusion would also require current fee revenue, power costs, equipment efficiency and financing information. Those inputs are not sufficiently complete in this edition.
Bitcoin Core’s official release record still identifies 31.1, released July 8, as maintenance context. The release notice is not new September news or proof of universal deployment. Custody remains a different question: chain operation does not certify key management, intermediary solvency or recovery arrangements. No comprehensive custody incident review or new custody milestone is established here. These are limits on what can be concluded, not findings of no change. Bitcoin Core release.
Conditional paths and trigger map
Constructive continuation: The same series retains $80,000 for at least three consecutive completed UTC days, the next completed five-session fund window is positive, and the twenty-session total remains positive without renewed issue-to-issue deterioration. Repeated alignment would strengthen the medium-term case. Losing the price reference alongside net withdrawals would challenge it.
Uneven recovery: Price retains the area but fund flows weaken or alternate. The latest intermediate pass would remain historical evidence, while confidence in persistence would stop improving. Renewed consistent alignment in either direction would supersede this interpretation.
Deterioration: At least three consecutive completed daily references below $76,000 combine with a negative completed five-session fund window. Sustained recovery above $80,000 with renewed inflows would challenge that case. These are qualitative research conditions, not ranked probabilities.
The next review will retain these reference levels and conventions. It will also examine original yield releases, reserve-balance dates, corporate financing disclosures and the same network estimator. A change in any reference or observation convention must be explained. A single weaker day may deserve attention before a full condition is met, but it does not by itself complete the deterioration test.
Horizon Posture
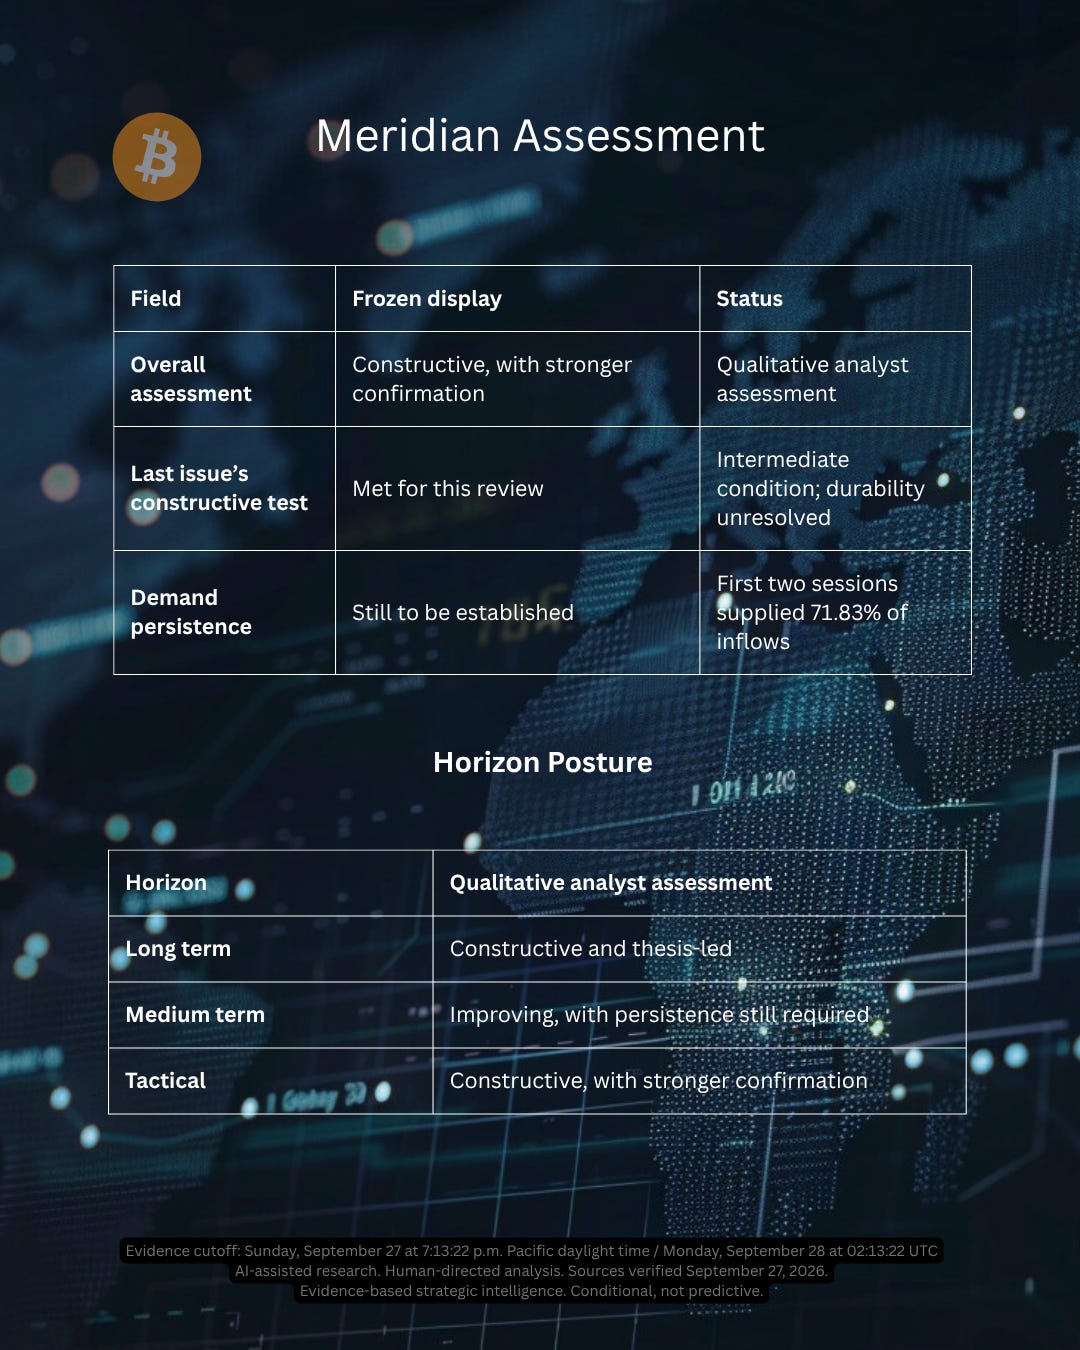
Long term: Constructive and thesis-led. Sustained deterioration in credible ownership access, protocol integrity or adoption evidence would challenge the thesis. A price rally or hashrate reading alone does not resolve those questions.
Medium term: Improving, with persistence still required. The broader flow balance and repeated sessions now support an upgrade from last week’s conditional stance. Renewed depletion of that balance or deteriorating financing conditions would weaken it.
Tactical: Constructive, with stronger confirmation. The defined intermediate test is met. Failure to retain $80,000 alongside renewed withdrawals would reduce that assessment before any stronger regime claim could be justified.
Contrary evidence and limitations
The strongest contrary case is that a large early-week inflow impulse loses force while real yields rise and reserve balances contract. Bitcoin ended below Monday’s daily reference despite the positive seven-day result. One strong fund week could therefore coexist with an incomplete broader recovery.
The strongest challenge to excessive caution is equally concrete: seven daily references held above the carried level, every fund session was positive, and the wider balance improved. Ignoring those observations would preserve an old assessment after its evidence changed. Missing market-wide leverage, executable depth, stablecoin comparability and ownership attribution limit the scale of the upgrade, rather than nullifying the verified improvement.
Meridian Strategic Conclusion
WCIR 027 asked demand to follow the price recovery. This week it did so across the specified completed sessions, and the price-duration condition held. The tactical assessment can improve on that basis.
The remaining uncertainty concerns durability under a demanding macro backdrop. Further constructive evidence would come from continued retention of the same reference, repeated demand beyond this week and resilience in the wider balance. The report therefore recognizes stronger confirmation while keeping its long-term thesis, medium-term persistence test and tactical condition distinct. The next issue should test this conclusion against new evidence, including evidence that challenges it.
Methodology and Principal Sources
Price uses Coin Metrics PriceUSD, U.S. dollars per Bitcoin, at the provider’s UTC day end. Raw date labels are retained. All price comparisons use this one captured vintage covering January 1, 2025 through September 27, 2026 without missing dates. Prices can be revised; the bounded daily maximum is not an all-time high. Fund totals use Farside’s displayed session totals. Missing reports, holidays and zeros are distinct. Network estimates use completed-date mapping. Macro release dates and observation periods are stated separately. Price convention, revision policy.
The linked primary sources above, Alternative.me’s sentiment release, and the accompanying frozen source map support the observations. Descriptive arithmetic is separated from Meridian’s qualitative interpretation. This is strategic research, not a forecast of short-term returns.
Editorial Note
Meridian Signal uses artificial intelligence to assist source discovery, comparison, drafting and arithmetic verification. Outputs are checked against retained evidence. Final editorial responsibility rests with Meridian Signal. Historical statements retain their original dates and conditions; this edition does not rewrite prior publications.
Research Disclosure
General information only, not individualized financial or investment advice. Bitcoin is volatile and loss of principal is possible. No probability, proprietary score or transaction instruction is assigned. AI-assisted. Human-directed. Source-verified.
Meridian Signal
Independent Strategic Intelligence Desk
Sources reviewed September 27, 2026, Pacific time. Evidence-based strategic intelligence. Conditional, not predictive.