
Weekly Conviction Intelligence Report | Evidence-Led Series
Evidence cutoff: September 21, 2026 at 8:41:18 AM PDT / 15:41:18 UTC. Reporting week: September 14–20. This edition includes historical price data retrieved September 21. Observation dates and source limitations remain explicit below.
Executive assessment
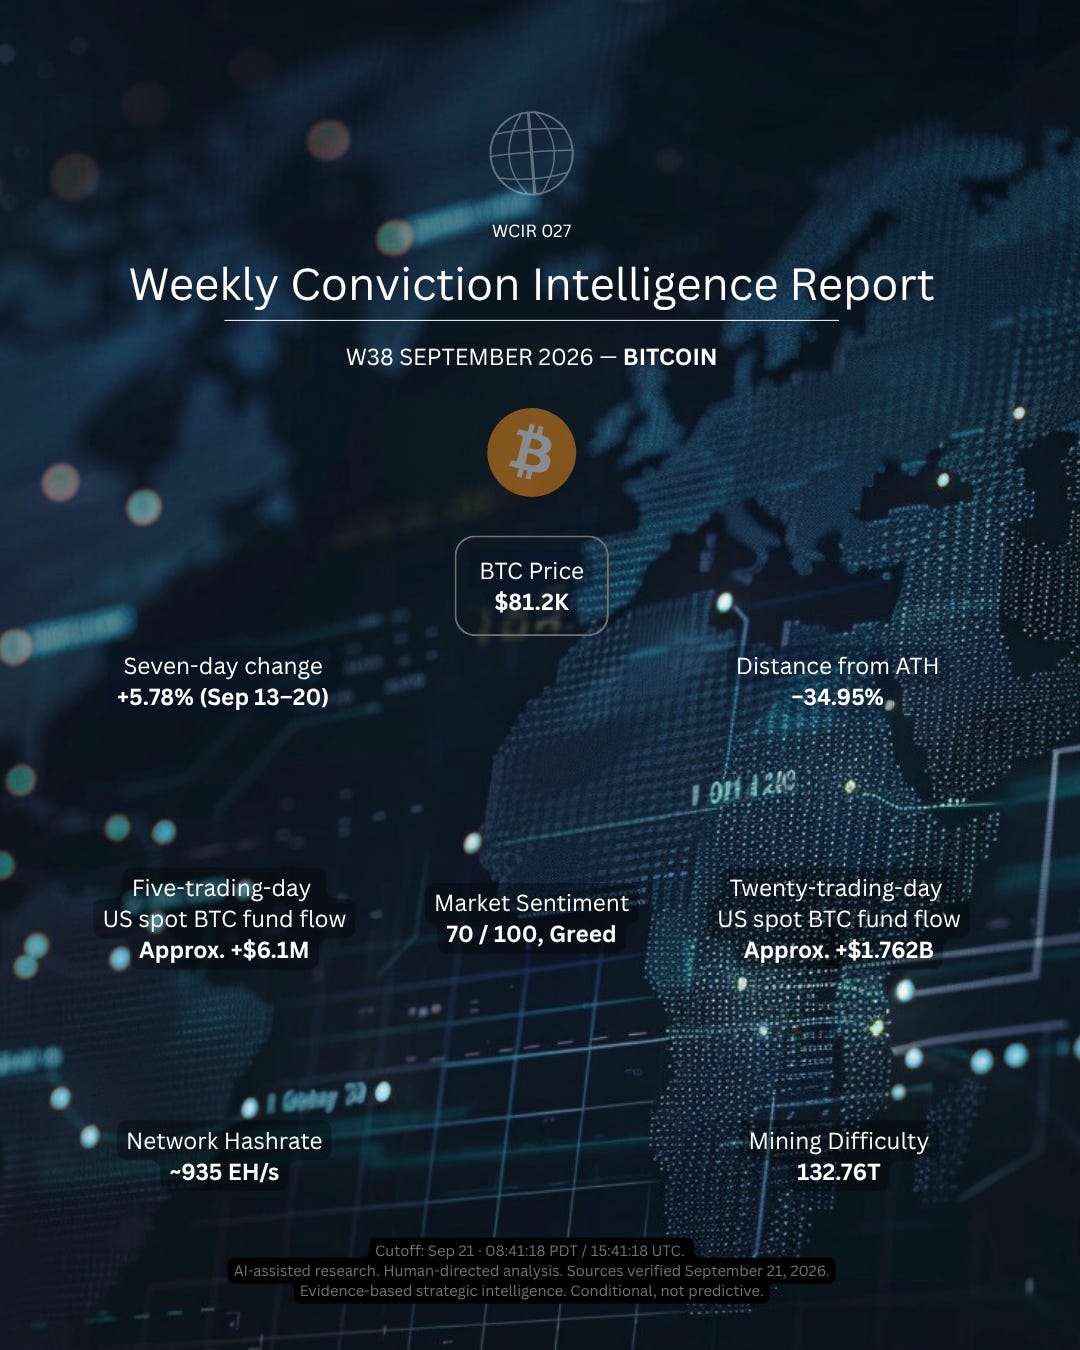
Bitcoin regained the $80,000 reference that framed the previous issue, but the demand evidence is less convincing than the price rebound.
Coin Metrics’ September 20 daily UTC closing reference was $81,194.74, up +5.78% from September 13 in the same series. U.S. spot Bitcoin funds finished September 14–18 with approximately +$6.1 million of net inflows. That positive balance followed substantial withdrawals and a late recovery. The twenty-session total remained positive at approximately +$1.762 billion, but below the previous issue’s wider-window reading. Coin Metrics data and convention, Farside Investors
Meridian’s qualitative assessment is partial confirmation, not a durable recovery verdict. Price repaired an important reference, and recent fund demand stopped deteriorating in net terms. Yet the weekly flow surplus is small, the wider flow balance weakened, and the Federal Reserve raised its policy rate during the week. These channels do not tell one uniformly constructive story.
The question now is whether daily closes can retain the recovered area while fund demand becomes less dependent on isolated strong sessions. The long-term thesis and the tactical assessment remain separate. No probability, proprietary score or capital instruction is assigned.
Executive Snapshot
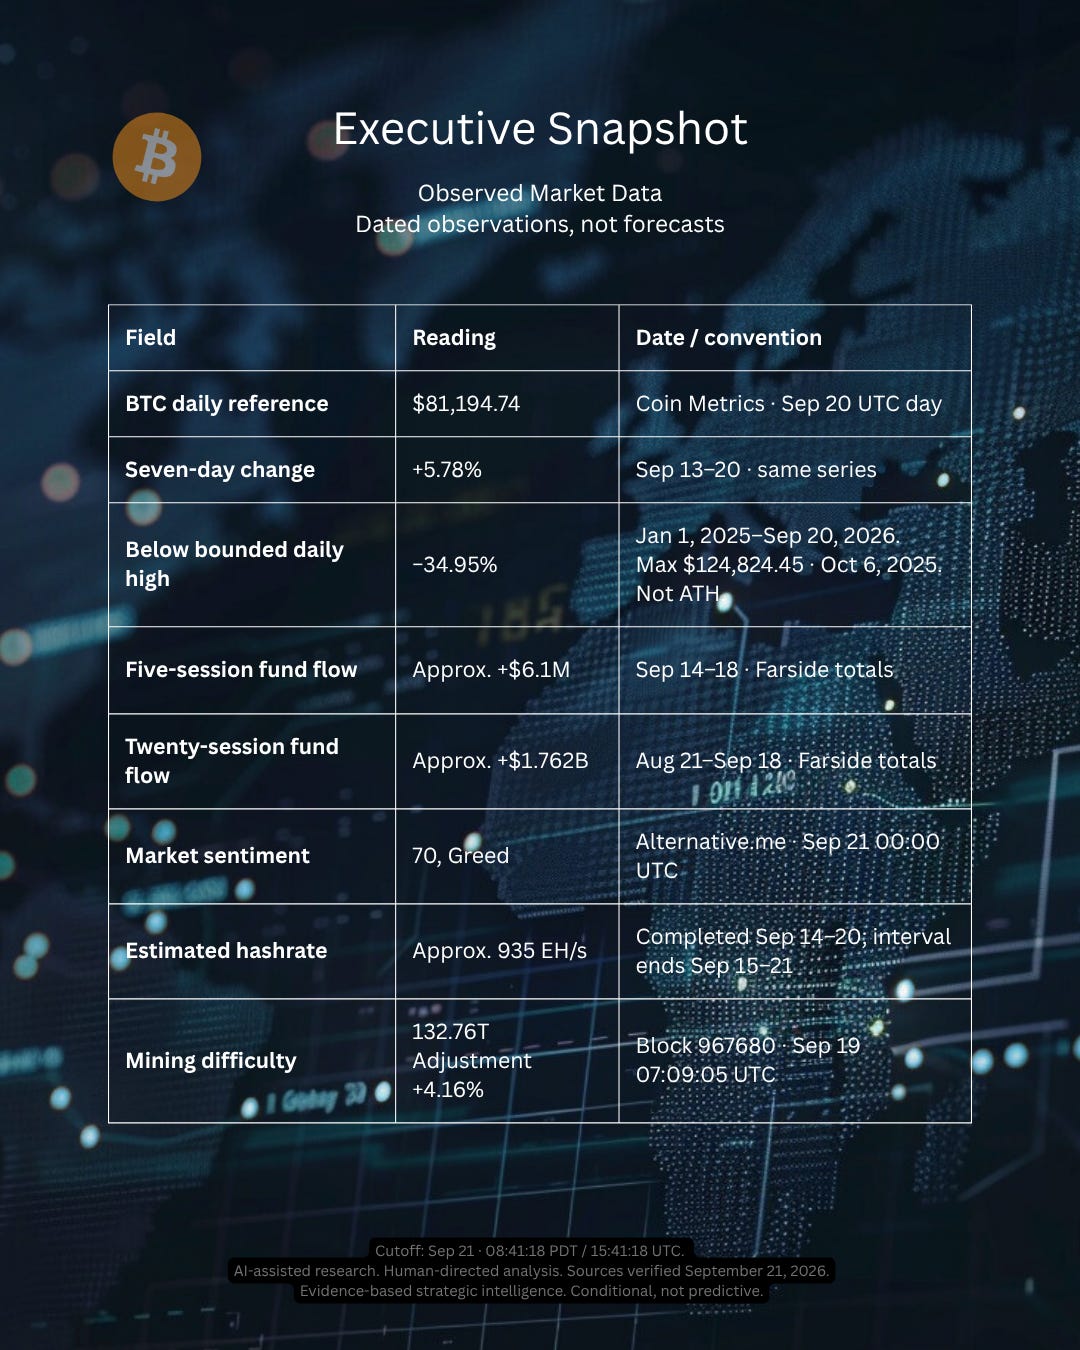
The maximum is a daily closing reference within a specified 628-day history, not an intraday or all-time high. EH/s means exahashes per second. Sentiment is a third-party composite. Sources: Coin Metrics, Farside, Alternative.me, mempool.space.
Last issue’s test
WCIR 026 asked whether Bitcoin could reclaim $80,000 alongside renewed multi-session inflows. It also identified continued references below $76,000 with another negative fund window as deterioration evidence.
Constructive test: partly met. In the newly disclosed Coin Metrics series, the September 18, 19 and 20 closing references were above $80,000. Three of the five fund sessions were positive, and the net total was slightly positive. That repairs part of the earlier tactical damage. It does not establish persistent, broad sponsorship beyond this week.
Deterioration test: not met as a combined weekly condition. The September 15 closing reference was below $76,000, but later closes recovered and the five-session fund total did not finish negative. One weak close is not the same as continuing weakness with another negative window.
These are qualitative follow-through assessments. WCIR 026 used a different price source and observation convention, and it did not define a minimum duration for “reclaim.” We therefore do not award a formal historical pass or silently rewrite that test. The seven-day return here is calculated from Coin Metrics’ own September 13 reference of $76,759.26, not from the prior article’s different reference price.
What changed, and what did not
Price improved. The latest weekly closing comparison is positive, and the last three completed UTC dates sit above $80,000. The recovered area is useful for continuity; it is not guaranteed support or a model target.
The shorter fund window improved while the wider one weakened. WCIR 026 reported approximately −$288.1 million over September 4 and September 8–11. The current five-session window is September 14–18, with no shared sessions. The wider twenty-session windows overlap, so their decline from approximately +$3.310 billion to +$1.762 billion is not a separate flow loss. Older observations leave the rolling sum as new ones enter.
Sentiment warmed and difficulty increased. Alternative.me moved from 57 to 70, retaining its Greed label. The seven-day hashrate estimate remained near the prior issue’s rounded 939 EH/s, while difficulty rose to 132.76 trillion. Sentiment, estimated computational work and difficulty describe different mechanisms. None independently establishes durable buying.
Three continuities matter: the wider fund balance is still positive; network activity remains substantial; and the report still lacks a complete derivatives, market-depth or ownership-attribution picture. Those continuities constrain both bullish and bearish interpretations.
Institutional demand: the sequence beneath the total
The week’s displayed fund totals were +$159.9 million, −$450.4 million, −$295.9 million, +$159.5 million and +$433.0 million. Without Friday’s inflow, the preceding four sessions sum to −$426.9 million. Friday therefore changed the weekly sign. It should not be mistaken for five days of steady accumulation. Within Friday, FBTC contributed +$310.7 million of the +$433.0 million total, illustrating concentration in the strongest session. Farside Investors
Meridian’s inference is that the demand recovery needs repetition. A near-zero weekly balance can accompany a substantial price rebound because fund flows are only one ownership channel, and price depends on the transactions occurring at the margin. This report cannot identify all buyers or prove that funds caused the rebound.
The appropriate next comparison is the next completed set of sessions, with its dates stated, alongside the direction of the wider balance. September 21’s unreported issuer entries are excluded, despite a displayed aggregate zero. Missing reports are not confirmed zero flows. Rounded provider totals and subsequent revisions can affect narrow net balances.
Macro and liquidity: a more demanding backdrop
On September 16, the Federal Reserve raised the federal funds target by a quarter percentage point to 3.75%–4.00%. Its statement described solid activity and elevated inflation. This is a dated policy decision, not a forecast for a future meeting. Federal Reserve statement
The September 18 H.15 release showed a five-year inflation-indexed Treasury yield of 2.46% on September 17, compared with 2.38% on September 11. The increase is eight basis points within that release. It is not a Monday live yield or a direct comparison with WCIR 026’s differently dated observation. Higher real yields can raise the opportunity cost of assets without contractual income, but the available evidence does not isolate the policy decision’s effect on Bitcoin. Federal Reserve H.15
The balance-sheet picture is more nuanced. In the September 17 H.4.1 release, weekly average reserve balances were $3.013794 trillion, up $22.484 billion for the week ended September 16. The Wednesday level was $2.921536 trillion. The weekly average Treasury General Account fell by $6.307 billion to $877.028 billion. These daily and weekly observations must not be mixed. Federal Reserve H.4.1
A rise in reserves does not cancel the rate increase, and neither establishes a complete global liquidity impulse. A broad dollar update, adjusted financial conditions, offshore liquidity and current stablecoin supply are not verified here. The practical implication is conditional: persistent demand would make a rebound more persuasive against this rate backdrop; a stronger price alone cannot certify easier financial conditions.
Corporate ownership and financing
Strategy’s September 14 filing reported no Bitcoin purchases or sales and no shares sold through its market offering program during September 8–13. It reported approximately 845,050 Bitcoin held as of September 13 and $139.3 millionspent repurchasing a preferred security during the disclosed period. The preferred repurchase is a use of corporate capital, not Bitcoin demand. Strategy filing
The filing date falls inside this reporting week, but the transaction period precedes it. No later completed activity period was verified for this edition. We do not carry “no purchases” forward into September 14–20 or treat the September 13 holding as a certified September 21 balance.
The broader mechanism remains important: a large treasury can be a major owner without being a marginal buyer. Its financing access, fixed commitments, repurchases and cash needs affect the transmission between its securities and Bitcoin. This issuer example is not a census of corporate demand, and it does not establish forced selling or sector-wide accumulation.
Custody, protocol and network
The mempool.space response supports approximately 935 EH/s over seven completed dates, September 14–20. The endpoint’s interval-end labels run September 15–21; the calculation uses those seven observations, not its separate current-hashrate field. Difficulty rose approximately 4.16% to 132.76 trillion at block 967680. mempool.space
Hashrate is an estimate influenced by variable block production. It is not an inventory of installed equipment, a measure of beneficial ownership or proof of a price floor. Difficulty describes the network adjustment; it does not certify miner profitability. Fees, energy costs, financing and equipment efficiency would be needed for a stronger economic assessment.
Earlier protocol maintenance remains relevant but is not repackaged as September news. The retained Bitcoin Core release record identifies version 31.1 on July 8. Its June 6 advisory described a privacy issue in specified private-broadcast configurations of version 31.0. A release notice does not establish universal deployment, and a privacy advisory is not automatically a consensus failure. Bitcoin Core release record, June advisory
Custody is a separate layer. A functioning chain does not attest to private-key management, intermediary solvency, recovery processes or legal recourse. No new custody milestone or broad incident conclusion is verified here. That is a coverage limit, not evidence that nothing happened.
Conditional paths and falsifiers
Constructive path: completed daily references retain the recovered $80,000 area while positive fund demand repeats beyond this week and the wider balance stabilizes. A renewed loss of that area with repeated withdrawals would challenge the interpretation.
Uneven-recovery path: daily references move around the recovered area while shorter flow windows alternate and the wider balance remains positive. Persistent alignment of price and demand in either direction would make this description less useful.
Deterioration path: daily references repeatedly fall below the carried $76,000 reference while another completed five-session fund window turns negative. Sustained recovery above $80,000 with repeated inflows would challenge that case.
These are analyst scenarios, not ranked probabilities. For the next review, “retaining” or “repeatedly below” means examining at least three consecutive completed UTC daily references in this same series. That convention is prospective editorial clarification, not a retroactive definition of earlier calls, a trading rule or a proprietary model.
Horizon Posture
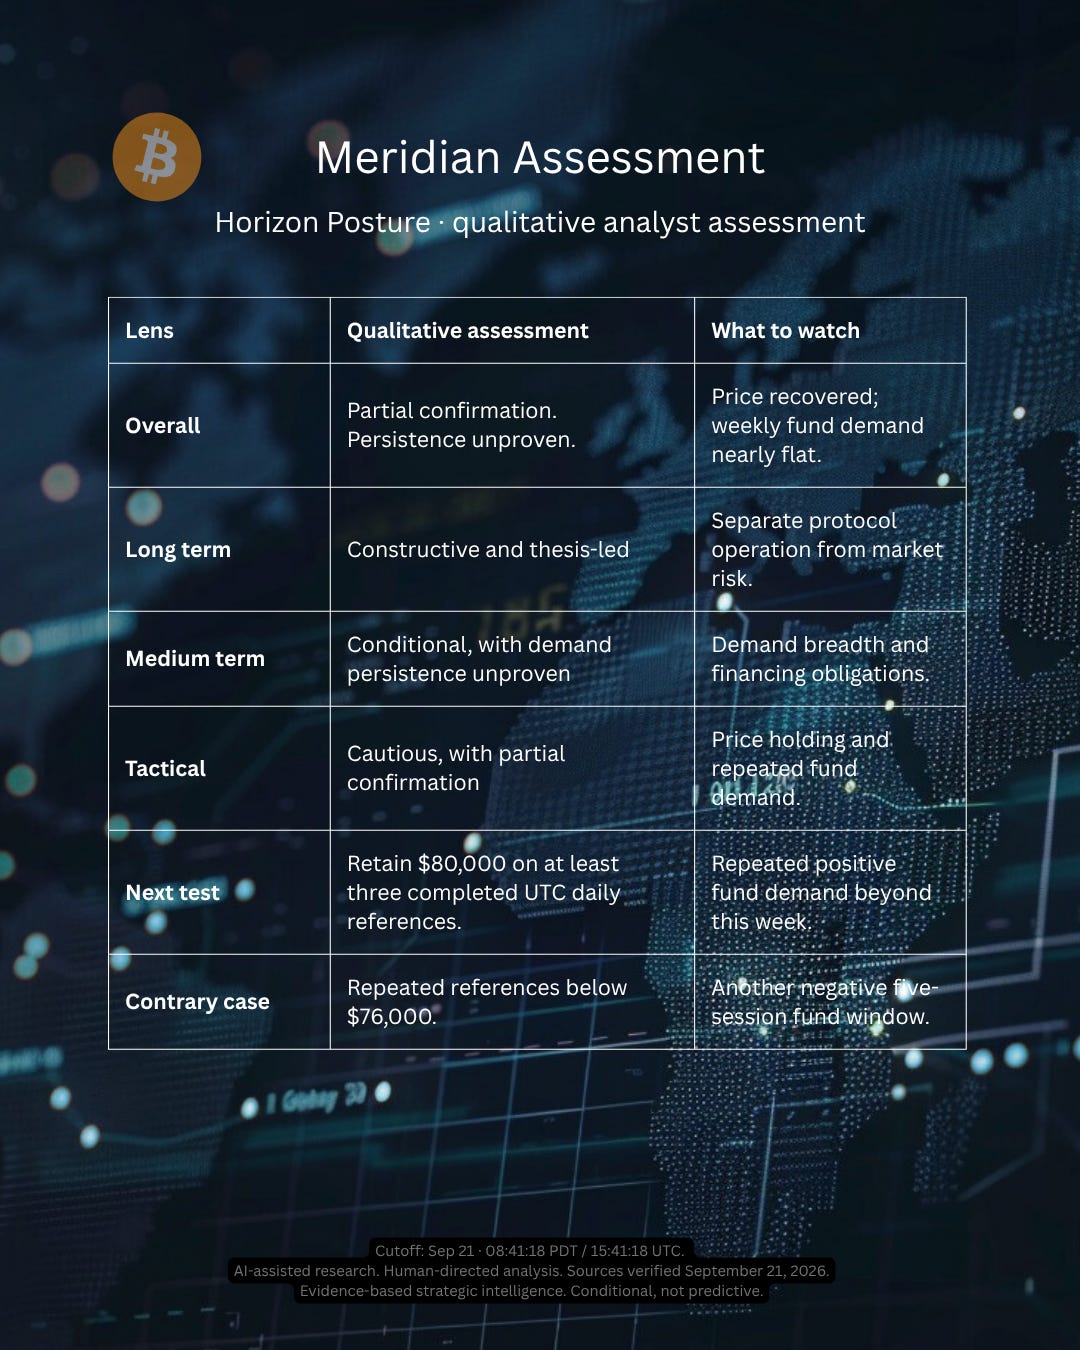
Long term: Constructive and thesis-led. Sustained deterioration in ownership access, monetary integrity or adoption evidence would challenge the thesis. Hashrate alone does not protect it.
Medium term: Conditional, with demand persistence unproven. Repeated fund inflows and a stabilizing wider balance would strengthen the assessment; continued depletion would weaken it.
Tactical: Cautious, with partial confirmation. The price reclaim is observable, but its durability still needs corroboration.
The next review will revisit the same $80,000 and $76,000 references, the next completed fund windows, original policy and yield releases, dated corporate filings, and the same network estimator. Changing a reference will require an explanation rather than silently replacing an inconvenient test.
Contrary evidence and limits
The strongest challenge to excessive caution is the combination of a positive seven-day price comparison, three closes above $80,000 and a still-positive twenty-session flow balance. The strongest challenge to a durable-recovery claim is concentrated late-week demand, a much weaker wider flow balance and higher policy and real rates.
The price source changed to Coin Metrics’ multi-venue daily USD reference. Every price comparison here uses that one retrieved vintage. Its 628 daily observations cover January 1, 2025–September 20, 2026 without missing dates. This verifies the stated lookback, not all historical prices. The provider can revise prices after errors are identified. The closing maximum cannot be compared directly with an old intraday peak or a differently timed reference. Price definition, revision policy
Derivatives positioning, executable depth and beneficial-owner attribution remain unverified. Sentiment partly reflects market inputs and is not wholly independent confirmation. Macro releases are lagged. Source access and incomplete coverage limit the conclusions; they do not justify filling gaps with stronger language.
Meridian Strategic Conclusion
Bitcoin repaired part of the deterioration recorded in WCIR 026. The closing reference recovered above $80,000 and the short fund window returned to a positive balance. That is meaningful improvement.
The missing proof is persistence. Friday’s inflow rescued a week that had been negative, the twenty-session balance weakened, and the rate backdrop became more demanding. The evidence supports recognizing a rebound without declaring that the surrounding demand structure has become durable.
Meridian therefore remains constructive and thesis-led over the long term, conditional over the medium term, and cautious tactically with partial confirmation. The next issue must resolve whether the recovered area held and whether demand repeated. A stronger conclusion should follow stronger evidence, not simply a stronger headline.
Methodology and disclosure
Price uses Coin Metrics PriceUSD at daily frequency: USD per Bitcoin, with the provider’s UTC day-end convention and date labels. It is not an executable quote at the evidence cutoff. Fund flows sum Farside’s displayed Total column over explicit trading sessions. Network estimates use the provider’s completed-date mapping. The accompanying source map records retrieval dates, retained evidence and limitations.
WCIR is Meridian Signal’s Evidence-Led strategic research series. Observations, descriptive arithmetic and qualitative analyst judgments are distinct. Its purpose is to explain changing market structure and the evidence that would alter an assessment, not predict short-term prices or direct transactions.
Meridian Signal uses AI-assisted systems for source discovery, comparison, research organization and arithmetic verification. AI outputs are not authoritative by default. Material claims are checked against available sources, and final editorial responsibility remains with Meridian Signal. This draft requires human publication review.
Meridian Signal
Independent Strategic Intelligence Desk
AI-assisted research. Human-directed analysis. Sources reviewed September 21, 2026; retained older observations are dated above. Evidence-based strategic intelligence. Conditional, not predictive.
General information only. Not individualized financial or investment advice. Bitcoin is volatile and loss of principal is possible.