

Weekly Conviction Intelligence Report | Evidence-Led Series | Week 37
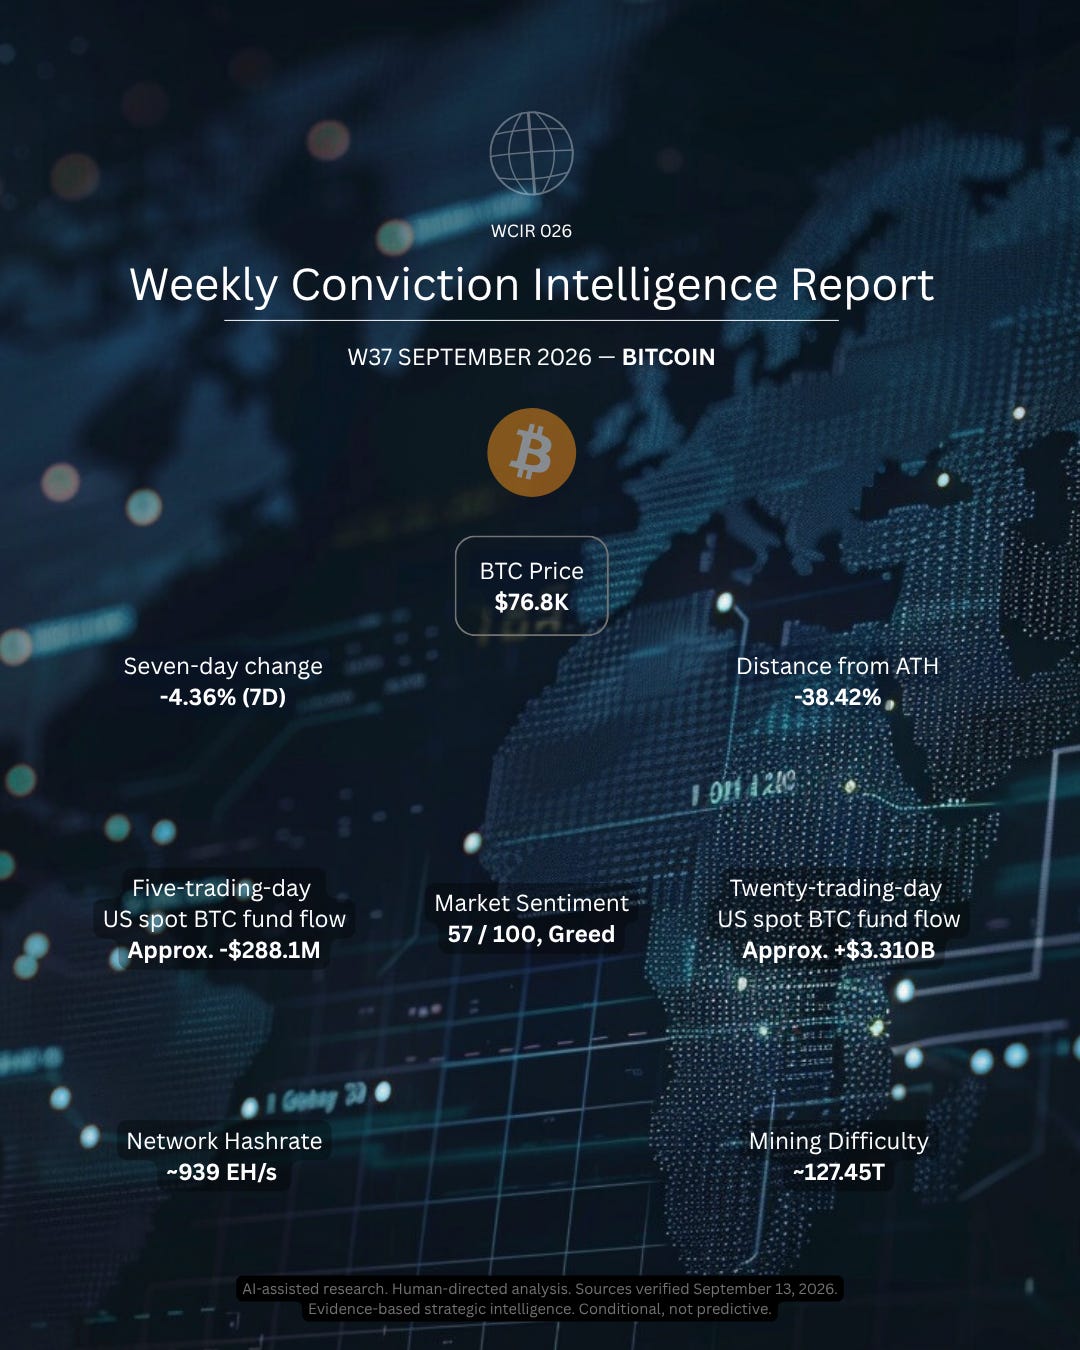
The latest five fund sessions reversed into net outflows while Bitcoin lost its recent $80,000 reference. The wider twenty session flow total remained positive, so the central question is whether the weakness persists.
Evidence cutoff: September 13, 2026 at 7:09:48 p.m. Pacific / September 14 at 02:09:48 UTC.
Executive assessment
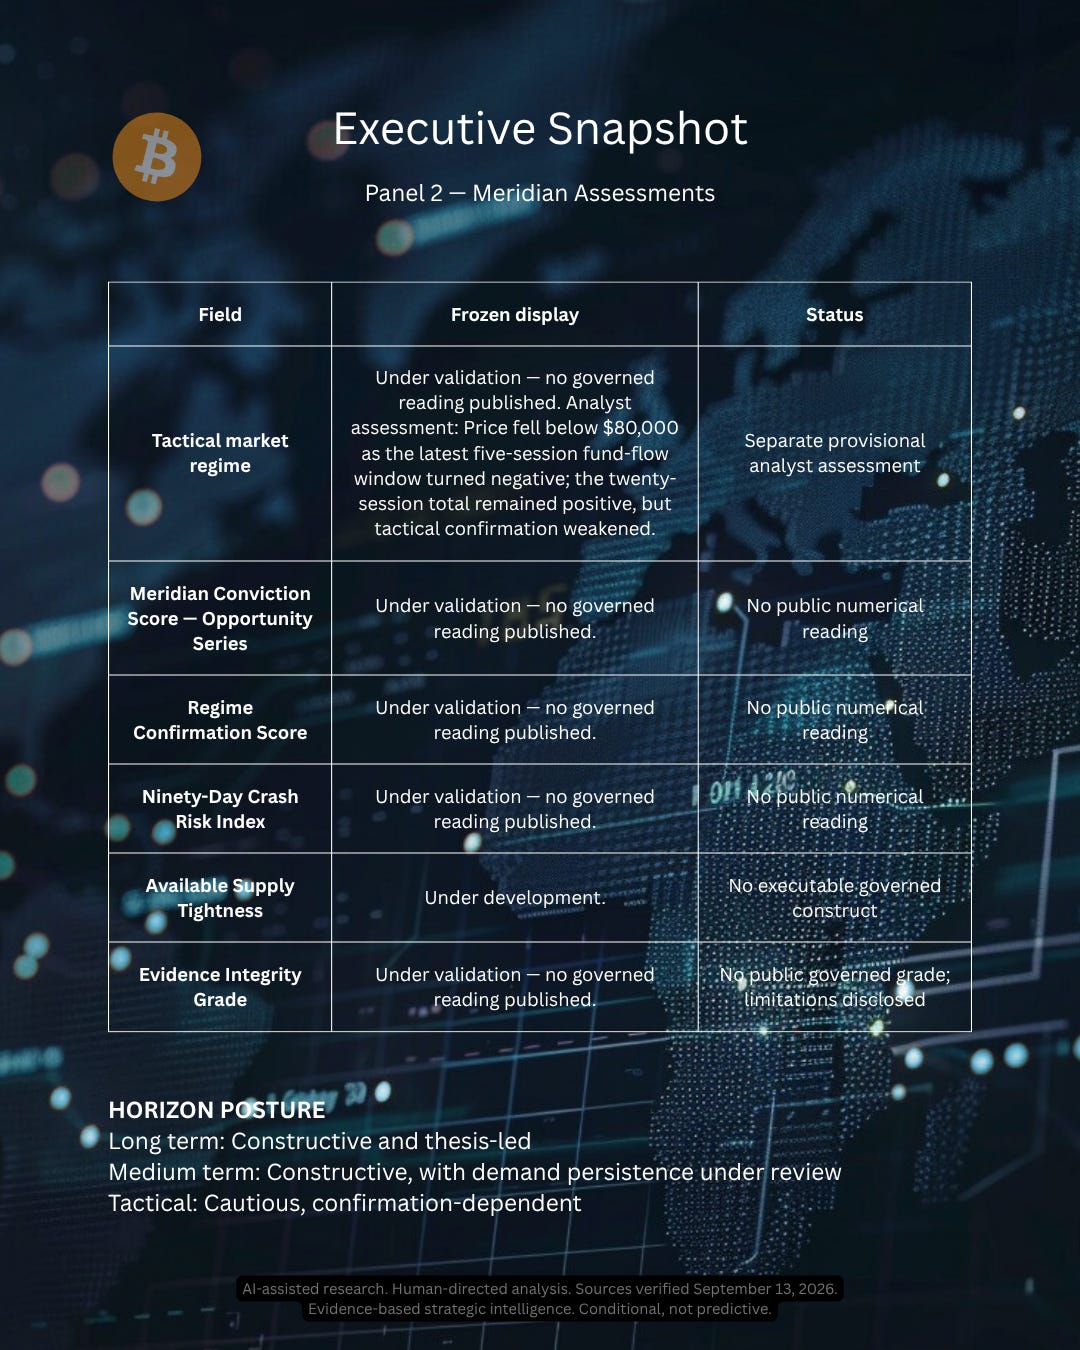
Bitcoin lost the recovery level that framed WCIR 025. The FRED distributed Coinbase daily reference finished September 13 at $76,804.92, down 4.36% over seven days. The latest five available U.S. spot Bitcoin fund sessions totaled approximately negative $288.1 million, reversing the prior issue’s positive weekly window. Those observations answer the opening question directly: price and the most recent fund demand both weakened.
The broader evidence is less one sided. The twenty session fund flow total remained approximately positive $3.310 billion, and estimated network hashrate averaged approximately 939 exahashes per second across the seven completed dates through September 13. Market sentiment cooled from 71 to 57, still classified as Greed. These observations do not erase the tactical deterioration, but they argue against describing one weak week as a complete breakdown.
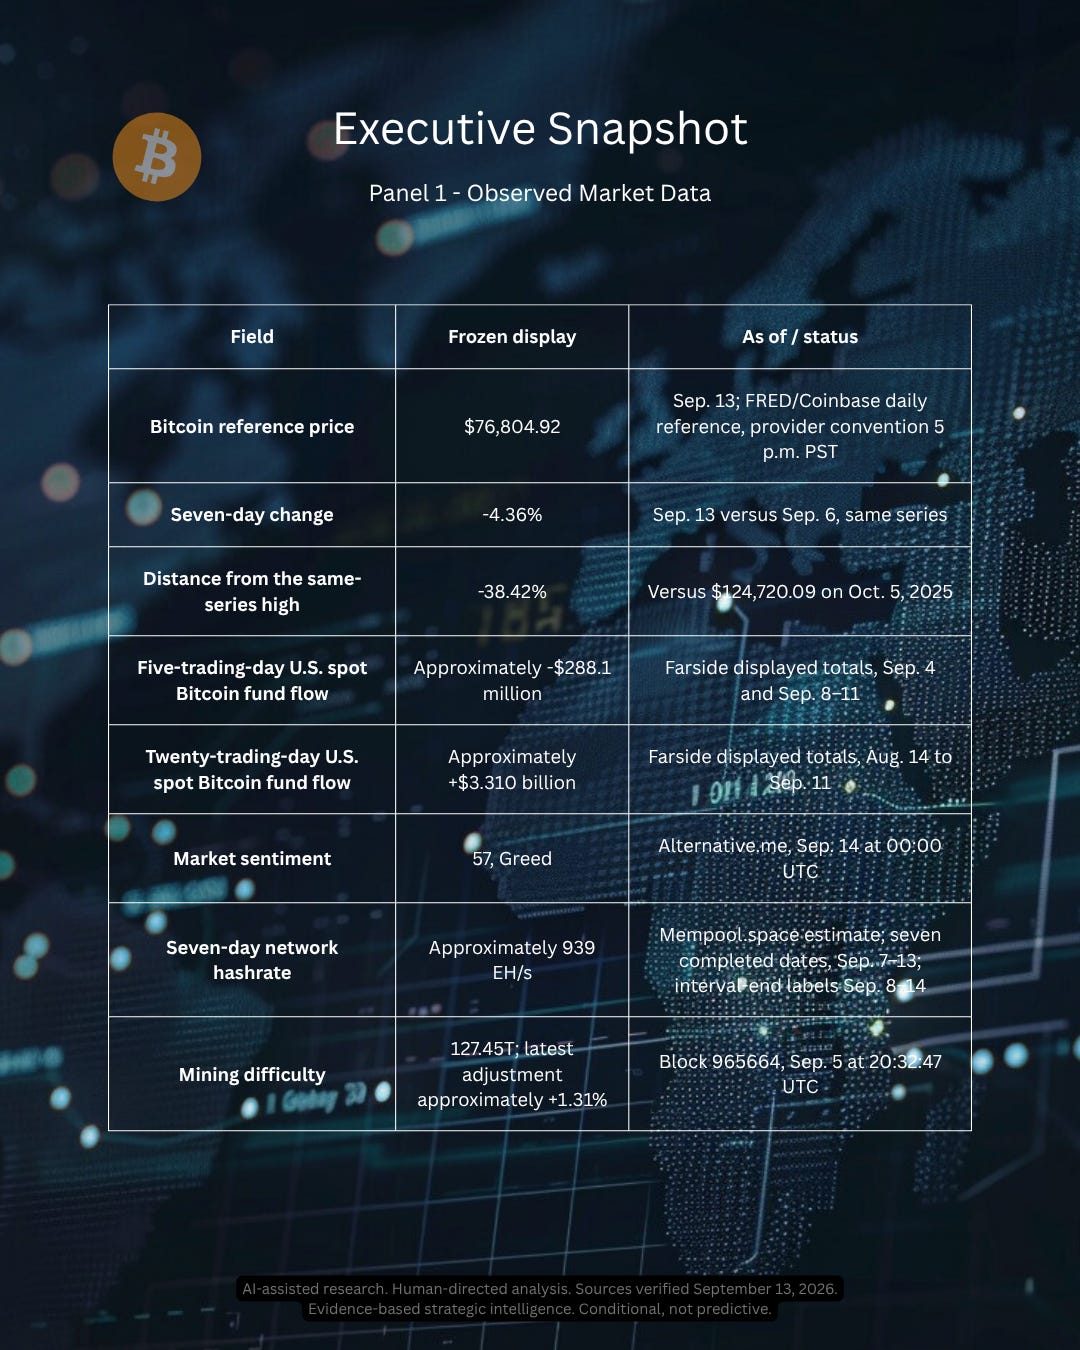
Our provisional analyst assessment is: Price fell below $80,000 as the latest five session fund flow window turned negative; the twenty session total remained positive, but tactical confirmation weakened. This is an interpretation of public evidence, not a governed regime reading. Governed fields remain withheld.
Executive Snapshot
Panel 2: Meridian Assessments
Three material changes
1. Bitcoin fell back below $80,000. The September 13 daily reference was $76,804.92, compared with $80,309.06 on September 6. That is a seven day decline of 4.36%. The same series remains 38.42% below its October 5, 2025 high of $124,720.09. The move reverses the prior issue’s reclaim of $80,000 and weakens the immediate price confirmation case. It does not, by itself, establish a lasting trend. FRED Bitcoin
2. The latest five fund sessions turned negative. Farside’s displayed daily totals for September 4, 8, 9, 10 and 11 sum to approximately negative $288.1 million. September 10 contributed the largest outflow in that window at negative $282.7 million. The sign reversal is more informative than treating the previous week’s positive total as persistent by default. It is still an aggregator view of one public fund channel, not a complete measure of global demand. Farside Investors
3. Sentiment cooled while remaining in Greed. Alternative.me registered 57 on September 14 at 00:00 UTC, down from 71 in WCIR 025. The classification remained Greed. A lower reading is consistent with reduced confidence, but the index is a third party composite and not an independent forecast of price or flows. Alternative.me
Three important continuities
The wider fund flow window stayed positive. The twenty latest displayed sessions sum to approximately positive $3.310 billion. That total is slightly below WCIR 025’s approximately $3.444 billion but still provides a broader positive context. A positive twenty session sum can coexist with a negative current week, and neither window reveals the investors’ holding horizons.
Mining capacity remained substantial. Mempool.space’s daily estimate averaged approximately 939 EH/s across the completed dates from September 7 through September 13. The latest difficulty observation remained 127.45T, following the approximately positive 1.31% adjustment at block 965664. Estimated hashrate is volatile and model dependent, so this report does not treat a one week average as a network security verdict. Mempool.space mining data
Governed fields remain withheld. A weaker week does not activate a numerical conviction score, regime state, crash probability, supply metric or evidence grade. Public observations and analyst judgments remain separate from governed outputs. That continuity matters most when the headline evidence becomes less comfortable.
Macro and liquidity context
The latest Adjusted National Financial Conditions Index observation was negative 0.588 for September 4, compared with negative 0.585 for August 28 in the same retrieved vintage. More negative values indicate looser conditions relative to the index’s historical average, but this small weekly movement does not demonstrate a fresh Bitcoin liquidity impulse. The series is weekly, lagged and revisable. FRED ANFCI
The five year Treasury inflation indexed yield was 2.29% on September 10, up from 2.17% on September 4. Positive real yields provide a competing return in the financial system. Meridian’s inference is that persistent Bitcoin demand becomes more important when investors can earn a positive inflation adjusted yield elsewhere. That is a transmission framework, not a claim that real yields caused this week’s price decline. FRED five year real yield
Federal Reserve total assets were $6.740619 trillion on September 9, compared with $6.737204 trillion on September 2. The observed increase was $3.415 billion. The broad dollar index was 118.0732 on September 4, the latest admitted observation. These are useful conditions, but they have different observation dates and cannot be combined into a precise Sunday liquidity score. A comprehensive net liquidity assessment would also require Treasury cash, reverse repurchase balances, bank reserves and offshore conditions. FRED Federal Reserve assets, FRED broad dollar index
The balanced reading is that broad adjusted conditions remained loose relative to history, while real yields moved higher. That mix does not supply a simple directional answer. Bitcoin still has to demonstrate demand through observable price acceptance and fund activity.
Corporate ownership, financing, custody and protocol context
New disclosure, no new Bitcoin transaction. Strategy’s September 8 Form 8 K states that the company did not purchase or sell Bitcoin from August 31 through September 7. It reported approximately 845,050 Bitcoin held at an aggregate acquisition cost of $63.73 billion and an average cost of $75,412 per Bitcoin. This is a current disclosure about an unchanged reported Bitcoin position, not evidence of fresh weekly buying. Strategy Form 8 K
The same filing increased the authorized repurchase program for digital credit securities from $1 billion to $2 billion. It also reported $5.10 billion in a U.S. dollar reserve and $1.44 billion of cash as of September 7. These facts show that corporate Bitcoin exposure sits within a broader financing and capital structure. They do not establish sector wide corporate accumulation or guarantee future purchases.
Custody remains a separate risk layer. No new primary source custody milestone was admitted for this reporting window. That is not a declaration that nothing occurred. It means this report did not verify a new development strongly enough to add it as a weekly fact. Price performance, fund inflows and public company ownership do not attest to the security of private keys, devices, custodians, recovery processes or legal claims.
Protocol context comes from measured network operations. The hashrate observation is restored this week after verifying the provider’s units, interval end convention and completed date mapping. Blockchain.com and Coin Metrics were also evaluated as credible backup sources, but they were not silently substituted because estimator definitions and revisions are not automatically equivalent. Mempool.space remains the admitted primary estimator for this issue. Difficulty and estimated hashrate answer different questions, so neither should be treated as a complete network health score.
What is happening beneath the headline
The evidence shifted from recovery to retest. WCIR 025 paired a price reclaim with a positive weekly flow window. WCIR 026 records the opposite immediate combination: price moved below $80,000 and the latest five fund sessions turned negative. The twenty session total, however, remained positive. The market is therefore testing whether recent demand was durable or concentrated.
The constructive interpretation is that the current week is a pullback inside a still positive wider demand window. The contrary interpretation is that the five session reversal is the first sign that the previous recovery lacked staying power. The available data cannot settle that contest from a single week. The next observations should be judged by persistence rather than by the strongest daily move.
Sentiment provides a second cross check. A fall from 71 to 57 is directionally consistent with weaker price and flows, but the reading remains in Greed. If sentiment remains relatively warm while price and fund demand continue to deteriorate, that divergence would challenge the idea that confidence is translating into durable buying.
Conditional paths and horizon posture
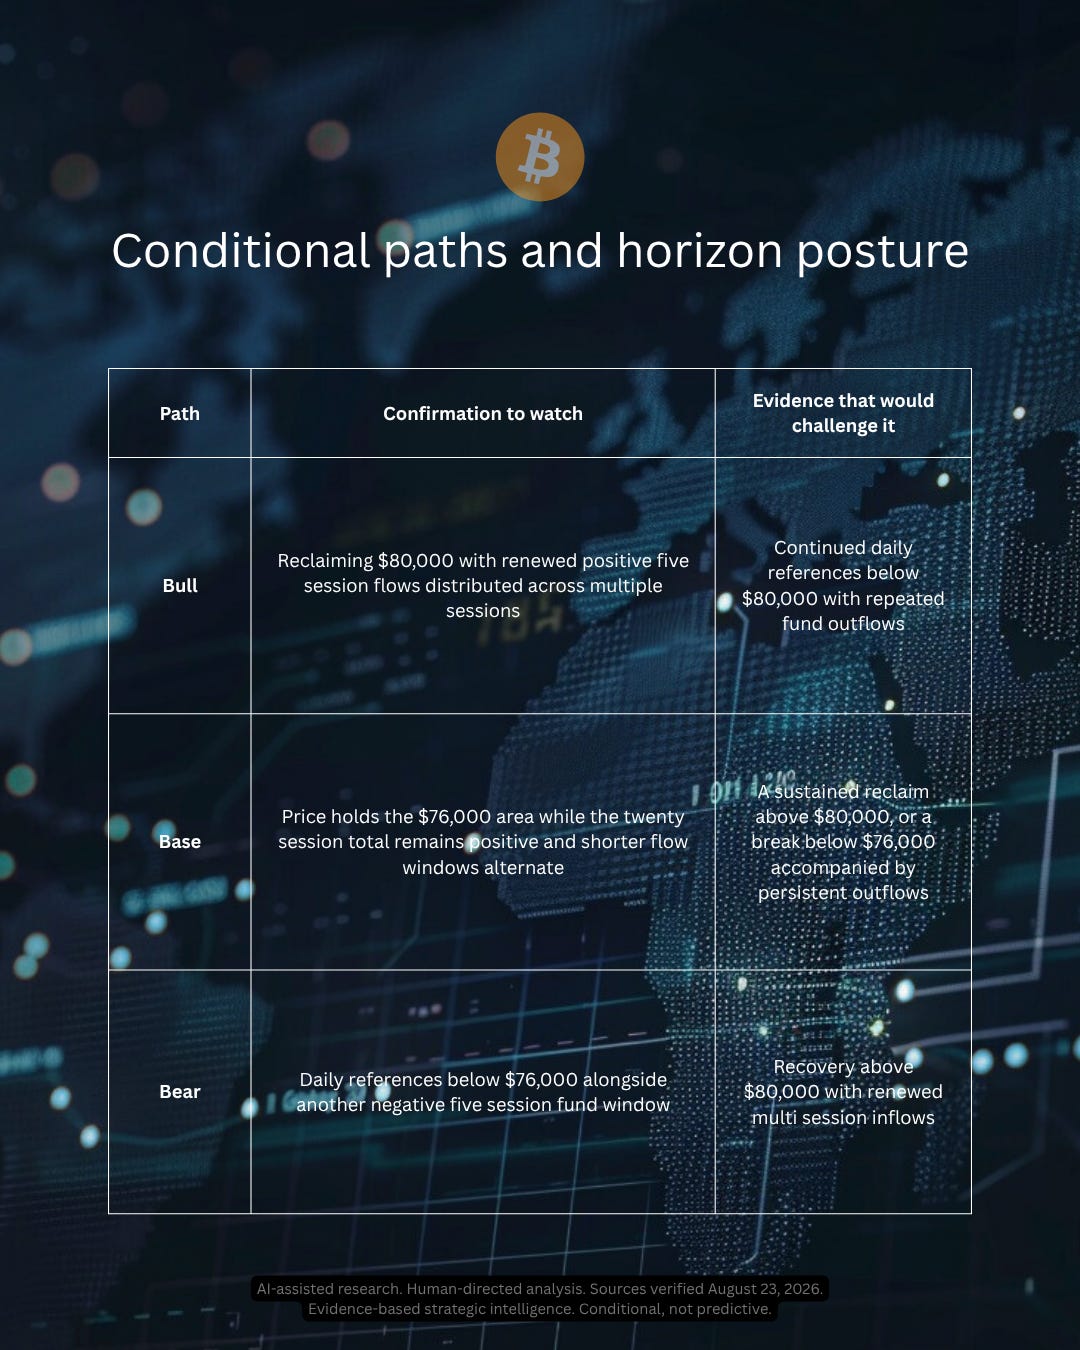
The $80,000 and $76,000 levels are analyst reference points carried forward for continuity. They are not model targets, promised support or resistance, or instructions to transact. No probabilities are assigned.
Long term: Constructive and thesis-led.
Medium term: Constructive, with demand persistence under review.
Tactical: Cautious, confirmation-dependent.
Different horizons can diverge. A tactical downgrade can be appropriate while the long term thesis remains intact. The reverse is also true: one positive week would not prove structural adoption or permanently easier financial conditions.
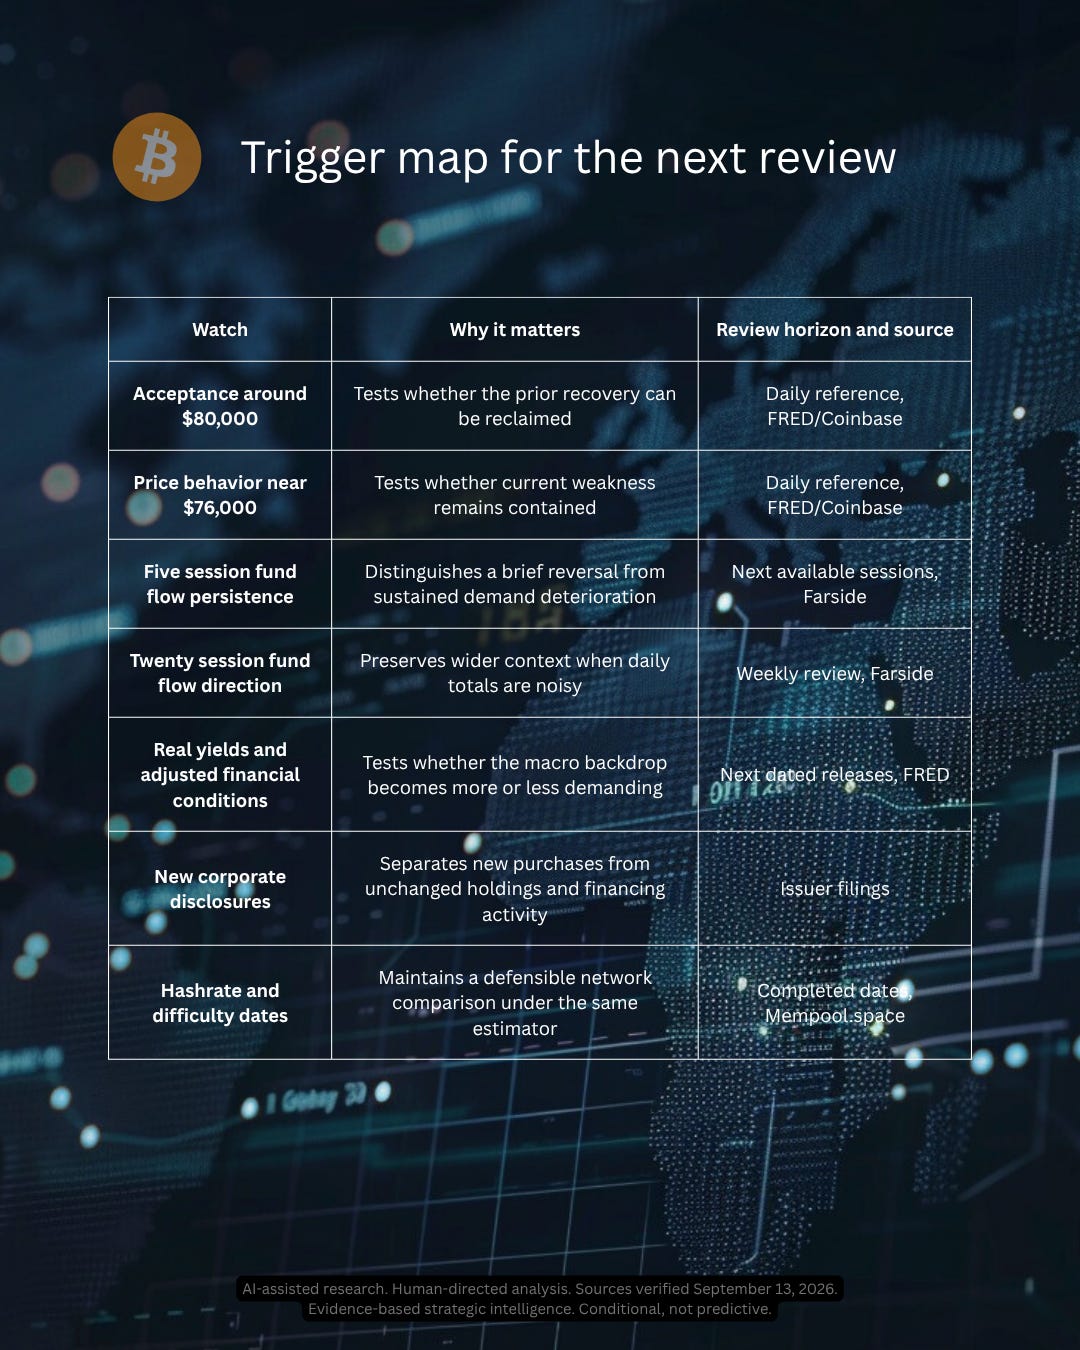
Trigger map for the next review
Contrary evidence and limitations
The strongest contrary evidence to the long term constructive posture is the combination of a negative five session flow window, loss of $80,000 and a substantial 38.42% distance from the same series high. If those conditions persist, the interpretation should weaken rather than being protected by a long term narrative.
Evidence also supports restraint against an overly bearish reading. Twenty session fund flows remained positive, the network continued to report substantial estimated computing activity, and financial conditions remained loose relative to the ANFCI’s historical average. None of these observations guarantees price support.
This issue does not provide verified derivatives funding, open interest, options positioning, exchange wide market depth or beneficial owner attribution. Those subjects are unavailable here, not labeled unchanged. Farside’s direct data routes returned access denied during collection; the same provider’s current public table was recovered through its public web representation. The provider notes that its table is generated automatically and can contain errors. Macro series are lagged and revisable. Hashrate is an estimate, and backup estimators were reviewed without being combined.
The controlled system operations candidate did not pass its fresh canonical byte retrieval gate because the Library file transfer returned an error. That makes WCIR 026 non-counting and leaves the sequence at 2 of 8. This operational result does not block the separately authorized public research preparation within the Sunday window. It also does not support an empirical validation claim.
Strategic conclusion
WCIR 026 records a meaningful tactical deterioration without declaring a settled breakdown. Bitcoin fell below $80,000, the latest five fund sessions turned negative and sentiment cooled. Those observations weaken the prior week’s confirmation case. The positive twenty session total and continued network activity preserve a broader context that remains more constructive than the weekly headline alone.
The next test is straightforward. A reclaim of $80,000 accompanied by renewed multi session inflows would repair part of the tactical damage. Continued references below $76,000 with another negative fund window would strengthen the contrary case. Between those outcomes, the base path is uneven demand and continued scrutiny of whether the positive wider flow total is being depleted.
Consistency requires the same discipline in both directions. We should not promote a one week recovery into a governed regime, and we should not convert a one week reversal into a forecast of collapse. The report remains most useful when it identifies the evidence, separates the dates, states the limitations and specifies what would change the assessment.
Methodology and principal sources
Price changes use the FRED distributed Coinbase daily reference. The provider convention is 5 p.m. PST, so it is not an executable cutoff time quote. The high comparison uses retrieved same series history. Fund flows sum Farside’s displayed Total column over the latest five and twenty available sessions; displayed aggregator totals are rounded and may be revised. Sentiment retains Alternative.me’s supplied label.
Mempool.space hashrate values are received in hashes per second and converted to exahashes per second. The seven date average uses the provider’s interval end mapping to the preceding completed date. Blockchain.com and Coin Metrics were reviewed as backups, with their separate definitions retained. The cutoff is the information boundary, not the measurement time of every source. Macro observations keep their own dates and release lags. Corporate filing dates remain distinct from transaction periods.
Qualitative scenarios, reference levels and horizon posture are analyst judgments. They are not governed classifications, probabilities, forecasts or capital instructions.
Editorial Note
The Bitcoin Weekly Conviction Intelligence Report is a strategic intelligence publication by Meridian Signal designed to evaluate Bitcoin through the lenses of market structure, institutional capital flows, liquidity conditions, supply dynamics, network security, and evolving risk.
Its purpose is not to predict short-term price movements or provide investment recommendations. It is designed to assess the quality of Bitcoin’s current structural position, identify meaningful changes in market conditions, and reduce uncertainty for long-term strategic decision-making.
Source-attributed observations, Meridian analyst assessments, and governed proprietary indicators are treated as separate forms of intelligence. Analyst assessments, qualitative scenarios, and horizon-specific posture represent human-directed judgments based on the evidence available at the stated cutoff. Governed numerical readings are published only after their data, methodology, validation, and activation requirements have been satisfied.
All assessments reflect the information available at the time of publication and may change as new evidence emerges.
Meridian Signal remains committed to evaluating structure over price, conditional paths over predictions, conviction over emotion, and signal over noise.
Research Disclosure
Meridian Signal uses artificial intelligence-assisted systems to accelerate public-source discovery, data comparison, research organization, arithmetic verification, and analytical synthesis. Artificial intelligence outputs are not treated as authoritative by default.
Material claims are evaluated against available sources, and all interpretations, strategic assessments, and editorial conclusions remain under institutional human direction and review. Meridian Signal retains final human editorial responsibility. Artificial intelligence has no authority to approve, publish, trade, or activate a governed Meridian indicator.
Proprietary formulas, weights, normalization rules, internal thresholds, private calculations, and calculation mechanics are not publicly disclosed. The absence of a governed reading does not imply a neutral condition; it means the applicable evidence, validation, or activation requirements have not yet been completed.
Meridian Signal
Independent Strategic Intelligence Desk
General informational analysis only. This is not individualized financial, investment, legal, tax, accounting, or custody advice. Bitcoin is volatile, and loss of principal is possible.