
Bitcoin finished four consecutive daily references below $76,000 while U.S. spot Bitcoin funds lost $1.282 billion over five sessions. That combination meets the deterioration test retained in the preceding report. Wednesday’s rebound above $80,000 lasted one observation, and the longer fund window weakened despite an improvement in selected U.S. banking-liquidity measures.
The immediate implication is a more defensive tactical assessment. Recovery requires sustained price persistence, a positive complete five-session fund window and a positive twenty-session total that does not deteriorate against its completed predecessor. All three conditions remain unmet.
Evidence cutoff is November 8, 2026 at 7:05:39 p.m. Pacific, November 9 at 03:05:39 UTC. Price observations cover November 2 through 8. The latest complete fund week covers November 2 through 6.
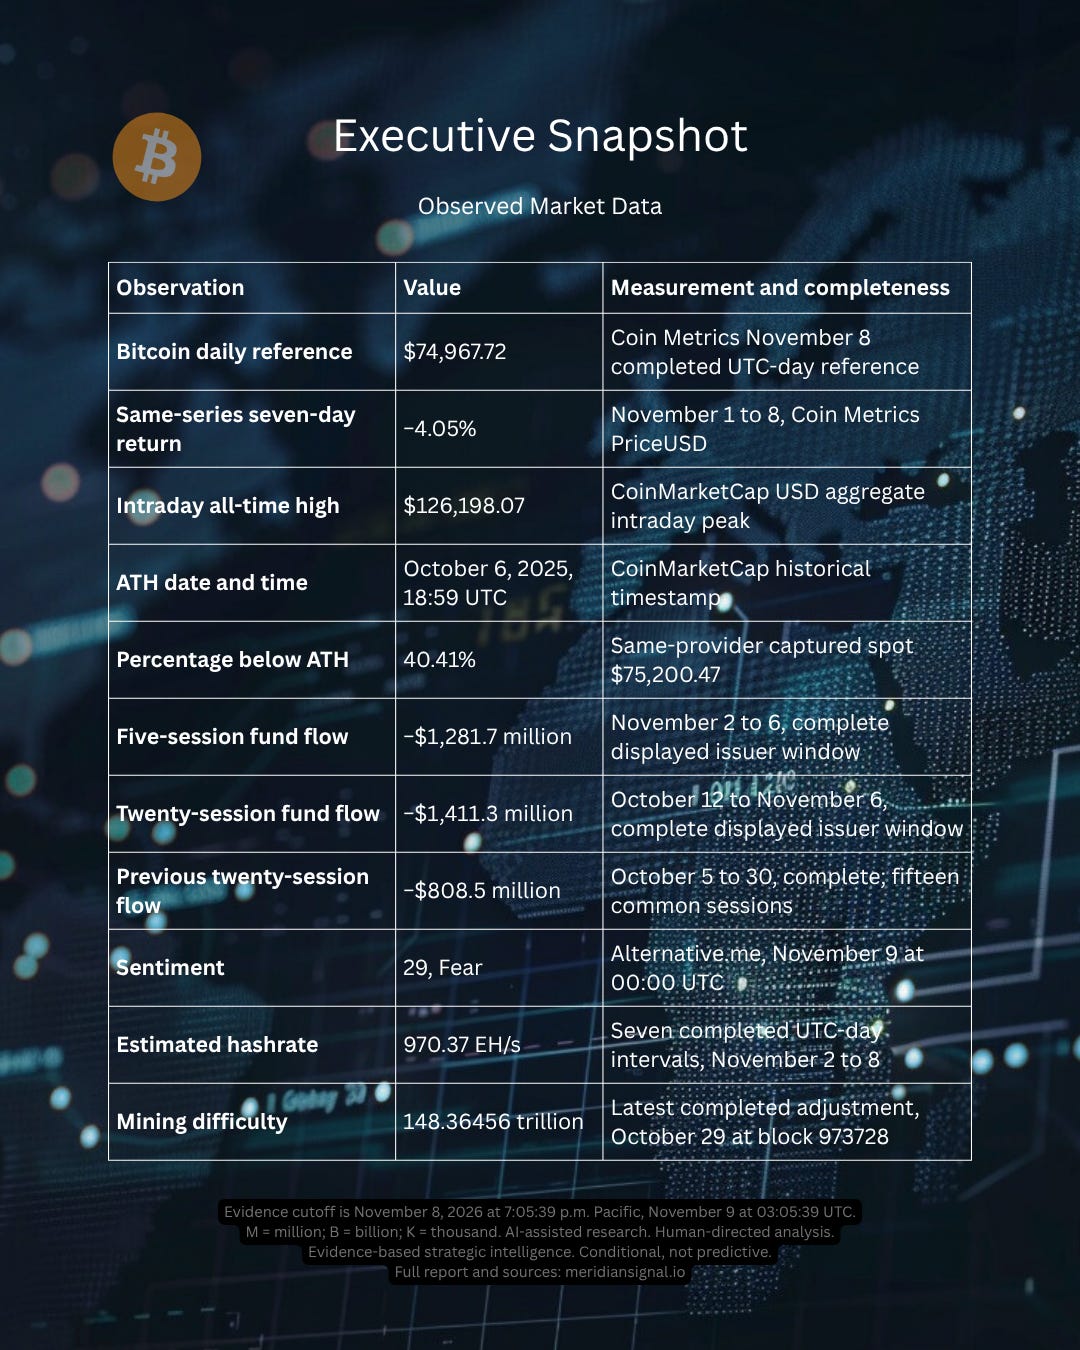
EH/s means exahashes per second. The weekly return uses one daily series and one retrieval vintage. The ATH comparison uses CoinMarketCap’s separate aggregate spot and intraday peak. Fund amounts are net flows in U.S. dollars. Complete means that all displayed issuer observations are present in the specified window, subject to subsequent provider revision.
Last issue’s test
The preceding published report, WCIR 033, retained the $80,000 and $76,000 thresholds and three-completed-day duration. Its full recovery test also required a positive November 2 to 6 fund week and a positive, non-deteriorating twenty-session window.
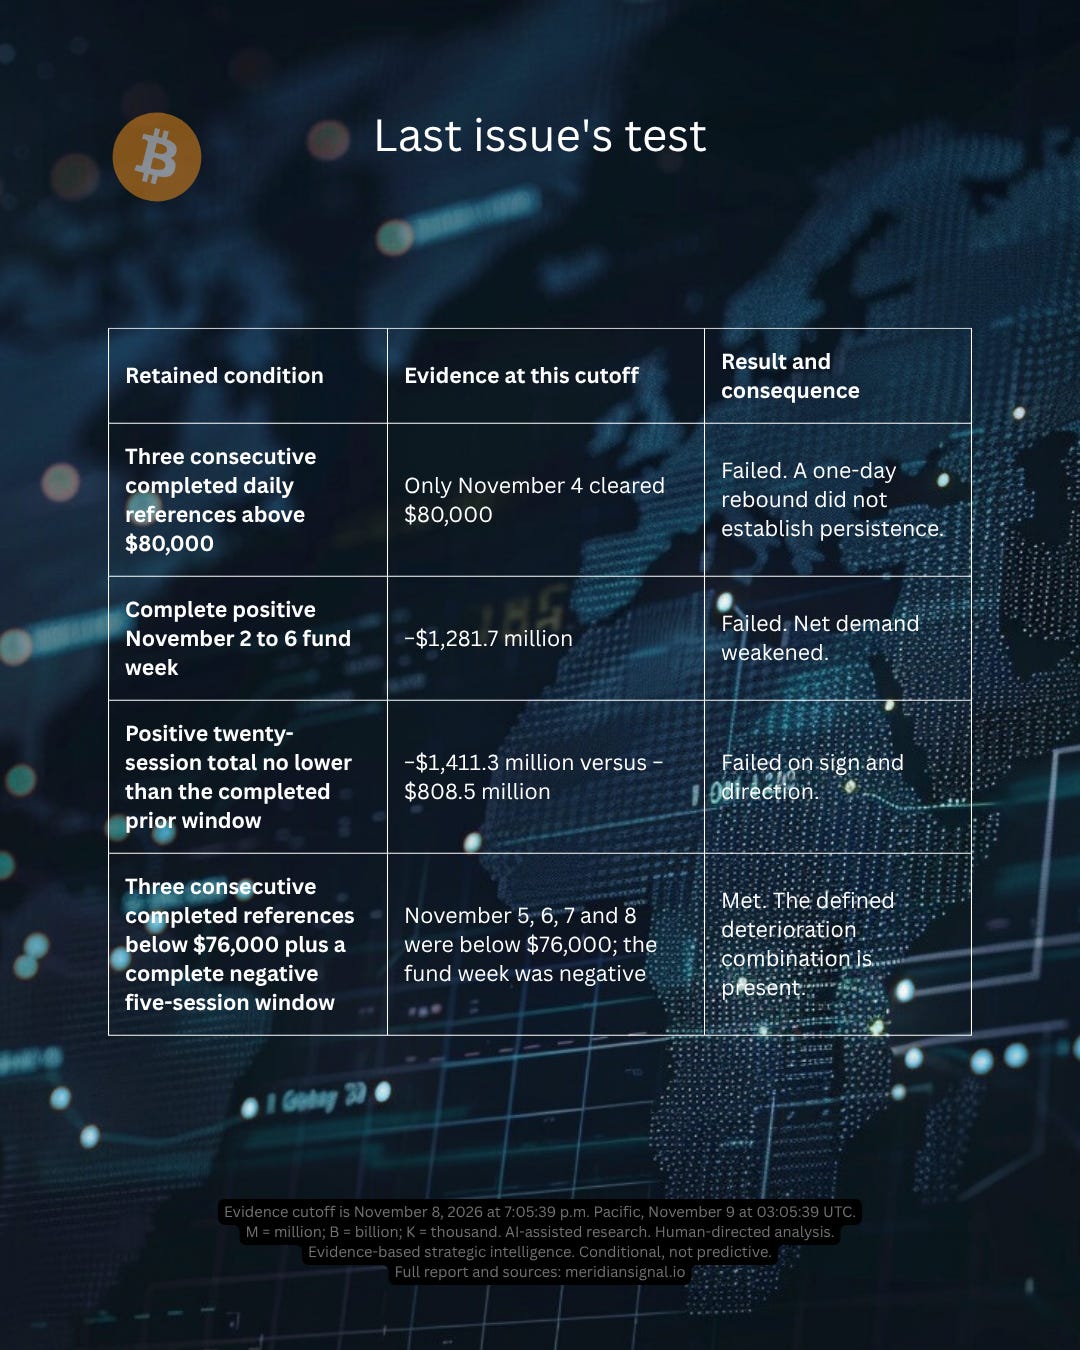
These are qualitative research conditions with disclosed observation rules. Their fulfillment supplies no calibrated crash probability, price target or instruction to transact.
Price structure
Coin Metrics’ completed daily USD references were $76,680.75, $77,655.74, $80,487.59, $75,803.13, $75,826.53, $75,724.41 and $74,967.72 from Monday through Sunday. The final reading was 4.05% below November 1’s $78,135.08.
Wednesday supplied the strongest rebound within the weekly daily series, followed immediately by a drop below the lower research threshold. The final four observations remained below that threshold. This duration distinguishes the current result from a brief intraday breach.
The week’s highest and lowest daily references were $80,487.59 and $74,967.72. They are daily-reference extrema, rather than the week’s highest and lowest traded prices. The analysis does not splice exchange intraday observations into the daily return series.
Institutional fund demand
Farside’s complete daily totals were −$398.6 million, −$115.6 million, +$74.6 million, −$430.2 million and −$411.9 million. Wednesday was the only net inflow session. Thursday and Friday together accounted for $842.1 million of withdrawals.
IBIT recorded withdrawals on all five days, totaling $1,209.5 million. FBTC finished positive at $93.1 million, despite its $199.9 million Thursday withdrawal. BITB added $16.6 million. The aggregate weakness therefore coexisted with buying in selected funds. IBIT’s withdrawals exceeded the net aggregate loss attributable to most other individual funds, making concentration important when interpreting the week.
The twenty-session total fell by $602.8 million, from −$808.5 million for October 5 to 30 to −$1,411.3 million for October 12 to November 6. Fifteen sessions overlap. The entering five-session loss of $1,281.7 million replaced the October 5 to 9 loss of $678.9 million.
The November 2 to 6 loss was larger than the preceding week’s $202.4 million loss. Both windows are complete in the captured table. Fund flows cover the listed products and cannot identify all Bitcoin demand. A comparable exchange-supply series was not established, limiting any conclusion about exchange balances, holder intent or the destination of withdrawn coins.
ATH context
CoinMarketCap continued to report an aggregate intraday high of $126,198.06960343386 on October 6, 2025 at 18:59 UTC. Its captured spot was $75,200.46851959871. The descriptive calculation, 100 × (ATH − spot) / ATH, gives 40.41% below ATH.
CoinGecko independently reports $126,080 on October 6, 2025 at 10:57:42 UTC. These providers use different aggregate constructions and sampling conventions. Their values corroborate the date and scale while retaining different peak observations. No new high was shown in either capture.
The prior CoinMarketCap snapshot stood 37.93% below its high. The wider distance gives historical context, without identifying fair value, a bottom or a recovery timetable. The same-series weekly decline remains the separate Coin Metrics calculation.
Macro and liquidity
The Federal Reserve’s November 6 H.15 release puts the five-year inflation-indexed Treasury yield at 2.33% on November 5, compared with 2.31% on October 29 in WCIR 033. That is a two-basis-point issue-to-issue increase. The current release also shows 2.25% on October 30, making the October 30 to November 5 increase eight basis points. Neither comparison is a completed Friday-to-Friday week. The five-year maturity is retained for continuity.
The November 5 H.4.1 release shows weekly-average reserve balances of $2,930.088 billion for the week ended November 4, up $36.318 billion from $2,893.770 billion. The Treasury General Account averaged $957.175 billion, down $42.552 billion from $999.727 billion. These are comparable averages of daily figures. The separate Wednesday reserve balance of $2,962.804 billion and Treasury balance of $936.248 billion are not substituted into the weekly-average comparison.
More reserves and lower Treasury cash make these selected U.S. liquidity observations more supportive than last week. The increase in the five-year real yield points the other way. The combination does not establish a global liquidity expansion or explain the week’s Bitcoin moves by itself.
DefiLlama’s sum of USD-valued circulating stablecoin balances fell 1.54%, from $299.402 billion at November 2 00:00 UTC to $294.806 billion at November 9 00:00 UTC, using the same current retrieval. The November 2 baseline has been revised from the $299.553 billion captured in WCIR 033, a reduction of about $151 million. The current comparison uses the revised baseline explicitly. Native peg units are not added together. Valuation, exchange rates and provider coverage can affect the aggregate, so the decline cannot be assigned entirely to redemptions or Bitcoin demand.
Corporate ownership and financing
Strategy’s November 2 SEC filing reports 811 BTC purchased for $65.5 million during October 26 to November 1, financed through common-share sale proceeds. It reports 849,327 BTC held at November 1, compared with the previously reported 848,517. Those reported holdings differ by 810 BTC, one less than the stated purchase quantity. The filing does not explain that reconciliation difference in the captured update. Both reported figures are preserved without inventing an adjustment.
The disclosure was released during this week but its acquisition period ended before the current price week. It does not establish buying during November 2 to 8.
The company allocated another $98.5 million of common-share proceeds to USD Cash, used $208.2 million of USD Cash for STRC preferred-share repurchases and paid $43.4 million of preferred dividends from its separate USD Reserve. Ending balances were $132.7 million of USD Cash and $4.79 billion in the reserve. The reserve is intended to support financing obligations. Preferred-share repurchases and dividends compete for resources even while Bitcoin purchases continue.
Corporate buying is a counterweight to the negative fund evidence, but one company’s prior-period purchases neither establish broad current demand nor a price floor.
Network operation and miner economics
Mempool’s seven completed intervals average 970.37 EH/s, down approximately 9.24% from the preceding seven-day mean of 1,069.20 EH/s. The November 9 00:00 UTC endpoint represents the completed November 8 day. This interval-end mapping is retained throughout.
Difficulty remains 148.36456 trillion, following the October 29 adjustment. The current estimated hashrate and the latest completed difficulty adjustment describe different periods. A lower seven-day estimate does not by itself establish a lasting reduction in deployed equipment.
Hashrate Index displayed $32.22 per petahash per day, compared with $33.37 in the prior snapshot. This is expected mining revenue per unit of computation. Electricity costs, fleet efficiency, fees and financing determine miner profitability. The decline adds pressure to that revenue measure while the high difficulty setting remains in force.
Network operation, mining economics and Bitcoin’s market price are evaluated separately. Computation alone cannot validate decentralization, durable-holder behavior or a price floor.
Custody and protocol risk
Coverage correction, November 8. WCIR 033’s custody discussion did not incorporate Binance’s October 29 incident. The present report adds that missing context and distinguishes it from subsequent disclosures.
In its November 3 account, Binance estimates $6.34 billion in affected digital assets, with $2.85 billion frozen or intercepted, subject to reconciliation and market prices. The company reports unauthorized access to its wallet-signing service, including a transfer of 18,270 BTC. The aggregate incident estimate covers multiple assets. Binance also says it replenished 98% of impacted token assets as of October 31, with less-liquid assets still being acquired. That retrospective statement was disclosed November 3 and is not treated as evidence available at the prior cutoff.
The November 6 recovery announcement describes further phased withdrawal reopening, conditional on asset-specific checks. Replenishment, reserve verification and restoration of withdrawals address different questions. Company statements and proof-of-reserves snapshots do not establish a completed independent audit, universal withdrawal availability or final remediation.
The Bitcoin Core advisory index supplies scoped software evidence. The older Bitquery hardware-custody investigation retains its October 16 measurement date. Neither an exchange’s compromised signing infrastructure nor a hardware-custody incident establishes failure of Bitcoin’s consensus rules. Comprehensive incident coverage and independent confirmation of all remediation remain incomplete.
Changes, continuities and contrary evidence
The material change is fulfillment of the retained deterioration combination. The negative fund week deepened, the twenty-session loss increased, and four consecutive daily prices crossed the lower threshold. Sentiment fell from 37 to 29, both within Fear, but the index partly reflects market inputs and is not an independent vote on fund demand.
The strongest contrary evidence is the recovery in weekly-average reserves, the decline in Treasury cash, positive weekly buying in FBTC and BITB, and Strategy’s disclosed prior-period purchase. These temper a uniformly adverse interpretation. They did not deliver the three required recovery conditions.
The threshold levels, duration, daily price provider, flow windows and hashrate mapping remain consistent. Stablecoin historical values were revised by the provider and are identified above. Custody coverage is broader because material missing context and newly released disclosures have been added.
Horizon Posture
Long term. Constructive thesis with elevated custody concern. Network operation supports continued consideration of Bitcoin as digital collateral, while the exchange incident raises the burden of evidence for custody resilience. Recurring use, independently substantiated remediation and sustainable financing would strengthen the thesis. Persistent protocol impairment, broader verified custody failures or materially constrained access would weaken it. Current observations do not establish either a permanent impairment or a durable price bottom.
Medium term. Deterioration confirmed under the retained test. Persistent sub-$76,000 daily references and complete net fund withdrawals now meet the specified combination. Recovery requires three completed daily references above $80,000, a complete positive five-session fund week and a positive twenty-session total no lower than its completed predecessor. The current negative $1,411.3 million longer window makes a modest weekly inflow insufficient.
Tactical. Defensive and evidence-led. A one-day rebound failed to persist. The next evidence to watch is the duration of any price recovery, the breadth and completeness of fund demand, and verified withdrawal availability. Lower sentiment alone supplies no reversal signal. A renewed sub-$76,000 sequence with another complete negative fund week would reinforce the current assessment.
Conditional paths and next tests
The next standard five-session fund window is November 9 to 13. A constructive recovery assessment requires all three conditions together.
Three consecutive completed Coin Metrics daily references above $80,000.
A complete positive November 9 to 13 fund window.
A positive twenty-session total no lower than the completed predecessor, currently −$1,411.3 million, with revisions identified. Positivity is separately required even when the predecessor is negative.
An intermediate rebound can occur while that full recovery test remains incomplete. A price rise above $76,000 alone does not meet the constructive test. Missing issuer observations would leave the affected demand test unresolved.
The downside combination remains three consecutive completed daily references below $76,000 together with a complete negative five-session fund window. The present week meets it. These conditions describe evidence paths, not probabilities or validated trading levels.
Meridian strategic conclusion
The weakness now has both duration and fund-demand confirmation. Improved U.S. reserve measures and selective fund buying are meaningful counterweights, but the twenty-session window continues to deteriorate. A recovery upgrade therefore requires sustained prices above $80,000, a complete positive five-session fund window and a positive, non-deteriorating twenty-session total.
The most consequential distinction this week is between a temporary rebound and that complete recovery combination. Custody restoration also needs its own evidence, independently of any price bounce.
Sources
Coin Metrics · CoinMarketCap · CoinGecko · Farside Investors · Federal Reserve H.15 · Federal Reserve H.4.1 · DefiLlama · Strategy SEC filing · Mempool · Hashrate Index · Bitcoin Core · Bitquery · Binance initial findings · Binance November 6 update · Alternative.me
Editorial Note
The Bitcoin Evidence-Led Series distinguishes sourced observations, descriptive calculations and Meridian’s qualitative assessments. Each edition reflects the evidence available at its stated cutoff; source data may subsequently be revised.
Meridian Signal uses artificial intelligence to assist source discovery, comparison, drafting and arithmetic verification. Final review and editorial responsibility rest with Meridian Signal. Material limitations are disclosed, and corrections to prior reporting are identified explicitly.
Research Disclosure
This report provides general informational and educational research, not personalized investment, legal or tax advice or an instruction to transact. Bitcoin is volatile, and loss of principal is possible. Assessments involve uncertainty; conditions and scenarios do not guarantee outcomes.
Meridian Signal
Bold clarity at the right time.
Independent strategic intelligence on capital regimes, digital infrastructure and systemic risk.
AI-assisted. Human-directed.
Evidence-based strategic intelligence. Conditional, not predictive.
Questions or corrections: contact@meridiansignal.io