

Weekly Conviction Intelligence Report | Evidence-Led Series | Week 36
Bitcoin regained $80,000 as fund demand persisted. Macro conditions and uneven buying still make confirmation the central test.
Evidence cutoff: September 6, 2026 at 9:20:38 p.m. Pacific / September 7 at 04:20:38 UTC.
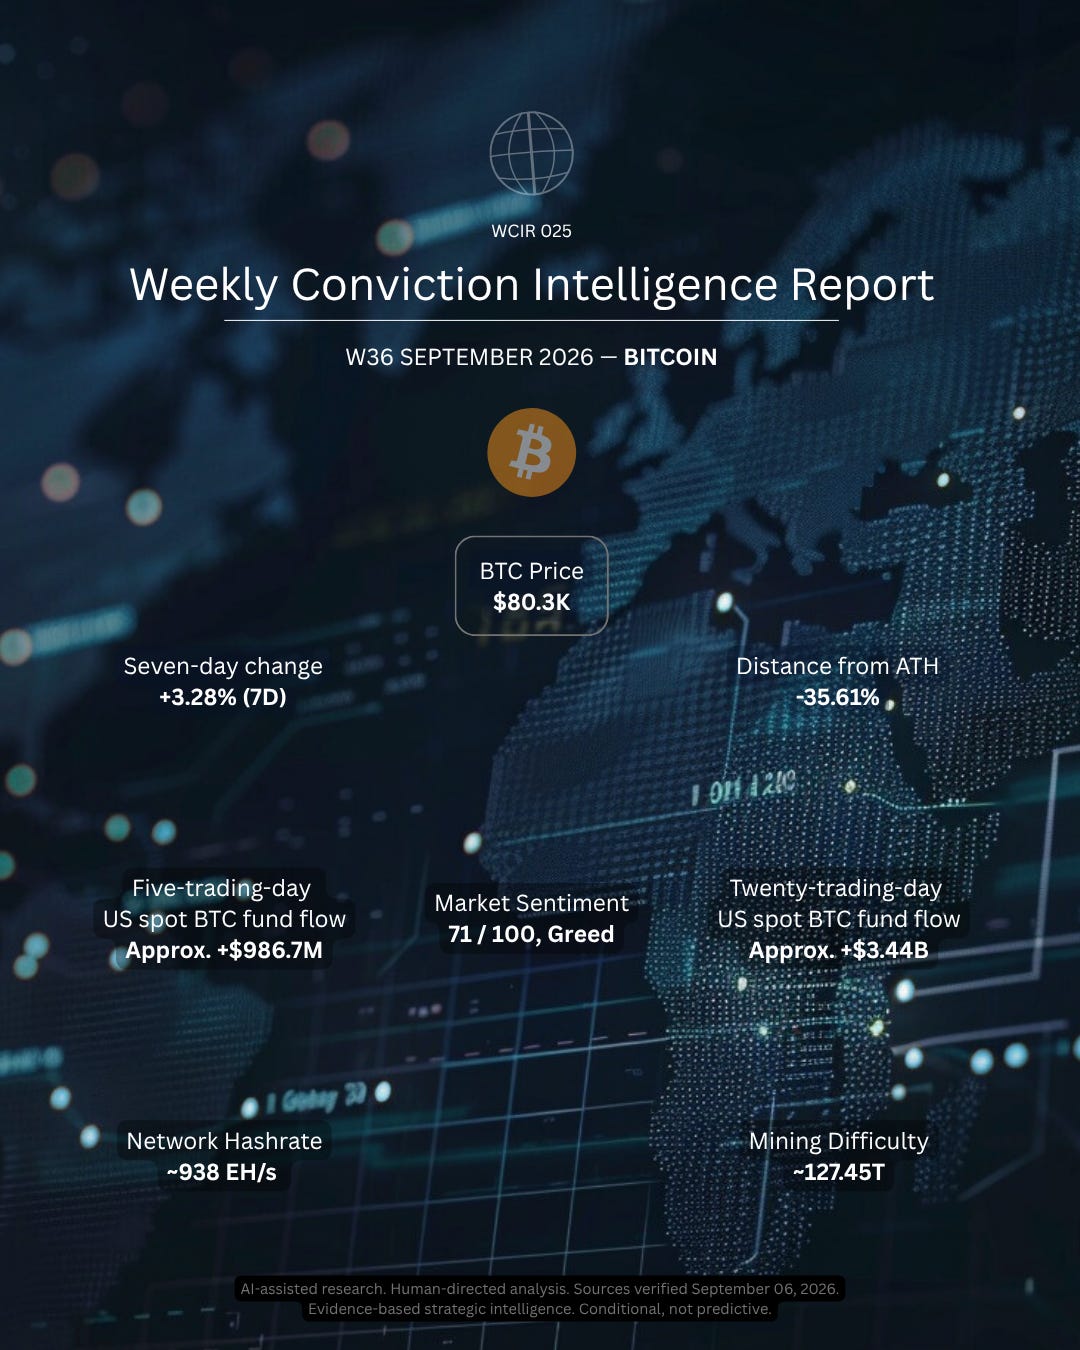
Executive assessment
Bitcoin made a meaningful recovery this week. The daily reference finished above the $80,000 observation level carried forward from WCIR 024, and the five-session fund-flow total remained positive. That combination strengthens the immediate recovery case. It does not yet demonstrate that demand has become durable across sessions or that the broader environment has shifted decisively in Bitcoin’s favor.
Our assessment is unchanged in its degree of caution: Price recovered above $80,000 while weekly fund inflows remained positive; tactical posture constructive but confirmation-dependent. The opportunity in the evidence is improving price acceptance. The uncertainty is whether that improvement survives less concentrated buying and a macro backdrop that still includes positive real yields.
This issue restores the wider lens: market demand, financial conditions, corporate financing, ownership risks, and the conditions that would change the interpretation. An unavailable network observation remains visible rather than becoming a reason to abandon the rest of the analysis.
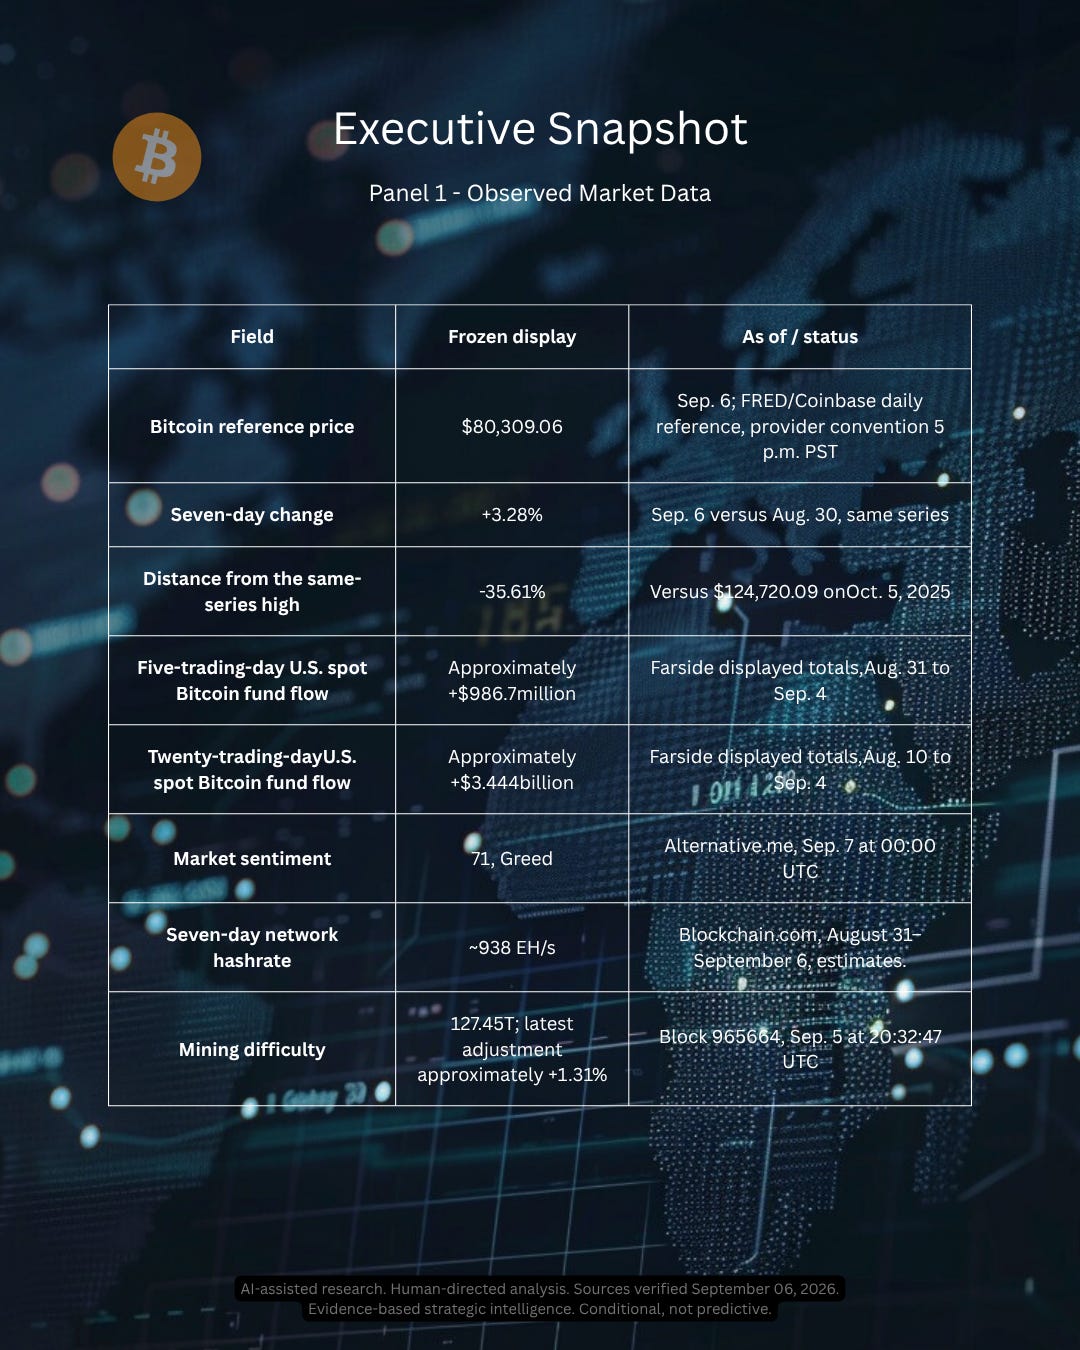
Executive Snapshot
Panel 1: Observed Market Data
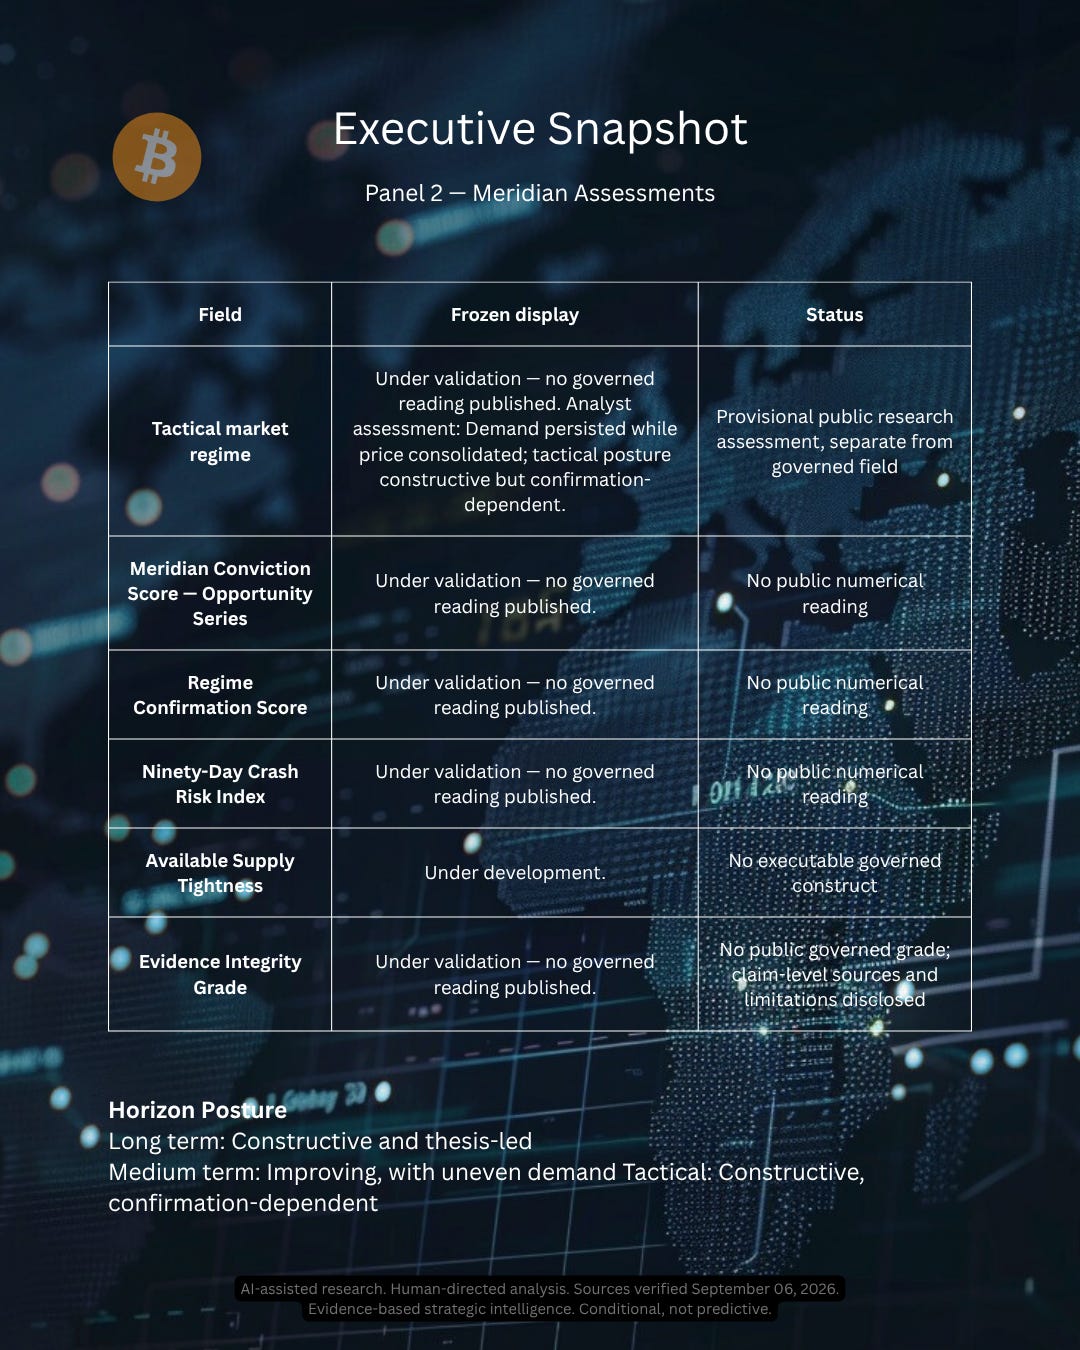
Panel 2: Meridian Assessments
Three material changes
1. Price reclaimed a useful reference level. The September 6 daily reference was $80,309.06, compared with $77,757.98 on August 30. The path matters: September 3 was above $81,000, September 4–5 returned below $80,000, and September 6 regained it. The latest reading is therefore a recovery signal with a recent failed hold already in view. It is not sufficient evidence of sustained acceptance. FRED/Coinbase
2. Weekly fund demand increased modestly, with an uneven distribution. The five-session total of +$986.7 million exceeded WCIR 024’s +$924.5 million. September 3 supplied +$730.8 million, while September 1 had a -$236.5 million outflow. The weekly sign alone hides that variation. Our interpretation favors a test of persistence across subsequent sessions rather than extrapolating the strongest day. Farside Investors
3. Sentiment became warmer. Alternative.me rose from the prior issue’s dated reading of 62 to 71, both classified as Greed. This is consistent with improving confidence, but confidence is not independent confirmation of future demand. If sentiment strengthens while price repeatedly fails to hold its recovery, that divergence would weaken the tactical case. Alternative.me
Three important continuities
The longer recovery is still incomplete. The same-series drawdown remains substantial. A positive week changes the immediate trajectory without resolving the distance from the prior high. The long-term thesis should not be strengthened merely because the latest week was green.
The wider fund-flow window remains positive. The twenty-session total supports continuity of demand over a broader interval. However, these flows cover the observed U.S. spot-fund channel, not all global Bitcoin purchases, and they do not reveal each investor’s holding horizon. Positive totals can coexist with selling elsewhere.
Confirmation remains conditional. We retain the distinction between observable market improvement and a governed regime reading. Proprietary fields remain withheld, and no newly published score is implied by a more constructive analyst interpretation. This methodological continuity should preserve clarity without reducing the depth of public research.
Macro and liquidity: supportive conditions, incomplete transmission
The latest Adjusted National Financial Conditions Index observation was -0.582 for August 28, released September 2. The same retrieved vintage reports -0.585 for August 21: a small move toward less negative conditions. Negative readings indicate looser-than-average adjusted financial conditions, but this broad measure does not establish a contemporaneous Bitcoin liquidity impulse. The prior issue used an earlier vintage; mixing that earlier value with this revision would misstate the weekly comparison. FRED ANFCI
The five-year Treasury inflation-indexed yield was 2.15% on September 3, the latest observation in the retrieved release. Positive real yields remain a competing return available in the financial system. For a non-yielding asset such as Bitcoin, our inference is that sustained demand matters more when the real-yield backdrop provides that alternative. This is a transmission argument, not a claim that one yield explains this week’s price movement. FRED DFII5
Federal Reserve total assets were $6.737204 trillion on September 2, compared with $6.730912 trillion on August 26. That increase is an observed balance-sheet change. It is not enough to label the week a broad liquidity expansion: this issue does not combine Treasury cash, reverse repos, bank reserves, offshore conditions, and other central banks into a comprehensive net-liquidity measure. FRED WALCL
Initial unemployment claims were 206,000 for the week ending August 29; their four-week average was 207,250, both released September 3. These observations provide labor-market context, not a policy forecast. A single weekly release cannot settle whether growth will support risk appetite or whether deterioration will eventually dominate it. FRED ICSA, FRED IC4WSA
Taken together, the reviewed macro evidence does not justify either an automatic tailwind or an imminent-breakdown narrative. The market still has to demonstrate that available financial capacity translates into persistent Bitcoin demand. Release lags also mean these observations describe different periods; they are not simultaneous measurements at Sunday night’s cutoff.
Corporate ownership, custody, and protocol context
New disclosure; earlier transaction period. Strategy’s August 31 filing reported the purchase of 4,603 BTC for $369.7 million during August 24–30, taking reported holdings to 845,050 BTC. Common-stock issuance funded those purchases. The same filing also allocated issuance proceeds to preferred-stock dividends, preferred repurchases, and cash. These transactions belong to the preceding week even though the disclosure entered this week’s information set. Strategy Form 8-K
The analytical implication is that corporate accumulation sits inside a financing structure. Access to equity capital can support purchases, while competing obligations affect how proceeds are used. This filing cannot establish sector-wide buying or guarantee future purchases. Corporate exposure also differs from directly held Bitcoin because the security introduces financing and issuer-specific risks.
Carry-forward custody risk. Coinkite’s August 20 security notice concerned a seed-generation vulnerability and explained that the incident was not remote compromise of the hardware itself. The notice distinguishes fixing firmware from resolving exposure associated with an affected existing seed. It remains relevant ownership context, but we are not presenting it as a new event this reporting week or estimating current losses. Coinkite security notice
The broader point is that a constructive market thesis does not remove custody risk. A price dashboard cannot attest to the security of a holder’s keys, device setup, intermediary, or recovery process. Research should keep those layers visible rather than treating institutional participation as a blanket security endorsement.
Protocol status, with a defined limit. The reviewed BIP 110 registry entry is marked Closed. That status is not proof of network adoption or evidence that every proposed rule became active. We treat it as registry context, not a newly verified weekly transition or a comprehensive assessment of Bitcoin implementation security. Bitcoin BIPs repository
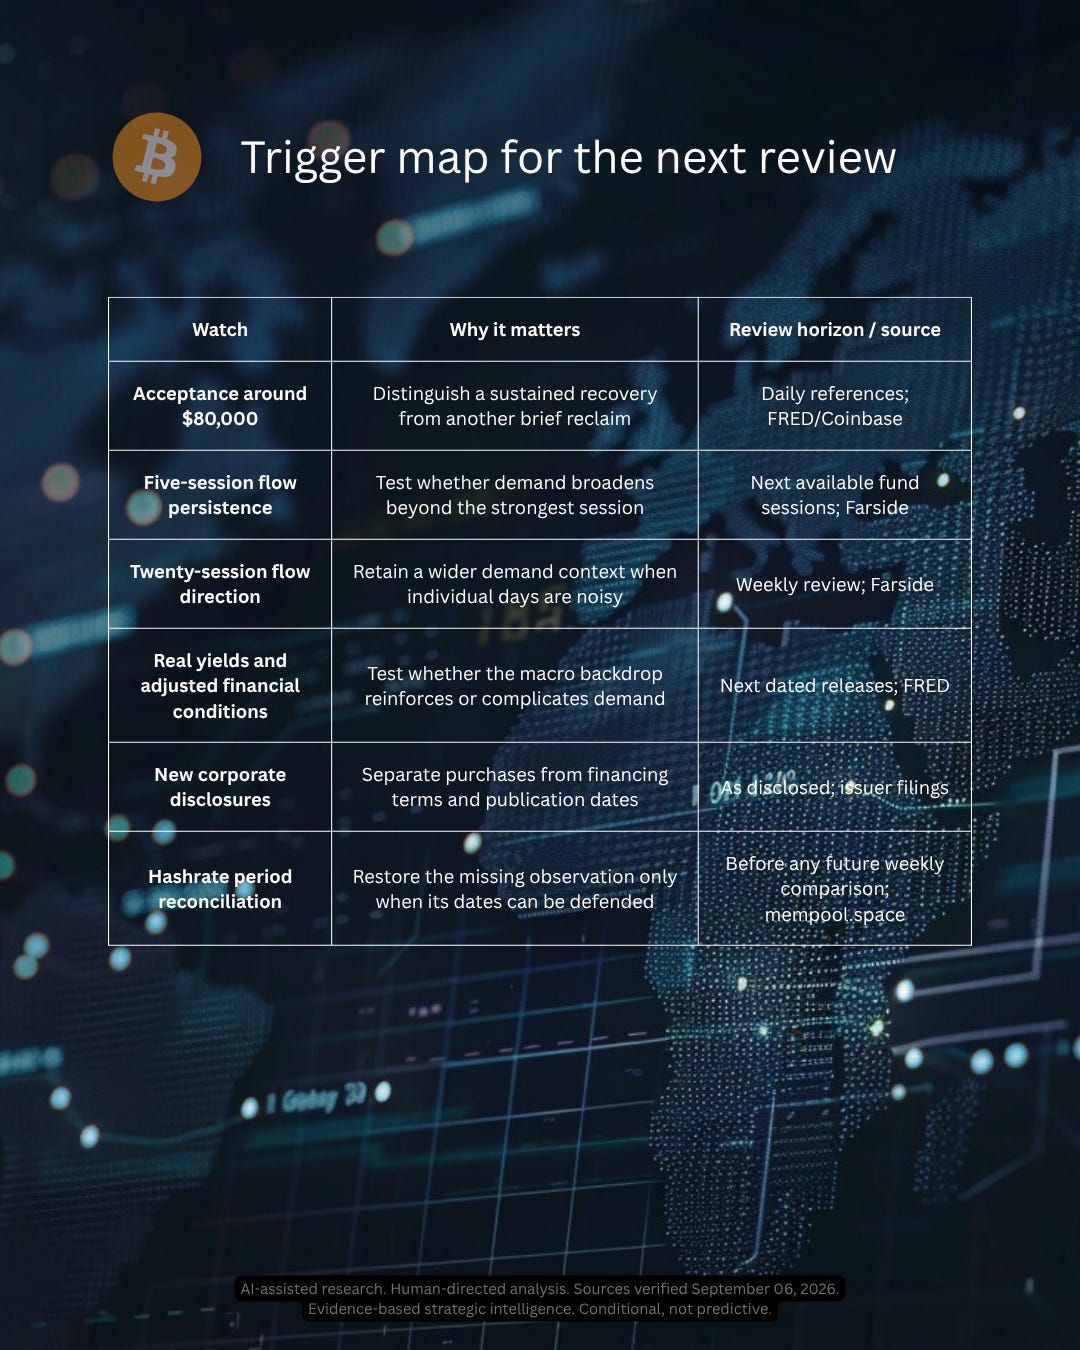
Separately, the difficulty observation is available, but the seven-day hashrate estimate is not admitted while its period labels remain unresolved. Difficulty and estimated hashrate answer different questions. We therefore make no weekly hashrate-trend claim or network-wide security all-clear. mempool.space
What is happening beneath the headline
Our synthesis is that price has recovered faster than the evidence has established consistency. A strong flow session and a reclaimed price reference are meaningful together, but they leave open whether the move reflects a durable broadening of demand or a recovery vulnerable to interruption. The warmer sentiment reading increases the value of watching that distinction.
The bullish interpretation is that recent buying is beginning to overcome available selling and that subsequent sessions will show firmer price acceptance. The contrary interpretation is that a concentrated burst has improved the weekly totals without changing the market’s ability to hold higher levels. The reviewed evidence does not resolve that contest.
Macro context adds another condition rather than supplying the answer. Broadly loose adjusted financial conditions can coexist with positive real yields, and corporate purchases can coexist with financing obligations. Neither observation automatically cancels the other. The next report should judge whether the market converts this combination into persistent demand and a more stable recovery.
Conditional paths and horizon posture
Bull: Repeated daily references above $80,000, with positive five-session flows supported across multiple sessions.
Evidence that would challenge it: Repeated loss of $80,000 alongside sustained fund outflows
Base: Price moves around $80,000 while twenty-session flows remain positive and daily demand stays uneven.
Evidence that would challenge it: Sustained upside confirmation, or a break below $76,000 accompanied by outflows
Bear: Daily references below $76,000 alongside negative five-session flows.
Evidence that would challenge it: Reclaiming $80,000 with renewed multi-session inflows
The $80,000 and $76,000 markers are analyst references carried forward from WCIR 024. They are neither model targets nor guaranteed support or resistance. These paths organize observation over the coming sessions and weeks; they have no assigned probabilities, price promises, or instructions to transact.
Long term: Constructive and thesis-led.
Medium term: Improving, with uneven demand.
Tactical: Constructive, confirmation-dependent.
The horizons need not move together. A short-lived failure to hold the recovery would matter tactically before it established anything decisive about the long-term thesis. Conversely, a strong week does not by itself prove that structural ownership, liquidity, or adoption conditions have improved permanently.
Trigger map for the next review
Contrary evidence and limits
The strongest challenge to our constructive interpretation is the recent inability to remain continuously above $80,000 despite a positive flow week. Demand concentration is a second caution. A weekly sum can improve while the market remains dependent on a small number of strong sessions.
This issue does not provide verified derivatives funding, open interest, options positioning, exchange-wide market depth, or beneficial-owner attribution. Without those inputs, we cannot identify how much leverage supported the recovery, assess execution capacity across venues, or attribute observed demand to stable long-horizon holders. These subjects are unverified here, not declared unchanged.
The unresolved hashrate field narrows the network comparison. Macro series are lagged and revisable, while fund-flow totals are aggregator observations. These limits constrain the conclusions; they do not justify substituting invented precision or treating every reviewed indicator as independent confirmation.
Strategic conclusion
WCIR 025 shows a recovery with evidence behind it and an unfinished confirmation process. The price reference improved, the broader fund-flow window stayed positive, and confidence warmed. Those observations support continued attention to the recovery. Their combination does not yet justify treating it as a settled change in regime.
The central question for the next issue is whether improved price acceptance and repeated demand reinforce each other. If they do, the constructive interpretation gains substance. If price again loses its reference levels while flows deteriorate, the reading should weaken promptly rather than being defended by the long-term thesis.
Consistency means preserving that chain of reasoning each week: what changed, what remained intact, what evidence argues against the preferred interpretation, and what would change our mind. A fuller report should make those judgments easier to audit, without suggesting that more words create more certainty.
Methodology and principal sources
Price changes use the FRED-distributed Coinbase daily reference, whose provider convention is 5 p.m. PST; it is not an executable cutoff-time quote. The high comparison uses retrieved same-series history. Fund flows sum Farside’s displayed Total column over five and twenty sessions; rounded aggregator totals may be revised. Sentiment and mining observations retain their third-party definitions.
The cutoff is the information boundary, not the measurement time of every series. Macro observations retain their dates and release lags; comparisons use the retrieved vintage. Corporate disclosure dates are distinguished from transaction periods. Carry-forward security context is labeled explicitly. Principal sources are linked at the claims they support; the accompanying source map records dates and limitations. Qualitative scenarios, reference levels, and horizon posture are analyst judgments, not governed classifications or probabilities.
Editorial Note
The Bitcoin Weekly Conviction Intelligence Report is a strategic intelligence publication by Meridian Signal designed to evaluate Bitcoin through the lenses of market structure, institutional capital flows, liquidity conditions, supply dynamics, network security, and evolving risk.
Its purpose is not to predict short-term price movements or provide investment recommendations. It is designed to assess the quality of Bitcoin’s current structural position, identify meaningful changes in market conditions, and reduce uncertainty for long-term strategic decision-making.
Source-attributed observations, Meridian analyst assessments, and governed proprietary indicators are treated as separate forms of intelligence. Analyst assessments, qualitative scenarios, and horizon-specific posture represent human-directed judgments based on the evidence available at the stated cutoff. Governed numerical readings are published only after their data, methodology, validation, and activation requirements have been satisfied.
All assessments reflect the information available at the time of publication and may change as new evidence emerges.
Meridian Signal remains committed to evaluating structure over price, conditional paths over predictions, conviction over emotion, and signal over noise.
Research Disclosure
Meridian Signal uses artificial intelligence-assisted systems to accelerate public-source discovery, data comparison, research organization, arithmetic verification, and analytical synthesis. Artificial intelligence outputs are not treated as authoritative by default.
Material claims are evaluated against available sources, and all interpretations, strategic assessments, and editorial conclusions remain under institutional human direction and review. Meridian Signal retains final human editorial responsibility. Artificial intelligence has no authority to approve, publish, trade, or activate a governed Meridian indicator.
Proprietary formulas, weights, normalization rules, internal thresholds, private calculations, and calculation mechanics are not publicly disclosed. The absence of a governed reading does not imply a neutral condition; it means the applicable evidence, validation, or activation requirements have not yet been completed.
Meridian Signal
Independent Strategic Intelligence Desk
General informational analysis only. This is not individualized financial, investment, legal, tax, accounting, or custody advice. Bitcoin is volatile, and loss of principal is possible.