

Weekly Conviction Intelligence Report | August 24, 2026
Evidence cutoff: Sunday, August 23, 2026 at 7:00 p.m. Pacific Time / Monday, August 24 at 02:00 UTC
Release type: Weekly Public Research Release — Evidence-Led Series
AI-assisted. Human-directed. Source-verified.
Executive Assessment
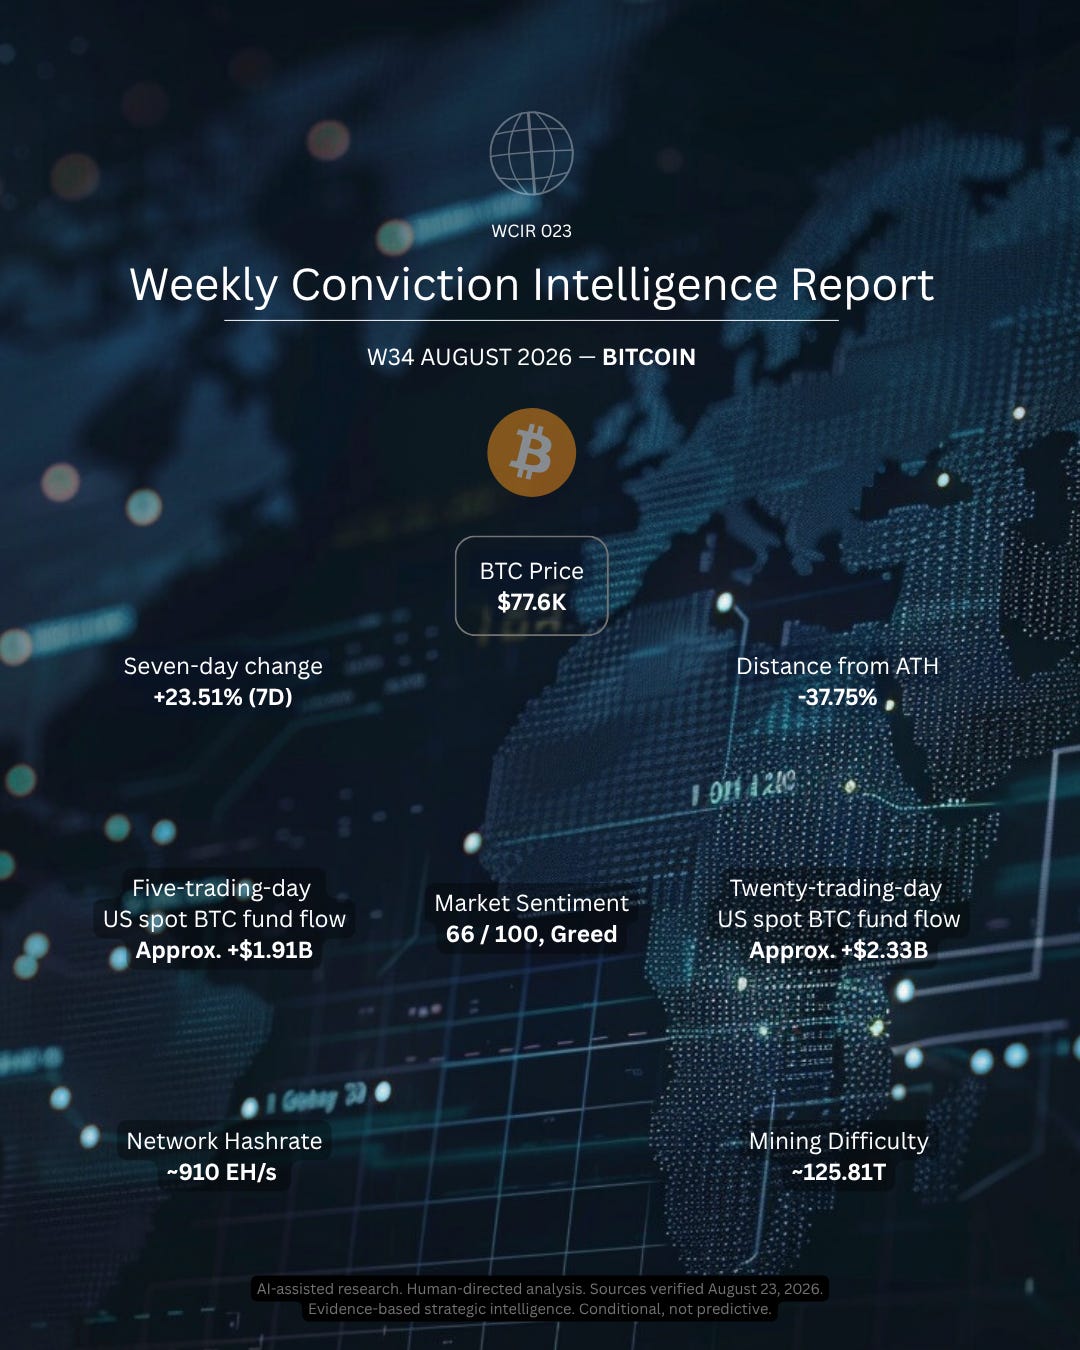
Bitcoin ended the research week with a sharp price repricing, the strongest short-window United States spot-fund demand in the current comparison window, and a rapid change in public sentiment. The evidence supports a materially improved demand picture. It does not establish that a one-week acceleration will persist.
The cutoff-available FRED/Coinbase daily reference was $77,637.69 for August 23, up 23.51% from the same series on August 16 and 37.75% below that series’ October 2025 high. FRED states that the underlying Coinbase observation uses a 5 p.m. PST convention; this is a daily reference, not an exact 02:00 UTC trade. (FRED CBBTCUSD)
The week’s clearest confirmation came from United States spot Bitcoin fund flows. Farside’s displayed totals for August 17–21 summed to approximately +$1.918 billion, reversing the prior week’s approximately -$385.2 million. The twenty-session sum increased to approximately +$2.336 billion. Farside is an aggregator, its table is generated in real time, and late issuer revisions remain possible; this release therefore treats the figures as approximate and uses one provider consistently. (Farside)
Sentiment changed just as quickly. Alternative.me’s August 23 00:00 UTC reading was 66, Greed, up from 31, Fear in WCIR 022. That is evidence of a broad mood shift, not a Meridian governed indicator or a trading signal. (Alternative.me API)
Network evidence remained firm. The arithmetic mean of mempool.space’s completed daily hashrate estimates for August 17–23 was approximately 910 exahashes per second, compared with approximately 897 EH/s in WCIR 022. Difficulty adjusted to 125.81 trillion, approximately -1.31%, at block 963648 on August 23 at 00:48:47 UTC. Hashrate is inferred and window-dependent; difficulty is the harder protocol-level observation. (mempool.space)
Executive Snapshot
Observed Market Data
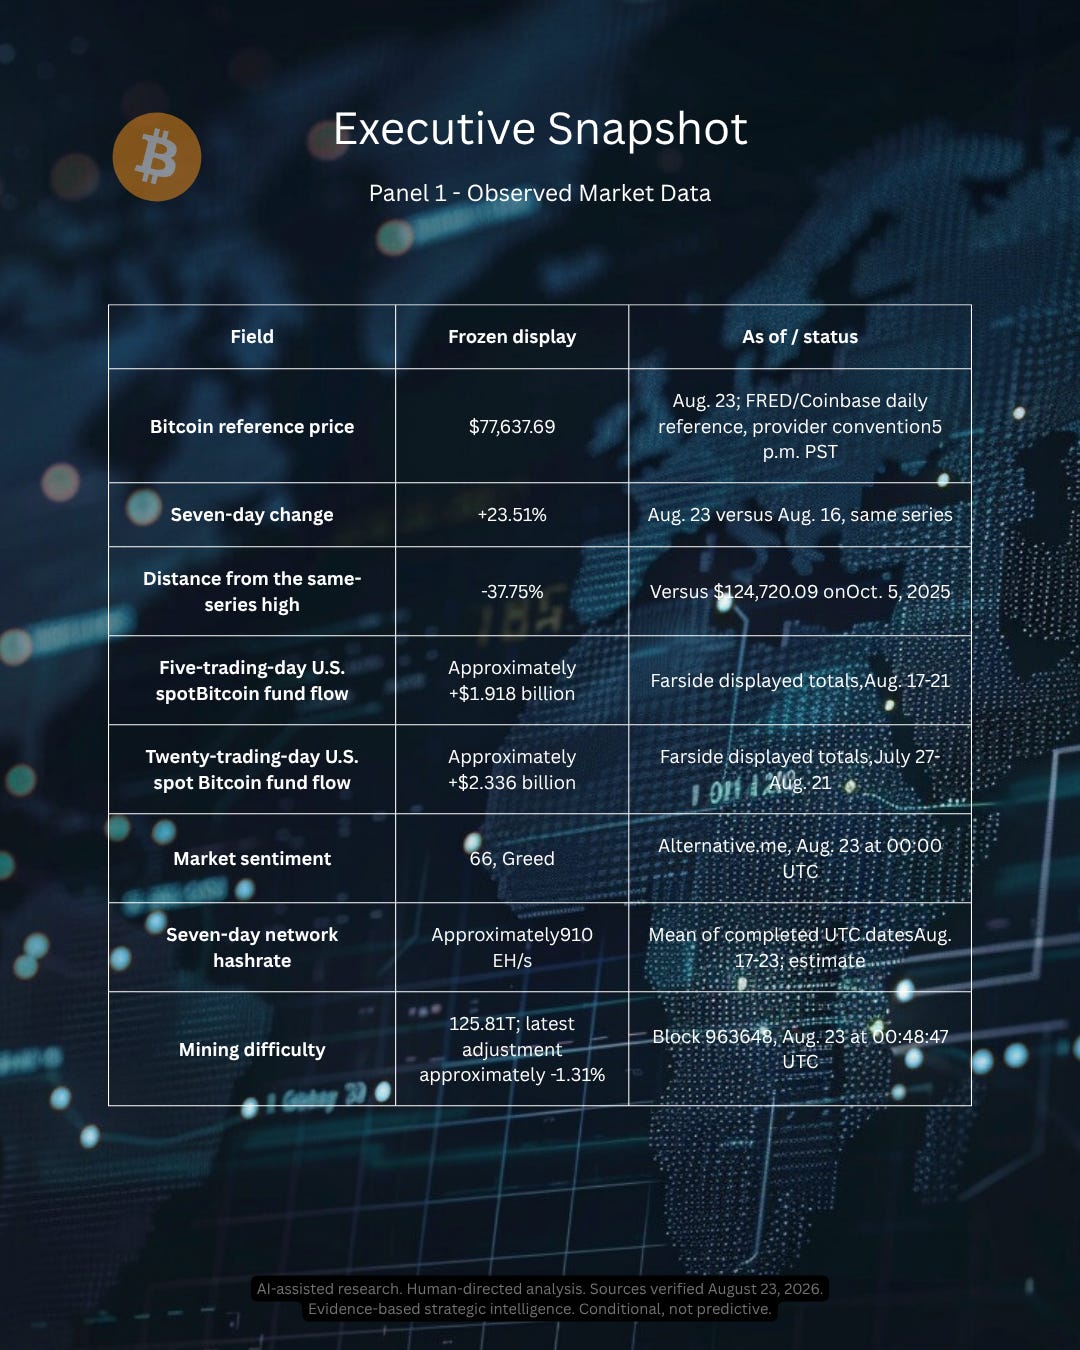
Bitcoin reference price: $77,637.69 — August 23 FRED/Coinbase daily reference; provider convention 5 p.m. PST.
Seven-day change: +23.51% — same series, August 23 versus August 16.
Distance from the all-time reference-series high: -37.75% — versus $124,720.09 on October 5, 2025.
Five-trading-day United States spot Bitcoin fund flow: approximately +$1.918 billion — Farside displayed totals, August 17–21.
Twenty-trading-day United States spot Bitcoin fund flow: approximately +$2.336 billion — Farside displayed totals, July 27–August 21.
Market sentiment: 66, Greed — Alternative.me, August 23 at 00:00 UTC.
Seven-day network hashrate: Approximately 910 EH/s — completed UTC dates August 17–23.
Mining difficulty: 125.81T; latest adjustment approximately -1.31% — block 963648, August 23 at 00:48:47 UTC.
Meridian Assessments
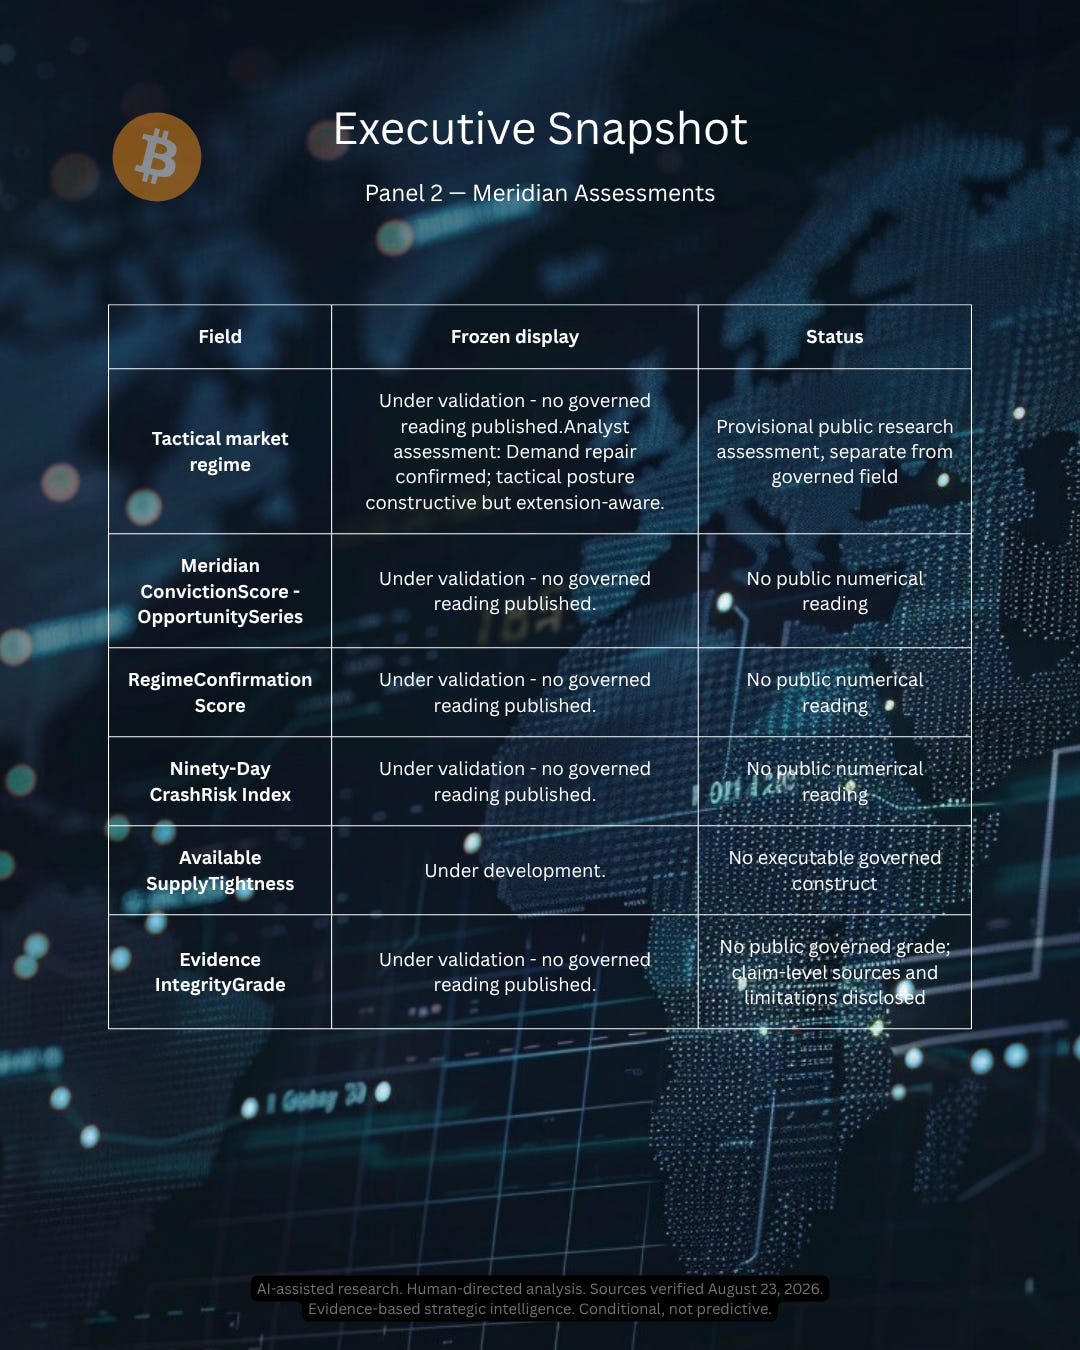
Tactical market regime: Under validation — no governed reading published. Separate analyst assessment: Demand repair confirmed; tactical posture constructive but extension-aware.
Meridian Conviction Score — Opportunity Series: Under validation — no governed reading published.
Regime Confirmation Score: Under validation — no governed reading published.
Ninety-Day Crash Risk Index: Under validation — no governed reading published.
Available Supply Tightness: Under development.
Evidence Integrity Grade: Under validation — no governed reading published. Claim-level sources and limitations are disclosed instead.
Horizon posture: Long-term constructive and thesis-led. Medium-term improving. Tactical constructive but extension-aware.
Three Material Changes Since WCIR 022
Price momentum reversed sharply. The same daily reference increased from $62,859.47 to $77,637.69. The seven-day reading moved from -3.08% to +23.51%, and the distance from the same-series high narrowed from -49.60% to -37.75%.
Fund demand became the principal confirmation. The five-session Farside sum reversed from approximately -$385.2 million to approximately +$1.918 billion. The twenty-session sum increased from approximately +$452.5 million to approximately +$2.336 billion.
Sentiment followed price. Alternative.me moved from 31, Fear to 66, Greed. The completed-date hashrate estimate also increased from approximately 897 EH/s to approximately 910 EH/s.
Three Important Non-Changes
Bitcoin remained below the reference-series high. Even after the weekly advance, the August 23 observation remained 37.75% below the October 2025 high.
Network work remained high. Difficulty stayed above 125 trillion after its latest adjustment, while the completed-date hashrate estimate remained near 910 EH/s.
Governed indicators remained unavailable. No private-shadow metric was activated, no governed value was released, and the approved unavailable-language remains in every recurring dashboard position.
Macro Backdrop: Conditions Remained Supportive, Not Unconditional
The latest cutoff-available Chicago Fed Adjusted National Financial Conditions Index was -0.587 for the week ended August 14. Negative values indicate conditions below the index’s long-run average, but this is a broad United States financial-conditions measure rather than proof of Bitcoin-specific liquidity support. (FRED ANFCI)
The five-year real Treasury yield was 2.05% on August 20. Positive real yields remain a competing return for non-yielding and duration-sensitive assets even while broader financial conditions are comparatively loose. (FRED DFII5)
Federal Reserve total assets were $6.745699 trillion on August 19, down from $6.759955 trillion one week earlier. This is a weekly balance-sheet observation, not a comprehensive liquidity index, and it should not be combined with other facilities into an unsupported score. (FRED WALCL)
Initial unemployment claims were 206,000 for the week ended August 15, while the four-week average was 204,000. The release is advance data and subject to revision. The Federal Reserve also released the minutes of its July 28–29 meeting on August 19; those minutes describe information available at the time of that meeting and do not constitute a new policy decision. (United States Department of Labor, Federal Reserve)
What Is Actually Happening
The short-term demand impulse improved decisively. Price rose, the five-session fund-flow sum turned strongly positive, and sentiment moved from Fear to Greed. These three observations justify upgrading the public analyst assessment from defensive-neutral to constructive.
The speed of the change is also the principal tactical risk. A 23.51% weekly repricing and a 35-point sentiment increase can represent genuine confirmation while also increasing the cost of chasing late momentum. The evidence supports constructive posture with extension awareness, not euphoria.
The medium-term picture is stronger than it was one week ago because the twenty-session fund-flow sum expanded materially and network work remained high. The long-term thesis remains separate from the weekly tape. Durable network security and institutional access are supportive; positive real yields, revision-prone flow data, and the distance still remaining below the prior high argue for confirmation discipline.
Regime, Risk, and Qualitative Scenarios
Bull path
Observable triggers: the same daily price series holds above $76,000; the five-session Farside sum remains positive; sentiment avoids a rapid move into Extreme Greed.
Falsifier: price closes below $72,000 while the five-session fund-flow sum turns negative.
Posture: long-term constructive; medium-term improving; tactical constructive with confirmation discipline.
Base path
Observable triggers: price consolidates broadly between $72,000 and $80,000; the twenty-session flow total remains positive; short-window flows moderate without reversing.
Falsifier: either a sustained break above the range with persistent inflows or a break below it with renewed outflows.
Posture: long-term constructive; medium-term improving; tactical patient and extension-aware.
Bear path
Observable triggers: the same daily series closes below $72,000; five-session fund flows turn negative; sentiment falls back below Neutral.
Falsifier: price reclaims $76,000 with renewed multi-session inflows.
Posture: long-term thesis unchanged absent structural deterioration; medium-term cautious; tactical defensive.
These paths are qualitative research frames, not forecasts, probabilities, position sizes, or capital instructions.
Contrary Evidence and Limitations
This public release uses source-attributed observations, transparent descriptive arithmetic, and clearly labeled analyst assessments. The evidence cutoff was 2026-08-24T02:00:00Z. Price uses the FRED/Coinbase daily reference and its provider clock, not an exact cutoff trade. Fund flows are aggregator estimates and may be revised. Hashrate is inferred and window-dependent. Macro releases have their own reference dates, seasonal conventions, confidence intervals, lags, and revision policies.
The strongest contrary evidence is the speed of the move itself. Price, fund demand, and sentiment all accelerated in the same week. That alignment supports confirmation, but it also means the public evidence is now more exposed to reversal if flows weaken or price loses the new range.
The recurring governed fields are not activated. No private-shadow reading, retired score, probability, formula, weight, normalization rule, internal threshold, hash, or capital logic is included.
Meridian Strategic Conclusion
WCIR 023 marks a real change in the observable demand picture. The daily reference increased 23.51% over seven days, the five-session United States spot-fund-flow sum reached approximately +$1.918 billion, and the twenty-session total expanded to approximately +$2.336 billion. Sentiment moved from Fear to Greed. Unlike a price-only rebound, this week’s move arrived with visible institutional-demand confirmation.
That does not turn a strong week into a permanent regime. Bitcoin remained 37.75% below the reference-series high. Fund-flow data remain revision-prone, sentiment has already moved rapidly, and positive real yields remain a competing return. Network evidence was steady rather than euphoric: the completed-date hashrate estimate was approximately 910 EH/s, while difficulty adjusted modestly lower to 125.81 trillion.
Meridian’s public analyst assessment is therefore demand repair confirmed; tactical posture constructive but extension-aware. The medium-term posture improves because price and fund demand now confirm one another. The long-term posture remains constructive and thesis-led. Confirmation from here requires persistence: price holding its new range, short-window flows remaining positive, and sentiment avoiding a rapid move into excess. Failure would look like a break below the new range paired with renewed outflows. Discipline now means distinguishing confirmation from acceleration and acceleration from permanence.
Principal Sources
Principal sources include Federal Reserve Economic Data for the Bitcoin reference series, Farside Investors for displayed United States spot Bitcoin fund totals, Alternative.me for attributed market sentiment, mempool.space for network estimates and difficulty, Federal Reserve Economic Data for adjusted financial conditions, the five-year real Treasury yield, and Federal Reserve total assets, the United States Department of Labor claims release, and the Federal Reserve’s July meeting minutes release.
Editorial Note
The Bitcoin Weekly Conviction Intelligence Report is a strategic intelligence publication by Meridian Signal designed to evaluate Bitcoin through the lenses of market structure, institutional capital flows, liquidity conditions, supply dynamics, network security, and evolving risk.
Its purpose is not to predict short-term price movements or provide investment recommendations. It is designed to assess the quality of Bitcoin’s current structural position, identify meaningful changes in market conditions, and reduce uncertainty for long-term strategic decision-making.
Source-attributed observations, Meridian analyst assessments, and governed proprietary indicators are treated as separate forms of intelligence. Analyst assessments, qualitative scenarios, and horizon-specific posture represent human-directed judgments based on the evidence available at the stated cutoff. Governed numerical readings are published only after their data, methodology, validation, and activation requirements have been satisfied.
All assessments reflect the information available at the time of publication and may change as new evidence emerges.
Meridian Signal remains committed to evaluating structure over price, conditional paths over predictions, conviction over emotion, and signal over noise.
Research Disclosure
Meridian Signal uses artificial intelligence-assisted systems to accelerate public-source discovery, data comparison, research organization, arithmetic verification, and analytical synthesis. Artificial intelligence outputs are not treated as authoritative by default.
Material claims are evaluated against available sources, and all interpretations, strategic assessments, and editorial conclusions remain under institutional human direction and review. Meridian Signal retains final human editorial responsibility. Artificial intelligence has no authority to approve, publish, trade, or activate a governed Meridian indicator.
Proprietary formulas, weights, normalization rules, internal thresholds, private calculations, and calculation mechanics are not publicly disclosed. The absence of a governed reading does not imply a neutral condition; it means the applicable evidence, validation, or activation requirements have not yet been completed.
Meridian Signal
Independent Strategic Intelligence Desk
General informational analysis only. This is not individualized financial, investment, legal, tax, accounting, or custody advice. Bitcoin is volatile, and loss of principal is possible.