

Fund demand strengthened and price repaired, but persistence, broader liquidity, and accepted price confirmation are still missing.
Bitcoin | Weekly Conviction Intelligence Report
Week 32 | Evidence cutoff: August 10, 2026 at 02:00 Coordinated Universal Time
AI-assisted. Human-directed. Source-verified.
Methodology Update
Beginning with WCIR 021, the Bitcoin Weekly Conviction Intelligence Report enters its Evidence-Led Series.
Source-attributed observations, Meridian analyst assessments, and governed proprietary indicators are now presented separately. Certain former scores and probability readings have been retired. New governed indicators will remain marked Under validation until their data, methodology, validation, and activation requirements are satisfied.
WCIR 001–020 remain unchanged as the Original Series and reflect the methodology used at the time of publication. Their proprietary readings should not be compared directly with indicators introduced under the Evidence-Led Series.
The weekly WCIR continues normally. What changed is the clarity of the boundary between evidence, judgment, and proprietary calculation.
Executive Assessment
Bitcoin’s short term setup improved this week.
United States spot Bitcoin exchange-traded funds showed approximately $865.3 million in displayed net inflows across the five trading sessions through August 7. The same research price series placed Bitcoin at $64,855.50 on August 9, up 2.22% over seven days and 2.13% from the reference observation used in WCIR 020. Farside Investors Federal Reserve Economic Data
That is a real improvement. It is not yet confirmation.
The fund record still contains missing product-session cells. Price remained 48.00% below the high of the same daily reference series and about 7.52% below its trailing 200-observation average. Macro transmission was mixed. Financial conditions and some dollar-liquidity measures improved, while real yields remained restrictive and the Federal Reserve’s latest decision included three votes for a rate increase. Federal Reserve
Meridian’s analyst assessment is therefore straightforward:
Repair, not confirmed.
The evidence supports maintaining a long term position and allows only predetermined, staged accumulation. It does not support chasing the current repair, increasing medium term risk, or adding new directional leverage.
Executive Snapshot
Observed Market Data
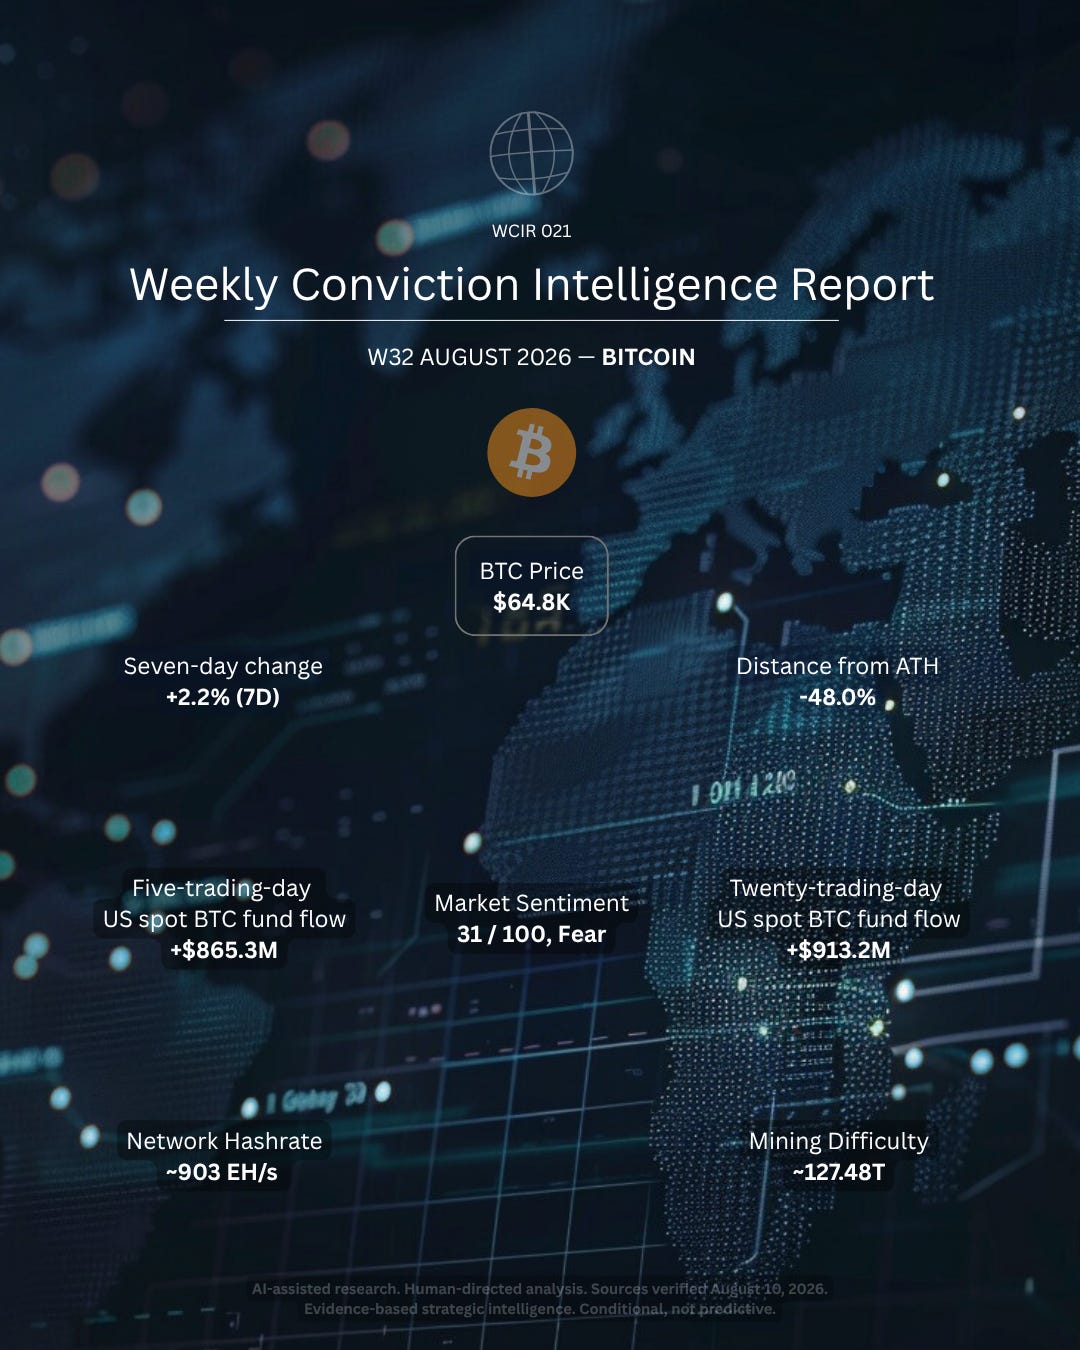
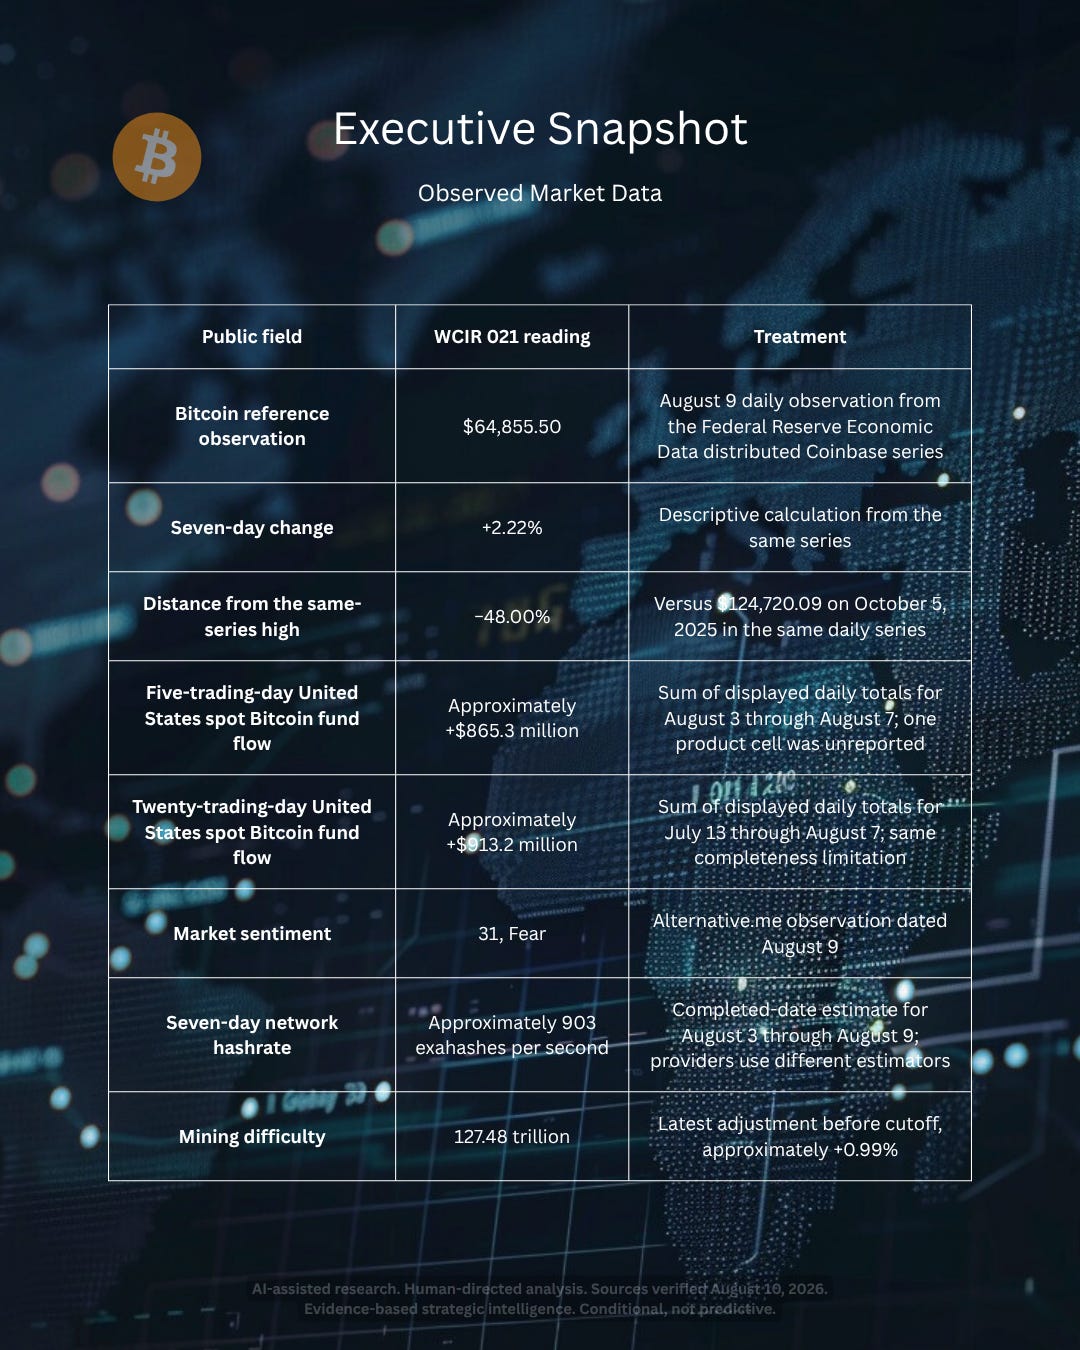
Sources: Bitcoin reference series, United States spot Bitcoin fund table, market sentiment, and network data.
Meridian Assessments
Tactical market state: Analyst assessment: Repair, not confirmed. Governed tactical state under validation; no governed classification published.
Meridian Conviction Score, Opportunity Series: Under validation. No governed reading published.
Regime Confirmation Score: Under validation. No governed reading published.
Ninety-Day Crash Risk Index: Under validation. No governed reading published.
Available Supply Tightness: Under development. Qualitative supply evidence only; no governed measure published.
Evidence Integrity Grade: Under validation. No governed grade published. Claim-level sources and limitations are disclosed instead.
Observed data are source-attributed research observations and descriptive calculations, not governed Meridian indicators. No private or unactivated reading is implied by an under-validation label.
Three Material Changes Since WCIR 020
1. Displayed fund demand improved materially
The strongest constructive signal came from the United States spot Bitcoin fund channel. Farside’s displayed daily totals were positive in all five sessions from August 3 through August 7 and summed to approximately $865.3 million. The displayed twenty-session total also moved positive to approximately $913.2 million. Farside Investors
This is meaningful because it shows renewed demand through regulated wrappers. It is not complete evidence of broad, persistent accumulation. The five-session activity was concentrated, the underlying table contained an unreported product cell on August 7, and the source is a live table that can be revised. The correct conclusion is that fund demand improved, not that institutional confirmation is complete.
2. Price repaired over seven days
Bitcoin’s August 9 reference observation was $64,855.50, compared with $63,443.93 seven days earlier. The price finished approximately 2.44% above its trailing 50-observation average, but remained approximately 7.52% below its trailing 200-observation average. Federal Reserve Economic Data
That combination matters. Shorter-term conditions improved while the longer trend remained unresolved. It supports the word repair. It does not support the word confirmed.
3. Financialization became more visible in corporate treasury behavior
Strategy disclosed that it sold 1,638 Bitcoin for $104.73 million net during July 27 through August 2. The filing says approximately $52.4 million supported preferred dividends and $52.3 million supported preferred-share repurchases. Strategy filing
This is not evidence of a market-wide corporate liquidation. It is evidence that Bitcoin inventory, equity issuance, preferred obligations, and cash requirements now operate in a two-way loop. Corporate adoption can create durable demand, but corporate financial obligations can also convert Bitcoin back into market supply. Both directions belong in the analysis now.
Three Important Non-Changes
1. The dominant Bitcoin network remains operational
Estimated network work remained near 903 exahashes per second, and mining difficulty increased to 127.48 trillion at the August 8 adjustment. The reviewed evidence did not establish a monetary fault, dominant-chain displacement, or prolonged network-liveness failure. Network data
The exact hashrate estimate varies by provider, so the number should be treated as an estimate rather than false precision. The structural message is more durable: Bitcoin continued to settle blocks under high work expenditure.
2. A new market regime has not been confirmed
One positive fund week and one repaired price week are not enough. Bitcoin remained below its longer-trend reference, macro transmission stayed mixed, and a complete view of offshore leverage, options, liquidation risk, and executable market depth was unavailable at the cutoff.
The analyst assessment remains Repair, not confirmed. The governed tactical state remains under validation.
3. No new directional leverage is justified
The better week lowers the need for defensive urgency, but it does not provide the evidence required for leverage. Opportunity, confirmation, downside fragility, tactical state, ownership risk, and evidence integrity are deliberately separated in the updated framework. Those governed readings are not active yet.
Until confirmation broadens, leverage adds sensitivity precisely where the evidence remains incomplete.
What Is Actually Happening
Bitcoin is receiving renewed sponsorship before the wider transmission system has fully confirmed it.
The demand layer improved first. Fund flows turned positive, price moved above its shorter average, and regulated positioning remained substantial. The macro layer was less decisive. The Chicago Federal Reserve’s adjusted financial-conditions reading was looser, the broad dollar index weakened across its comparison window, and reserve balances increased while the Treasury General Account and reverse repurchase balances declined. At the same time, the cutoff-valid five-year real yield was higher than twenty observations earlier, and the Federal Reserve maintained its policy rate on a nine-to-three vote with three members preferring an increase. Financial conditions Real yields Broad dollar Federal Reserve balance sheet
That is marginal relief, not a clean liquidity tailwind.
The surrounding financial system also matters more than it did in earlier cycles. Exchange-traded funds concentrate custody and benchmark dependencies. Corporate treasuries can acquire, pledge, lend, or sell Bitcoin. Wallet failures can move coins without reflecting a change in holder conviction. The deeper Bitcoin becomes embedded in financial infrastructure, the less useful it is to look at price alone.
New This Week
Three developments deserve attention beyond the dashboard.
First, Strategy’s sale tied Bitcoin directly to preferred distributions and repurchases. That makes treasury reflexivity observable rather than theoretical.
Second, Coinkite’s updated Coldcard advisory identified affected seed-generation behavior across several product models and firmware ranges. Updating firmware prevents new exposure but does not repair an existing affected seed. The event belongs to wallet and ownership infrastructure, not Bitcoin consensus. Preliminary industry estimates of the affected perimeter remain subject to revision. Coinkite advisory Independent technical analysis
Third, Bitcoin Improvement Proposal 110 is now marked Closed in the Bitcoin Improvement Proposal repository after a minority chain split and stalled mining. The episode warrants protocol monitoring, but the available evidence did not show displacement of the dominant chain. A proposal, a signaling monitor, or a short minority branch is not the same as Bitcoin-wide consensus failure. Bitcoin Improvement Proposal 110
The central distinction is important: the dominant Bitcoin network remained operational, while financial and ownership risks around it became more concrete.
Regime, Risk, and Qualitative Scenarios
No percentage is assigned to any path.
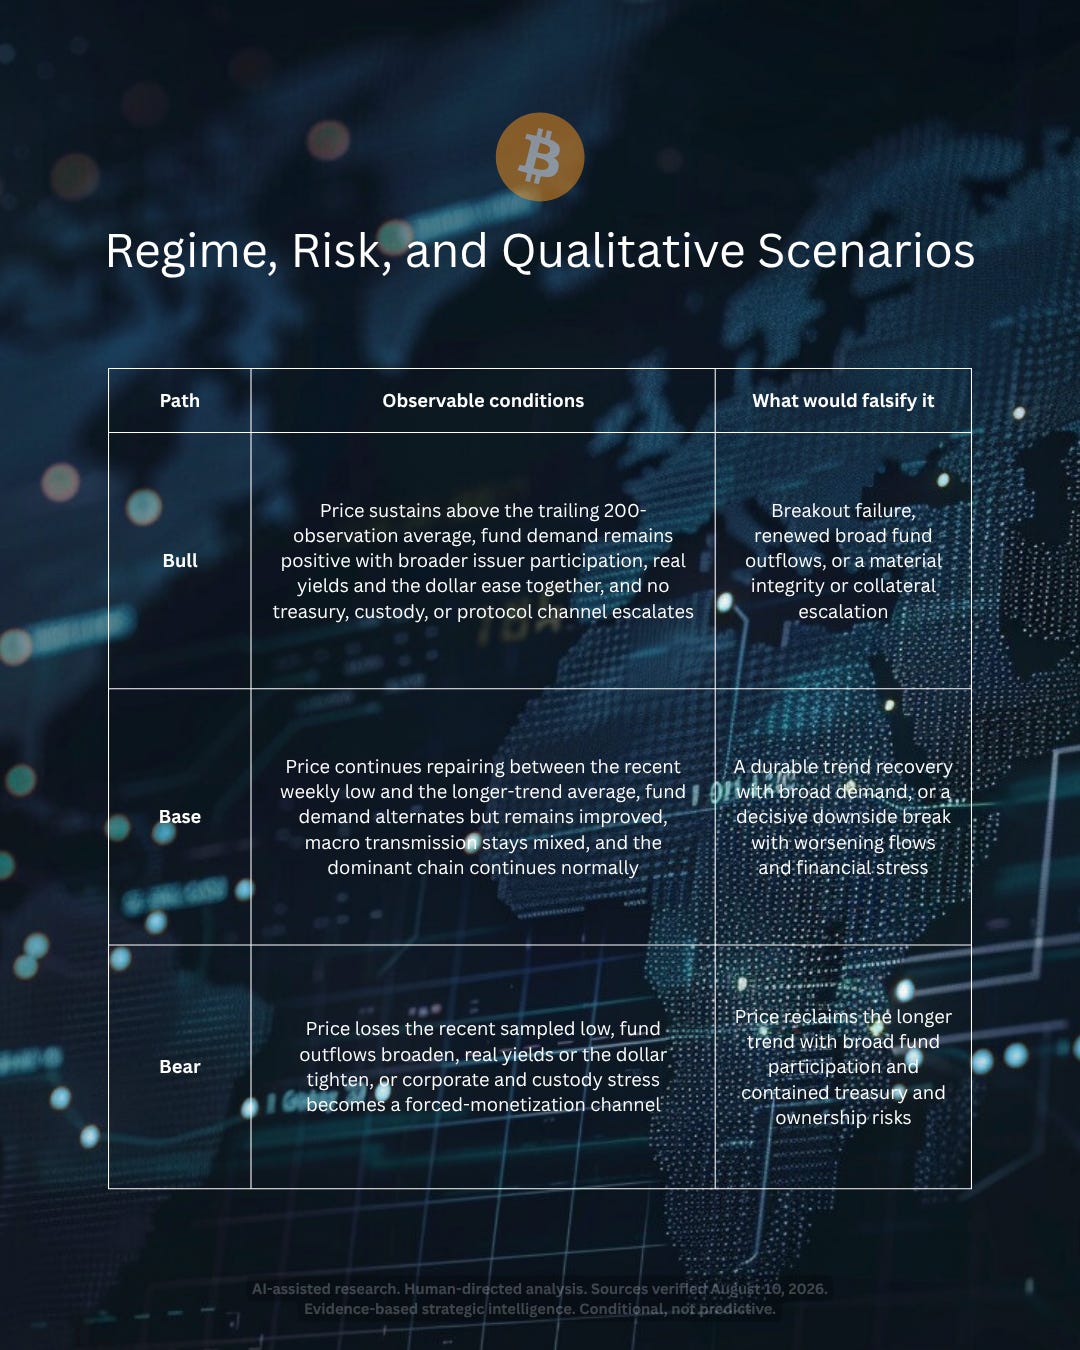
The Base path best describes the evidence at the cutoff. That is an analyst assessment, not a probability forecast.
Strategic Posture
Long term
Maintain. If adding, use predetermined staged accumulation rather than emotional chasing.
Medium term
Hold. Wait for repeated broad fund demand and longer-trend price confirmation.
Tactical
Defensive-neutral. The repair is constructive, but it is not a confirmed trend transition.
Leverage
Add no new directional leverage.
This posture separates the long term Bitcoin thesis from the timing of additional risk. A stronger week can improve the setup without requiring immediate action.
Trigger Map
Further demand improvement: Another complete positive five-session fund window with broader issuer participation
Longer-trend confirmation: Sustained daily observations above the trailing 200-observation average, approximately $70,127 at the cutoff, together with persistent fund demand
Initial deterioration: Repeated daily observations below the August 3 through August 9 sampled low of approximately $63,503, especially with a reversal in fund flows
Macro confirmation: Real yields and the broad dollar ease together while financial conditions remain supportive
Treasury escalation: Additional material Bitcoin sales explicitly used to fund recurring corporate obligations
Ownership escalation: A wider confirmed wallet-loss perimeter or a new cross-vendor custody failure
Protocol escalation: Dominant-chain displacement, sustained liveness failure, an inflation fault, or meaningful economic recognition of a competing ruleset
No single print should change the conclusion by itself. The next increase or reduction in risk should be earned by a cluster of evidence.
Contrary Evidence and Limitations
The five-session and twenty-session fund values are sums of Farside’s displayed daily totals. The table contained unreported issuer cells and remains subject to live revision, so these values are best read as strong directional evidence rather than a complete governed issuer ledger.
The Bitcoin price is a cited research observation from the Federal Reserve Economic Data distributed Coinbase series. It is not a live execution price, and the series carries provider copyright and timing limitations. The hashrate figure is an estimate; public providers differed because they use different intervals and estimators. Market sentiment is a third-party composite, not a Meridian indicator.
The macro series arrive on different release clocks and may be revised. Complete consolidated leverage, options-surface, liquidation, and market-depth data were unavailable at the cutoff. Coldcard loss estimates remain preliminary. Bitcoin Improvement Proposal 110 evidence supports a bounded minority-chain event, not a formal governed Protocol Integrity classification.
These limitations do not erase the improvement. They define how far the conclusion can responsibly go.
Meridian Strategic Conclusion
Bitcoin improved where it needed to improve: demand reappeared and price repaired. What remains missing is persistence.
The five displayed United States spot Bitcoin fund sessions through August 7 summed to approximately $865.3 million, and the twenty-session total moved positive. Bitcoin gained 2.22% over seven days and finished above its shorter reference average. Those are constructive changes.
They are not enough to declare a new regime.
The fund record remains incomplete at the issuer level. Price remains below its longer-trend average and far below the high of the same daily series. Macro transmission is mixed rather than decisively supportive. Strategy’s disclosed Bitcoin sale also shows that corporate adoption has become a two-way financial channel, while the Coldcard incident reminds us that ownership infrastructure can create market-visible movement without any failure of Bitcoin’s monetary system.
The network itself remains the strongest part of the picture. Work expenditure stayed high, difficulty increased, and the reviewed evidence did not establish a dominant-chain monetary or liveness failure. The main uncertainty sits around persistence, liquidity, financialization, and custody.
Meridian’s posture is therefore steady. Maintain long term exposure. Use only predetermined staged accumulation. Wait for broader demand and longer-trend confirmation before increasing medium term risk. Remain defensive-neutral tactically. Add no new directional leverage.
The opportunity, confirmation, downside fragility, tactical state, and evidence-grade indicators remain under validation. No substitute number is being published in their place.
Institutional verdict: The evidence is better than it was last week. The market has not yet earned the next increase in risk.
Principal Sources
Principal sources include Federal Reserve Economic Data for the Bitcoin reference series, Farside Investors for displayed United States spot Bitcoin fund totals, Alternative.me for attributed market sentiment, mempool.space for network estimates and difficulty, the Federal Reserve balance sheet, the Federal Reserve policy statement, Strategy’s August 3 filing, the Coinkite security advisory, and the Bitcoin Improvement Proposal 110 repository record.
Editorial Note
The Bitcoin Weekly Conviction Intelligence Report (WCIR) is a strategic intelligence publication by Meridian Signal designed to evaluate Bitcoin through the lenses of market structure, institutional capital flows, liquidity conditions, supply dynamics, network security, and evolving risk.
Its purpose is not to predict short-term price movements or provide investment recommendations. It is designed to assess the quality of Bitcoin’s current structural position, identify meaningful changes in market conditions, and reduce uncertainty for long-term strategic decision-making.
Source-attributed observations, Meridian analyst assessments, and governed proprietary indicators are treated as separate forms of intelligence. Analyst assessments, qualitative scenarios, strategic posture, and positioning conclusions represent human-directed judgments based on the evidence available at the stated cutoff. Governed numerical readings are published only after their data, methodology, validation, and activation requirements have been satisfied.
All assessments reflect the information available at the time of publication and may change as new evidence emerges.
Meridian Signal remains committed to evaluating structure over price, conditional paths over predictions, conviction over emotion, and signal over noise.
Research Disclosure
Meridian Signal uses artificial intelligence-assisted systems to accelerate source discovery, data comparison, research organization, and analytical synthesis. Artificial intelligence outputs are not treated as authoritative by default.
Material claims are evaluated against available sources, and all interpretations, strategic assessments, and editorial conclusions remain under human direction and review.
Proprietary formulas, weights, normalization rules, internal thresholds, private calculations, and calculation mechanics are not publicly disclosed. The absence of a governed reading does not imply a neutral condition; it means the applicable evidence, validation, or activation requirements have not yet been completed.
Meridian Signal
Independent Strategic Intelligence Desk
General informational analysis only. This is not individualized financial, investment, legal, or tax advice.